Strategy vault / Machine learning
3 Min Short Only Expert Advisor Strategy
This is a 3-min short-only expert advisor strategy for E-mini S&P500 futures (ES). It generates trading signals by calculating a series of exponential moving averages and combining specific pattern conditions.
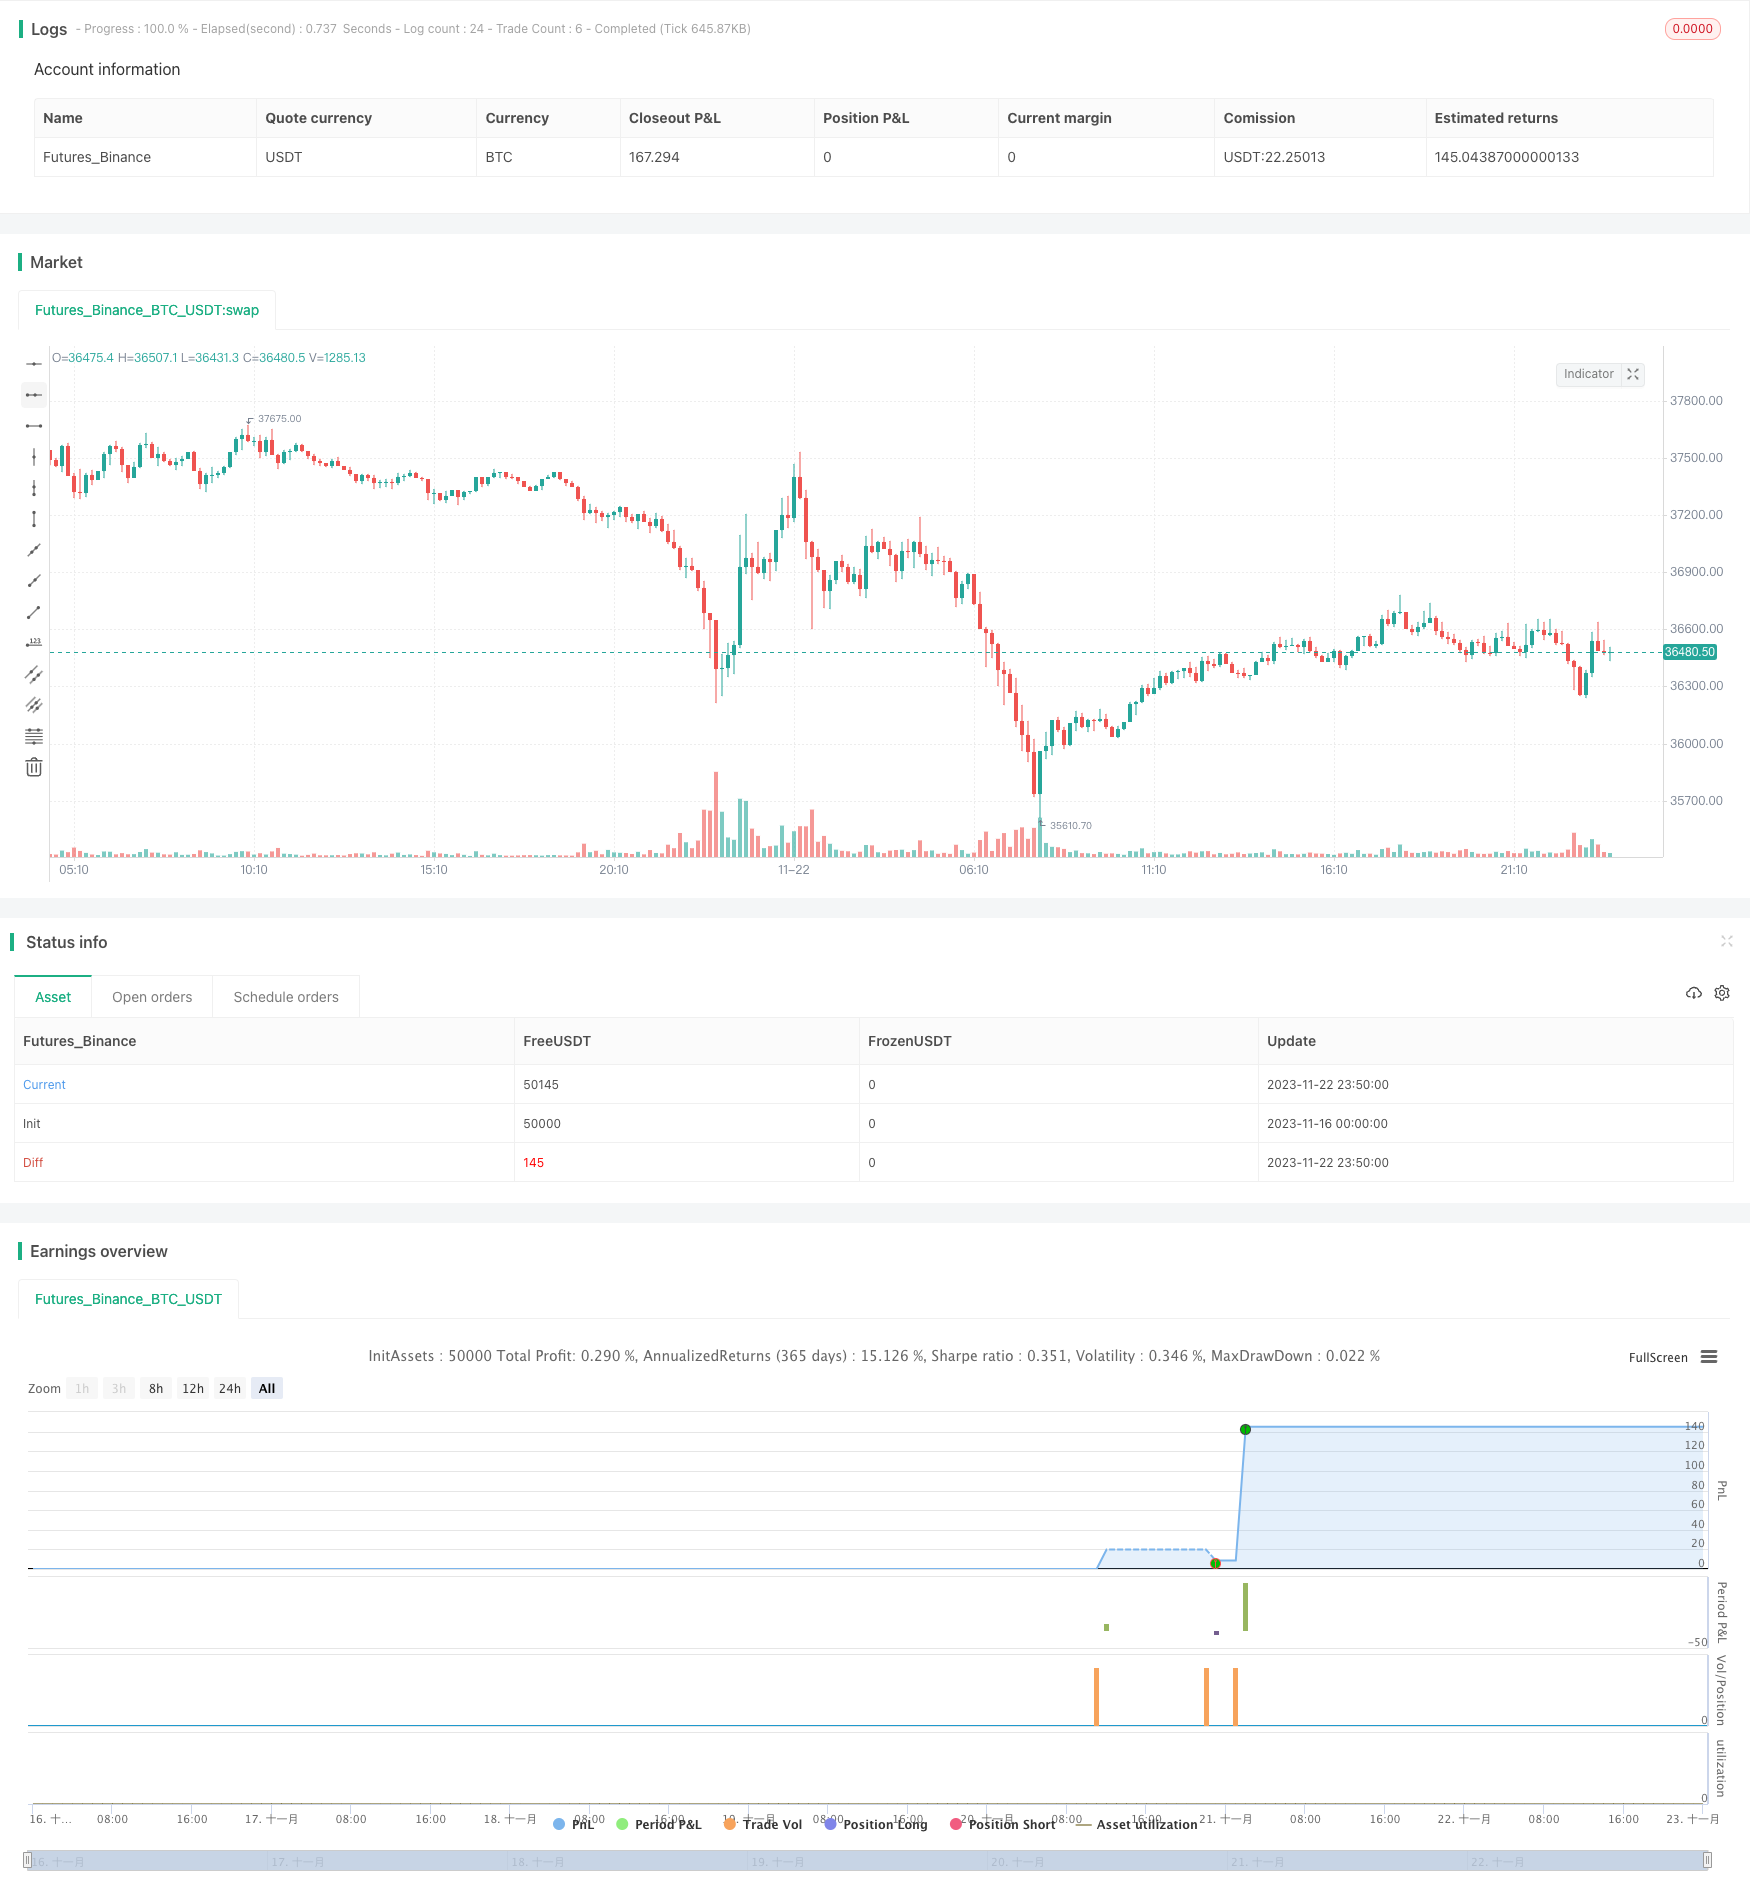
Overview
This is a 3-min short-only expert advisor strategy for E-mini S&P500 futures (ES). It generates trading signals by calculating a series of exponential moving averages and combining specific pattern conditions.
Principles
The core indicator of this strategy is the T3 average line. The T3 first calculates a set of exponential moving averages xe1~xe6 based on the user-defined T3 parameter. Then it calculates the weighted average of these EMAs using specific coefficients as the final T3 average line.
When the close price is below the T3 average line, a buy signal is generated. When the close price is above the T3 average line, a sell signal is generated. In addition, the strategy also judges specific candlestick patterns as supplementary entry conditions. Trading orders will only be sent out when both pattern conditions and T3 signals emerge at the same time.
Strengths
The biggest strength of this strategy lies in multi-filter design and parameter optimization. On one hand, combining price action and chart pattern filters can reduce noise trades. On the other hand, key parameters like T3 and pattern judging rules can be optimized to adapt to different markets and improve entry accuracy.
Compared to simple moving averages, the triple smoothing mechanism of the T3 indicator is effective in filtering out market noise and identifying trend reversal points. The 3-min timeframe allows fast order execution to capture short-term opportunities.
Risks & Solutions
The main risks of this strategy come from inappropriate parameter tuning and oversized holding period. If T3 parameter is set too large, the indicators will lag behind the market; if set too small, it increases the probability of noise trades. In addition, 3-min operations can face huge loss without timely stop loss.
To control risks, the first thing is to repeatedly backtest to determine the optimal parameter range for different products. Secondly, a strict stop loss strategy should be executed to exit positions with acceptable loss percentage per trade.
Improvements
There are several directions to improve the strategy:
Optimize T3 parameter to find the optimal range for different trading instruments
Improve pattern judging logic to increase accuracy of pattern recognition
Add more advanced stop loss mechanisms like trailing stop loss
Add money management module based on profit factor or max drawdown
Add machine learning assisted entry module
Through these improvements, the stability and profitability of the strategy can be enhanced step by step.
Conclusion
As a short-term intraday trading strategy, this strategy has advantages like huge optimization space, multiple filters and fast order execution. With a series of optimization methods like parameter tuning, stop loss optimization, money management, it can be tuned into an effective strategy suitable for high frequency trading.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 150 | T3 |
Source Pine Script
/*backtest
start: 2023-11-16 00:00:00
end: 2023-11-23 00:00:00
period: 10m
basePeriod: 1m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("ES 3m Short Only (Triple RED)", overlay=true)
// Alert Message '{{strategy.order.alert_message}}'
//3min
T3 = input(150)//to 600

xPrice3 = close
xe1 = ta.ema(xPrice3, T3)
xe2 = ta.ema(xe1, T3)
xe3 = ta.ema(xe2, T3)
xe4 = ta.ema(xe3, T3)
xe5 = ta.ema(xe4, T3)
xe6 = ta.ema(xe5, T3)

b3 = 0.7
c1 = -b3*b3*b3
c2 = 3*b3*b3+3*b3*b3*b3
c3 = -6*b3*b3-3*b3-3*b3*b3*b3
c4 = 1+3*b3+b3*b3*b3+3*b3*b3
nT3Average = c1 * xe6 + c2 * xe5 + c3 * xe4 + c4 * xe3

// Buy Signal - Price is below T3 Average
buySignal3 = xPrice3 < nT3Average
sellSignal3 = xPrice3 > nT3Average

//NinjaTrader Settings.
acct = "Sim101"
ticker = "ES 12-23"
qty = 1
takeProfitTicks = 4
stopLossTicks = 16
tickSize = 0.25

takeProfitShort = close - takeProfitTicks * tickSize
stopLossShort = close + stopLossTicks * tickSize

OCOMarketShort = '{ "alert": "OCO Market Short", "account": "' + str.tostring(acct) + '", "ticker": "' + str.tostring(ticker) + '", "qty": "' + str.tostring(qty) + '", "take_profit_price": "' + str.tostring(takeProfitShort) + '", "stop_price": "' + str.tostring(stopLossShort) + '", "tif": "DAY" }'
CloseAll = '{ "alert": "Close All", "account": "' + str.tostring(acct) + '", "ticker": "' + str.tostring(ticker) + '" }'

IsUp = close > open
IsDown = close < open
PatternPlot = IsDown[2] and IsDown[1] and IsDown and close[1] <= high[0] and close[1] > close[0] and low[1] > low[0] and high[2] > high[1] and low[2] <= low[1]
if (PatternPlot and sellSignal3)
    strategy.entry('Short', strategy.short, alert_message=OCOMarketShort)
    strategy.exit('Close Short', 'Short', profit=takeProfitTicks, loss=stopLossTicks, alert_message=CloseAll)

//plotshape(PatternPlot, title="Custom Pattern", style=shape.circle, location=location.abovebar, color=color.red, size=size.small)
Published by ChaoZhang on the FMZ strategy square · last modified 2023-11-24. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/3-Min-Short-Only-Expert-Advisor-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- AI Driven Dynamic Volatility Adaptive Trend Breakout Trading StrategyPine Script · Machine learning · 2d
- Dual Moving Average Matching Strategy Based on Bollinger BandsPine Script · Machine learning · 1h
- Dynamic Weighted Moving Average Trading StrategyPine Script · Machine learning · 1d
- EMA and RSI Quantitative Trading StrategyPine Script · Machine learning · 1h
- MACD Robot Trading StrategyPine Script · Machine learning · 1d
- Multi Indicator Dynamic Adaptive Quantitative Trading StrategyPine Script · Machine learning · 1h