Strategy vault / Mean reversion
3EMA with Stochastic RSI Strategy
This is a trend following strategy combining multiple indicators. It uses three EMAs with different periods, Stochastic RSI and ATR to identify trend direction and establish positions. It goes long when the faster…
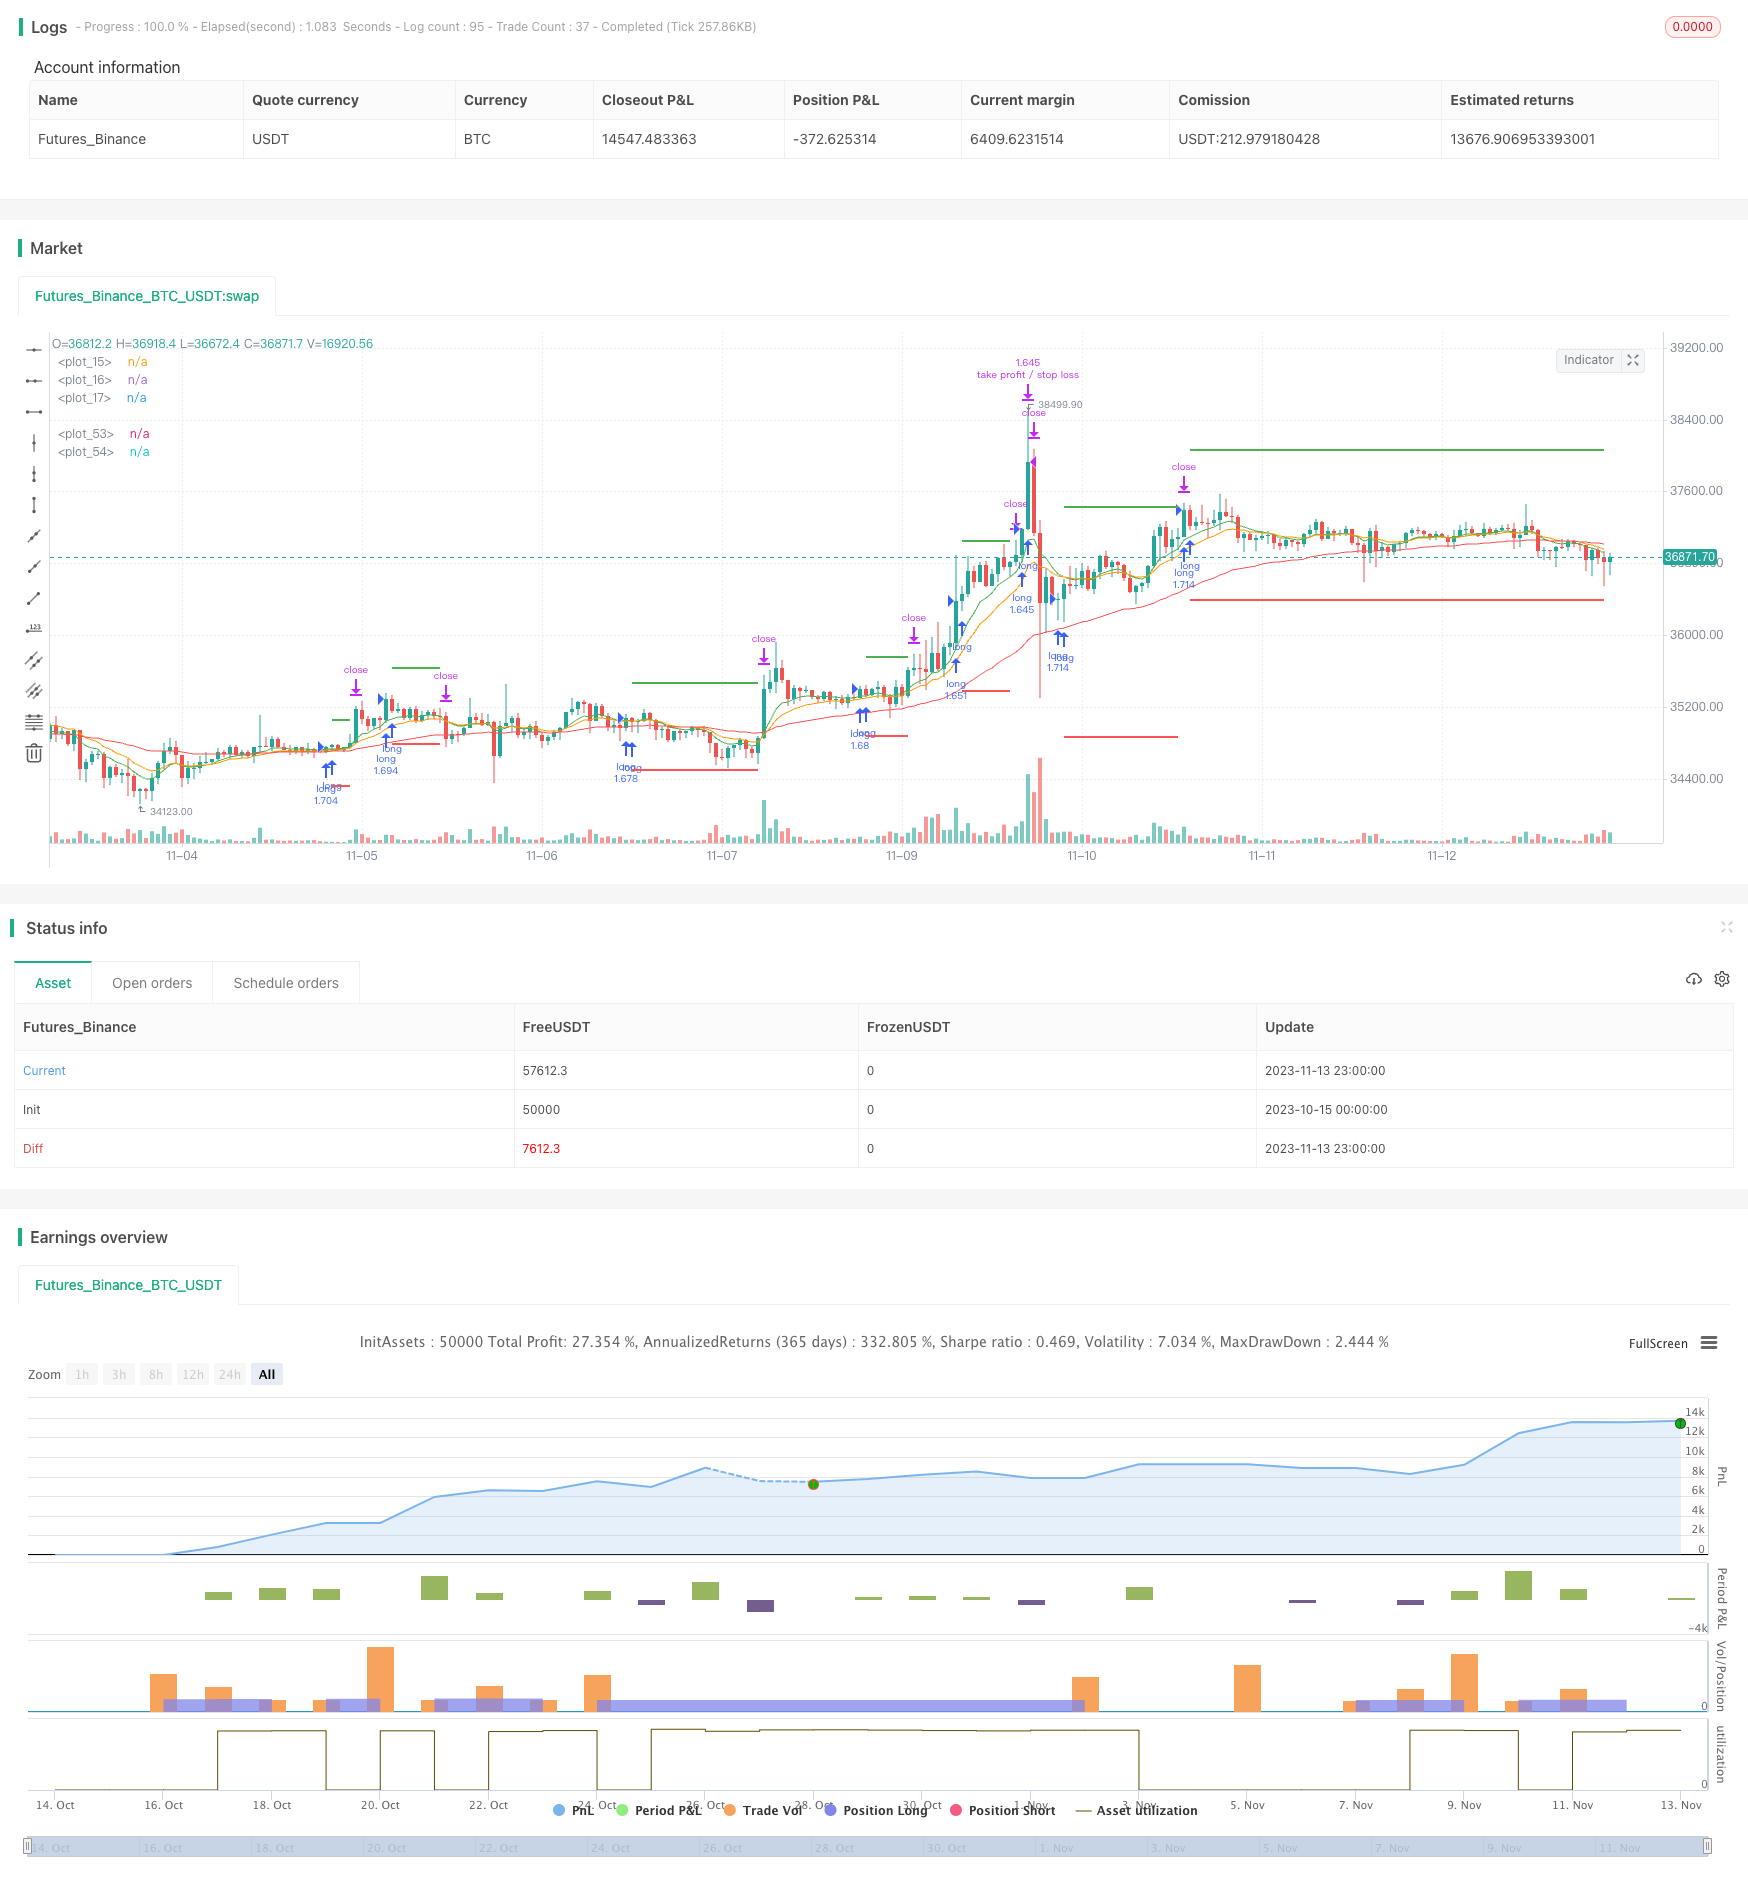
Overview
This is a trend following strategy combining multiple indicators. It uses three EMAs with different periods, Stochastic RSI and ATR to identify trend direction and establish positions. It goes long when the faster EMA crosses above the slower EMA, with stop loss set at 3 times the recent ATR value and take profit at 2 times the recent ATR.
Principle
The strategy uses three EMA lines - 8-, 14- and 50-period EMAs, representing price trends over different timeframes. When the 8-period EMA crosses above the 14-period EMA, and the 14-period EMA crosses above the 50-period EMA, it signals the start of an uptrend and a long position can be initiated.
The Stochastic RSI indicator incorporates RSI and Stochastic calculations to identify overbought/oversold conditions. When the Stochastic RSI K line crosses above the D line from below, it suggests the market is transitioning from oversold to bullish outlook, allowing a long position.
ATR represents the recent volatility range. The strategy uses 3 times ATR as stop loss distance and 2 times ATR as take profit distance to lock in profits and control risk.
Advantages
- EMAs filter out noise in price data and identify trend direction
- Stochastic RSI identifies reversal opportunities
- ATR dynamically trails stop loss/take profit based on market volatility
Risks
- Multiple indicators may generate conflicting signals
- Fixed stop loss/take profit ratios cannot adapt to changing market conditions
- Short-term longs susceptible to reversals
Optimization can be done by adjusting EMA periods to optimize sensitivity. Making ATR ratios adjustable allows customization based on market conditions. Adding other indicators helps validate signals and avoid mistakes.
Enhancement
- Adjust EMA periods to optimize sensitivity
- Make ATR ratios adjustable
- Add other indicators to avoid false signals
Conclusion
The strategy considers trend, overbought/oversold levels, and volatility range to identify entry timing. EMAs and Stochastic RSI combined effectively identify trends, while ATR's dynamic stop loss/take profit helps risk control. With parameter tuning and optimizations, the strategy can become a reliable trend following system. But false signals and fixed stop loss/take profit caveats need to be watched out for.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 8 | EMA1 Length |
| v_input_2 | 14 | EMA2 Length |
| v_input_3 | 50 | EMA3 Length |
| v_input_4 | 3 | K |
| v_input_5 | 3 | D |
| v_input_6 | 14 | RSI Length |
| v_input_7 | 14 | Stochastic Length |
| v_input_8_close | 0 | RSI Source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_9 | 14 | ATR Period |
| v_input_10 | 2 | Take-profit Multiplier |
| v_input_11 | 3 | Stop-loss Multiplier |
Source Pine Script
/*backtest
start: 2023-10-15 00:00:00
end: 2023-11-14 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © FreddieChopin

//@version=4
strategy("3 x EMA + Stochastic RSI + ATR", overlay = true, default_qty_type = strategy.percent_of_equity, default_qty_value = 100)

// 3x EMA
ema1Length = input(8, "EMA1 Length", minval = 1)
ema2Length = input(14, "EMA2 Length", minval = 1)
ema3Length = input(50, "EMA3 Length", minval = 1)
ema1 = ema(close, ema1Length)
ema2 = ema(close, ema2Length)
ema3 = ema(close, ema3Length)

plot(ema1, color = color.green)
plot(ema2, color = color.orange)
plot(ema3, color = color.red)

// Stochastic RSI
smoothK = input(3, "K", minval=1)
smoothD = input(3, "D", minval=1)
lengthRSI = input(14, "RSI Length", minval=1)
lengthStoch = input(14, "Stochastic Length", minval=1)
src = input(close, title="RSI Source")
rsi1 = rsi(src, lengthRSI)
k = sma(stoch(rsi1, rsi1, rsi1, lengthStoch), smoothK)
d = sma(k, smoothD)

// ATR
atrPeriod = input(14, "ATR Period")
takeProfitMultiplier= input(2.0, "Take-profit Multiplier")
stopLossMultiplier= input(3.0, "Stop-loss Multiplier")
atrSeries = atr(atrPeriod)[1]

longCondition = ema1 > ema2 and ema2 > ema3 and crossover(k, d)
strategy.entry("long", strategy.long, when = longCondition)

float stopLoss = na
float takeProfit = na

if (strategy.position_size > 0)
    if (na(stopLoss[1]))
        stopLoss := strategy.position_avg_price - atrSeries * stopLossMultiplier
    else
        stopLoss := stopLoss[1]
    if (na(takeProfit[1]))
        takeProfit := strategy.position_avg_price + atrSeries * takeProfitMultiplier
    else
        takeProfit := takeProfit[1]

    strategy.exit("take profit / stop loss", limit = takeProfit, stop = stopLoss)

plot(stopLoss, color = color.red, linewidth = 2, style = plot.style_linebr)
plot(takeProfit, color = color.green, linewidth = 2, style = plot.style_linebr)Published by ChaoZhang on the FMZ strategy square · last modified 2023-11-15. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/3EMA-with-Stochastic-RSI-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Dynamic Adaptive Multi Timeframe Trend Following and Range Reversal Hybrid StrategyPine Script · Mean reversion · 2d
- Oma and Apollo Dual Rail Trading StrategyPine Script · Mean reversion · 5m
- Multi Indicator Weighted Smart Trading StrategyPine Script · Mean reversion · 2d
- Dual Moving Average Stochastic StrategyPine Script · Mean reversion · 1d
- Advanced 15 Minute Chart Trading Signal StrategyPine Script · Mean reversion · 3h
- Advanced Momentum EMA Trend Following with RSI Overbought Oversold Trading StrategyPine Script · Mean reversion · 1d