Adaptive Backtest Date Range Selection Strategy Based on Double MA
The core idea of this strategy is to implement a framework that can flexibly select the backtest date range to meet different needs of users, so that they can automatically or manually set the start and end times for…
Overview
The core idea of this strategy is to implement a framework that can flexibly select the backtest date range to meet different needs of users, so that they can automatically or manually set the start and end times for backtest.
The strategy provides four options for date range selection through input parameters: using all history data, recent specified days, recent specified weeks or manually specifying a date range. The strategy will dynamically set the backtest window based on the selected date range, while keeping the trading logic unchanged, so that the performance difference under different time windows can be compared.
Strategy Principle
The strategy consists of two modules: backtest date range selection and double MA trading strategy.
Backtest Date Range Selection Module
- Provides four options for date range selection: all history data (ALL), recent specified days (DAYS), recent specified weeks (WEEKS), manually specified date range (MANUAL).
- Dynamically sets the backtest start and end time based on timestamp conversion of the selected range.
- Uses time condition window() function to filter candles and only do backtest within selected date range.
Double MA Trading Strategy Module
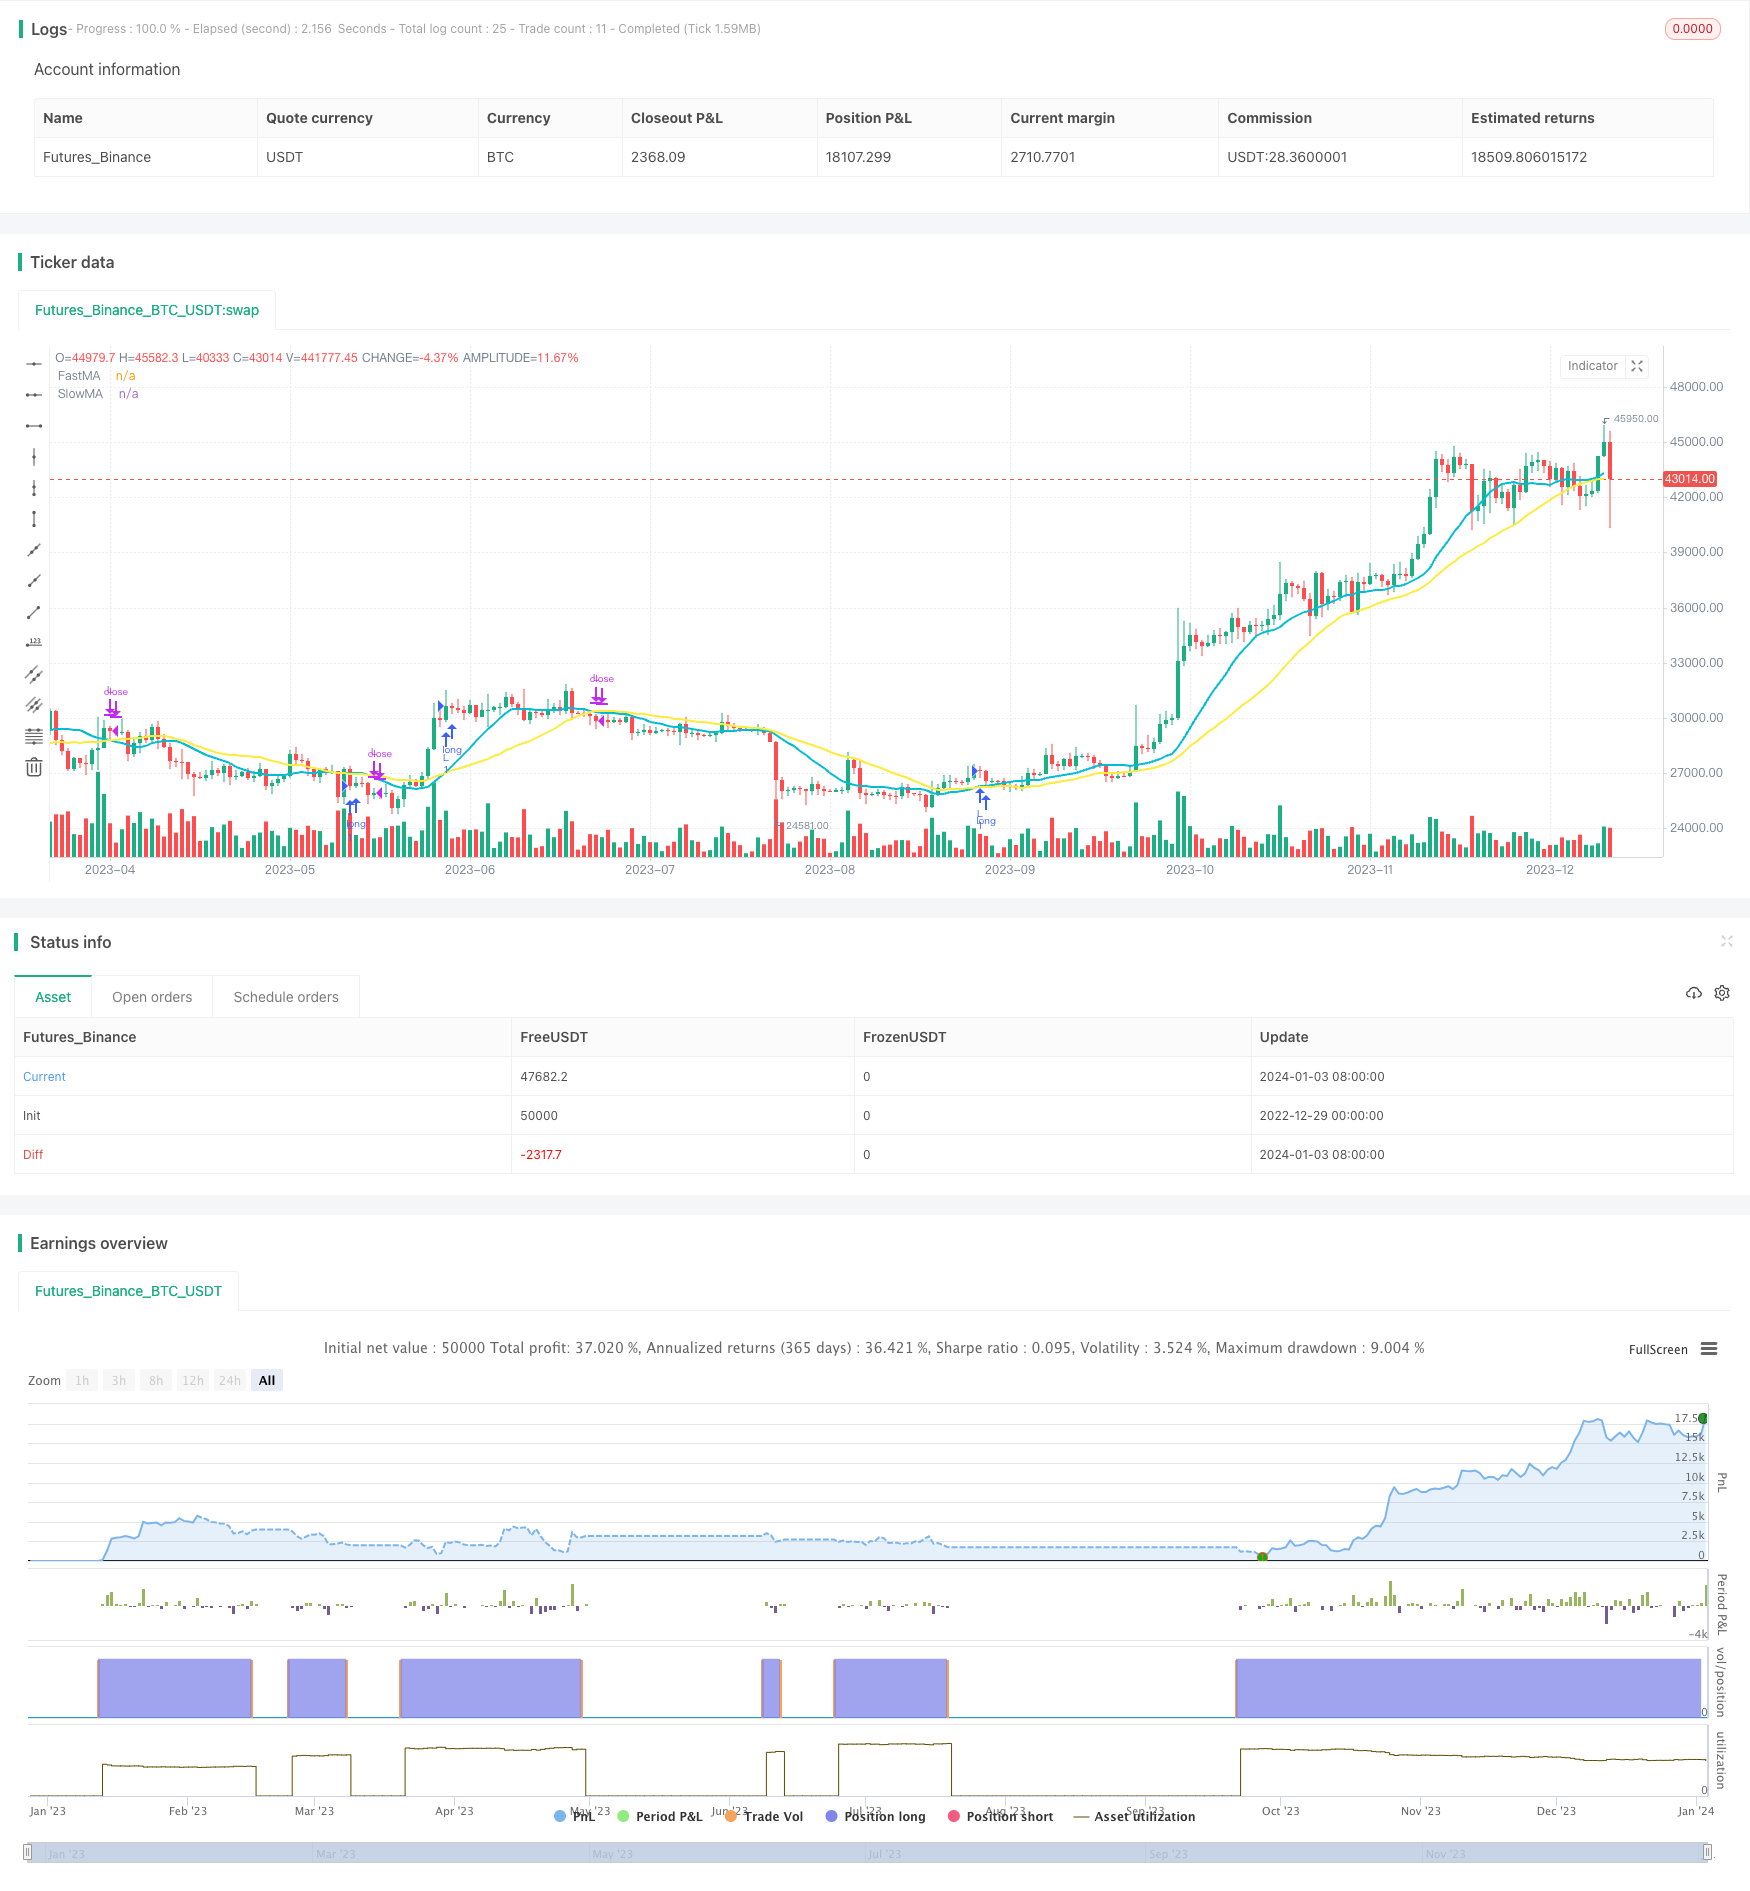
- Fast MA period is fastMA, default 14; slow MA period is slowMA, default 28.
- Long when fast MA crosses over slow MA; close position when fast MA crosses below slow MA.
- Plots fast and slow MA curves.
Analysis of Advantages
- Flexibly selects different backtest date ranges without limitation to meet different experimental needs.
- Can test the effects of different period parameters within the same time frame with comparability of results.
- Easy to modify trading logic to serve as framework for other strategies.
- Simple to understand double MA strategy, easy for beginners.
Analysis of Risks and Solutions
- Double MA strategy is crude with frequent buying/selling issues. Consider adding stop loss etc. for optimization.
- Manually setting date range needs caution to avoid errors. Can show alert messages.
- Long history backtest increases test cycle. Can consider adding slippage or fees to reduce frequent trades.
Directions for Strategy Optimization
- Add stop loss logic to lower risk of loss.
- Filter stocks with stocks pool by strong index relevance for higher stability.
- Add filters to remove unstable signals within certain periods to reduce unnecessary trades.
- Test performances of stocks indexes to find the best varieties.
Conclusion
As a flexible and customizable framework for date range selection, the advantages are meeting different test needs of users. Combined with simple but effective double MA trading logic, it can quickly verify and compare strategies. Follow-up optimizations like adding filters or stop loss logic can make the strategy more practical for live trading. In summary, the strategy framework has good scalability and reference value.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 14 | FastMA |
| v_input_2 | 28 | SlowMA |
| v_input_3 | 0 | Date Range: WEEKS | DAYS | ALL | MANUAL |
| v_input_4 | 52 | # Days or Weeks |
| v_input_5 | 9 | From Month |
| v_input_6 | 15 | From Day |
| v_input_7 | 2019 | From Year |
| v_input_8 | 12 | To Month |
| v_input_9 | 31 | To Day |
| v_input_10 | 9999 | To Year |
Source Pine Script
/*backtest
start: 2022-12-29 00:00:00
end: 2024-01-04 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4

strategy(title = "How To Auto Set Date Range", shorttitle = " ", overlay = true)

// Revision:        1
// Author:          @allanster

// === INPUT MA ===
fastMA = input(defval = 14, title = "FastMA", type = input.integer, minval = 1, step = 1)
slowMA = input(defval = 28, title = "SlowMA", type = input.integer, minval = 1, step = 1)

// === INPUT BACKTEST RANGE ===
useRange     = input(defval = "WEEKS", title = "Date Range", type = input.string, confirm = false, options = ["ALL", "DAYS", "WEEKS", "MANUAL"])
nDaysOrWeeks = input(defval = 52, title = "# Days or Weeks", type = input.integer, minval = 1)
FromMonth    = input(defval = 9, title = "From Month", minval = 1, maxval = 12)
FromDay      = input(defval = 15, title = "From Day", minval = 1, maxval = 31)
FromYear     = input(defval = 2019, title = "From Year", minval = 2014)
ToMonth      = input(defval = 12, title = "To Month", minval = 1, maxval = 12)
ToDay        = input(defval = 31, title = "To Day", minval = 1, maxval = 31)
ToYear       = input(defval = 9999, title = "To Year", minval = 2014)

// === FUNCTION EXAMPLE ===
window() => true

// === LOGIC ===
buy  = crossover(sma(close, fastMA), sma(close, slowMA))         // buy when fastMA crosses over slowMA
sell = crossunder(sma(close, fastMA), sma(close, slowMA))        // sell when fastMA crosses under slowMA

// === EXECUTION ===
strategy.entry("L", strategy.long, when=window() and buy)        // buy long when "within window of time" AND crossover
strategy.close("L", when=window() and sell)                      // sell long when "within window of time" AND crossunder

// === PLOTTING ===
plot(sma(close, fastMA), title = 'FastMA', color = color.aqua, linewidth = 2, style = plot.style_line)    // plot FastMA
plot(sma(close, slowMA), title = 'SlowMA', color = color.yellow, linewidth = 2, style = plot.style_line)  // plot SlowMA
Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-05. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Adaptive-Backtest-Date-Range-Selection-Strategy-Based-on-Double-MA.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Angle Attack Follow Line IndicatorPine Script · Other · 15m
- Customizable Backtest Start Time StrategyPine Script · Other · 2d
- Gann High LowPine Script · Other · 4h
- MACD StrategyPine Script · Other
- Monthly Performance PnL Calendar StrategyPine Script · Other · 1d
- QQE MOD SSL Hybrid Waddah Attar ExplosionPine Script · Other · 4h