Strategy vault / Trend following
Adaptive Bollinger Bands Trend Tracking Strategy
This strategy uses adaptive Bollinger Bands indicator to identify the trend direction and market orders to track the trend with stop loss for efficient trend trading.
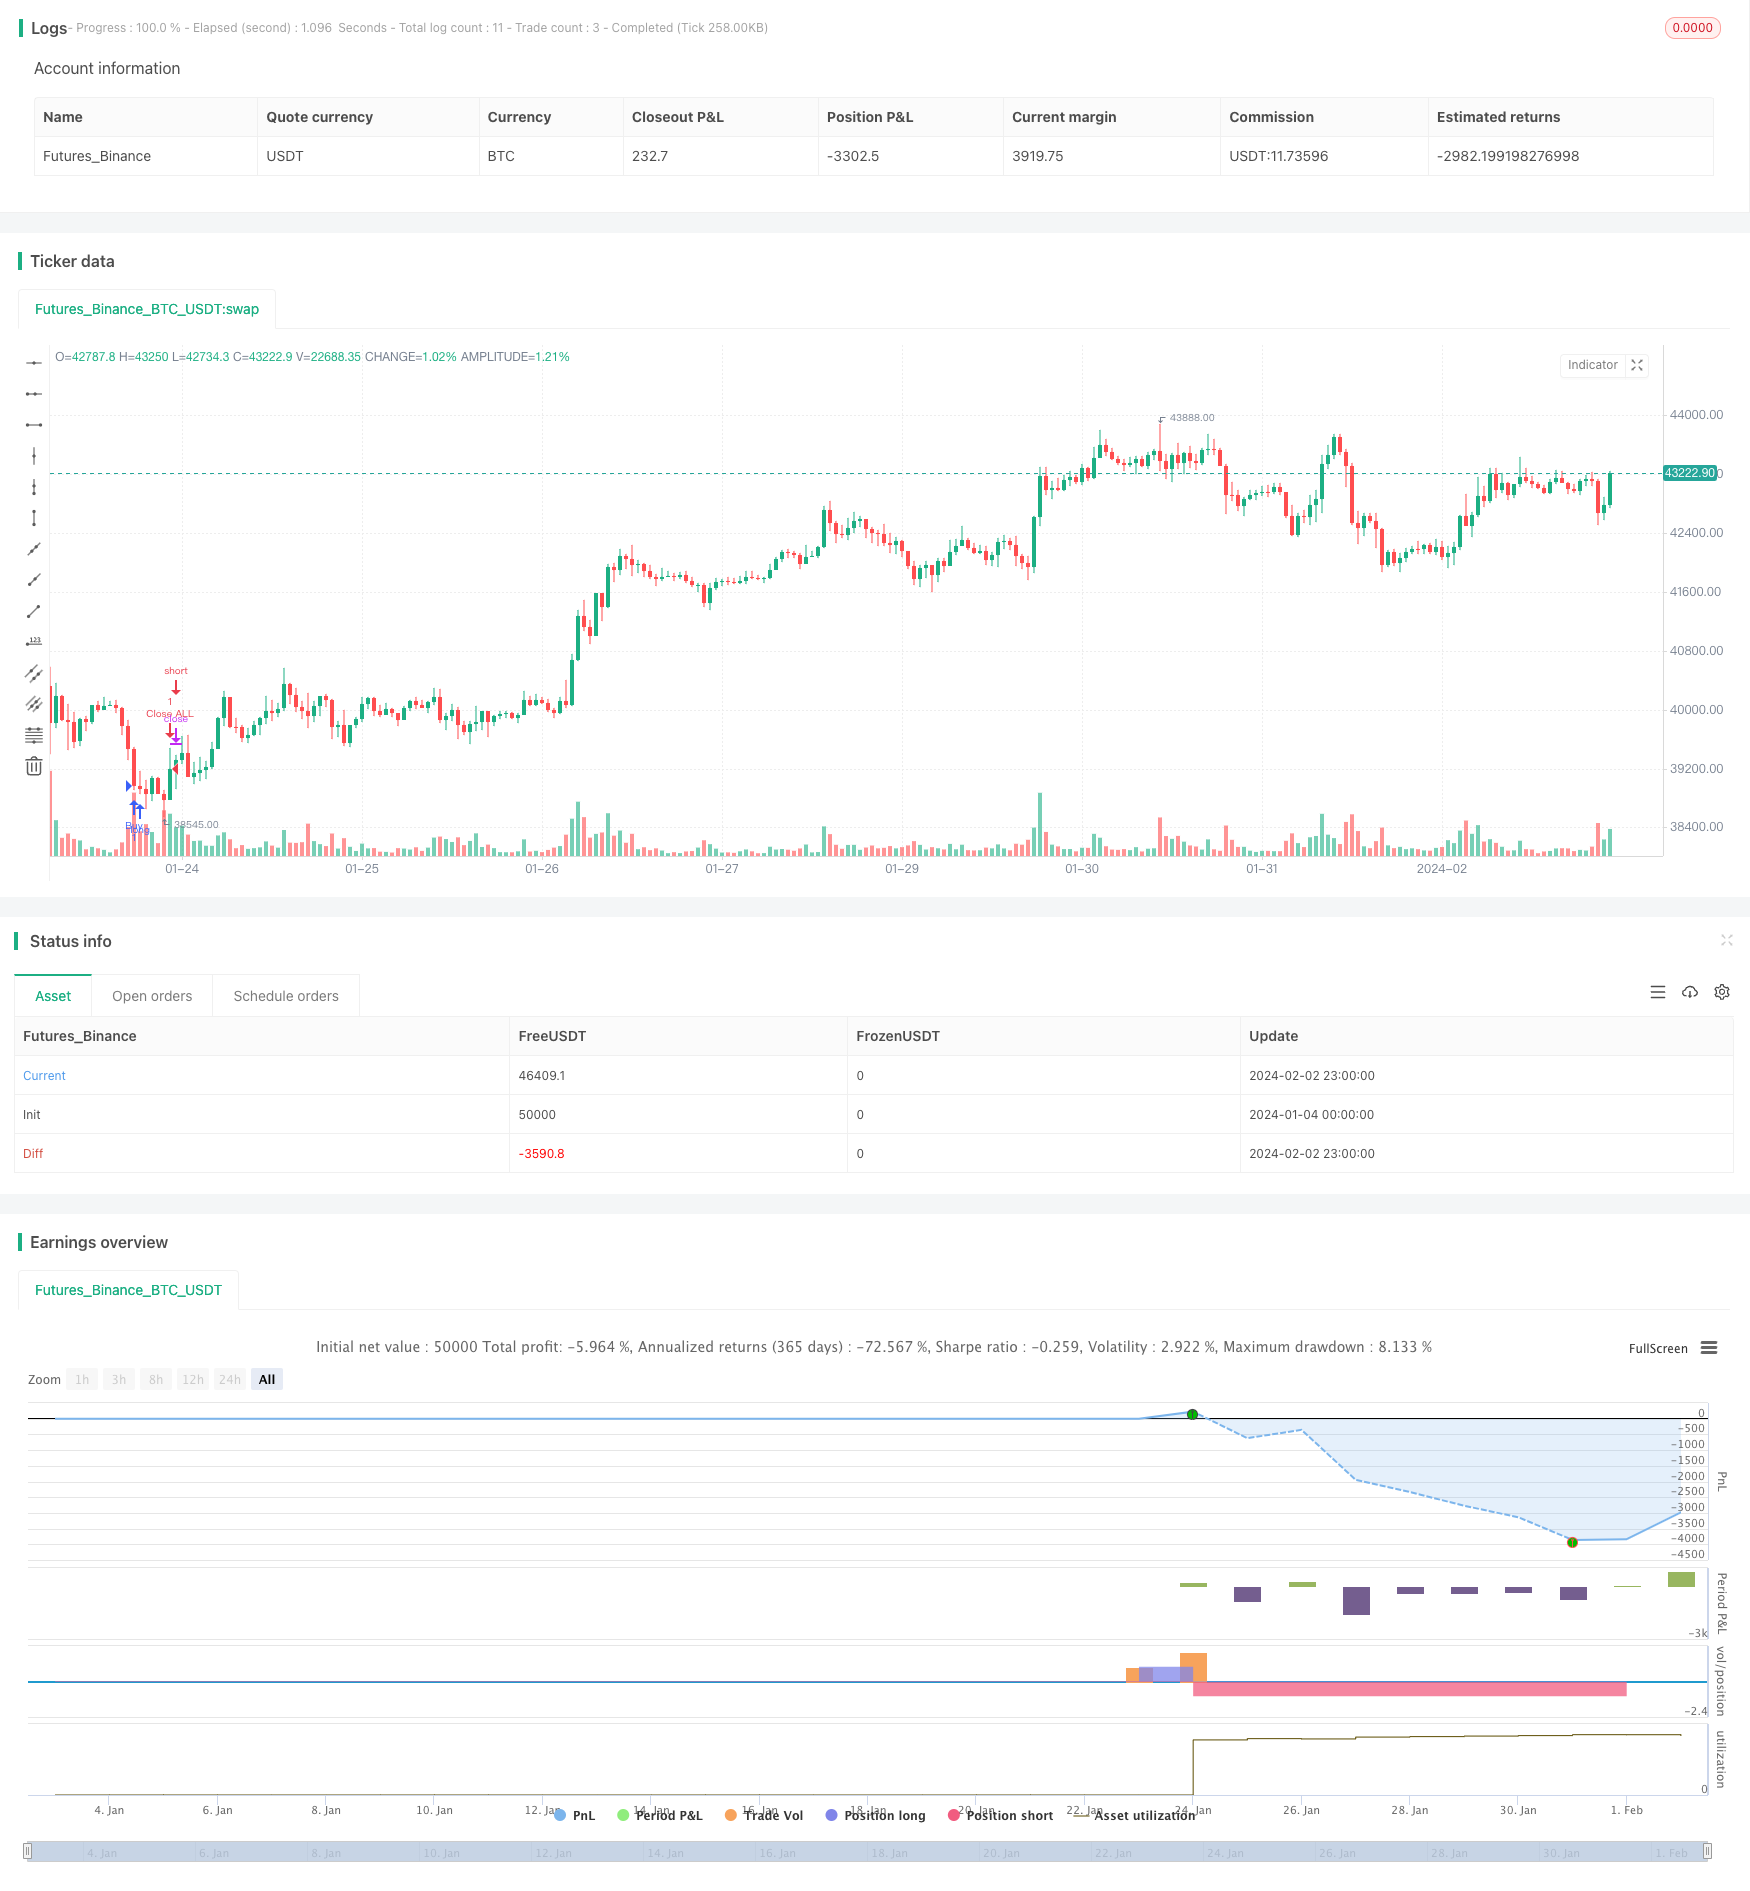
Overview
This strategy uses adaptive Bollinger Bands indicator to identify the trend direction and market orders to track the trend with stop loss for efficient trend trading.
Strategy Logic
- Calculate the middle, upper and lower bands of Bollinger based on a certain period
- Go long when the price breaks through the upper band and go short when breaks the lower band to track the trend
- Use market orders for fast entry
- Set stop loss and take profit for position management
Advantages
- Adaptive Bollinger Bands are sensitive to market volatility for fast judgement of trend reversal
- Market orders ensure fast entry with reduced slippage risk
- Automatic stop loss and take profit strictly control the risk and lock in profit
Risks
- Bollinger Bands has some lagging nature, cannot fully avoid false breakouts
- Market orders cannot control the execution price precisely
- Proper setting of stop loss and take profit levels is needed
Optimization Directions
- Adjust Bollinger parameters for better sensitivity in judging trends
- Add indicators like volume or MACD to filter false breakouts
- Optimize stop loss and take profit levels
Summary
This strategy makes full use of Bollinger Bands' advantage in judging trend directions and combines fast-exit market orders for trend tracking from both sides, gaining excess returns under controlled risk. Further improvements like optimizing Bollinger parameters, adding filtering indicators and adjusting stop loss/take profit logic can lead to better strategy performance. With clear logic and easy implementation, it is an efficient and reliable trend tracking trading strategy.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | false | Live |
| v_input_2 | 1600976975 | Start Timestamp |
| v_input_3 | 60 | Start Delay |
| v_input_4 | true | Leverage |
| v_input_5 | true | Take Profit % |
| v_input_6 | -1 | DCA when < % |
| v_input_7 | 0 | Entry Level: 1 | 2 | 3 | 4 | 5 | 6 | 7 | 8 | 9 | 10 |
| v_input_8 | 60 | Pivot Length |
Source Pine Script
/*backtest
start: 2024-01-04 00:00:00
end: 2024-02-03 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © CryptoRox

//@version=4
//Paste the line below in your alerts to run the built-in commands.
//{{strategy.order.alert_message}}
strategy("Automated - Fibs with Market orders", "Strategy", true)

//Settings
testing = input(false, "Live")
//Use epochconverter or something similar to get the current timestamp.
starttime = input(1600976975, "Start Timestamp") * 1000
//Wait XX seconds from that timestamp before the strategy starts looking for an entry.
seconds = input(60, "Start Delay") * 1000
testPeriod = true


leverage = input(1, "Leverage")
tp = input(1.0, "Take Profit %") / leverage
dca = input(-1.0, "DCA when < %") / leverage *-1
fibEntry = input("1", "Entry Level", options=["1", "2", "3", "4", "5", "6", "7", "8", "9", "10"])

//Strategy Calls
equity = strategy.equity
avg = strategy.position_avg_price
symbol = syminfo.tickerid
openTrades = strategy.opentrades
closedTrades = strategy.closedtrades
size = strategy.position_size

//Fibs
lentt = input(60, "Pivot Length")
h = highest(lentt)
h1 = dev(h, lentt) ? na : h
hpivot = fixnan(h1)
l = lowest(lentt)
l1 = dev(l, lentt) ? na : l
lpivot = fixnan(l1)
z = 400
p_offset= 2
transp = 60
a=(lowest(z)+highest(z))/2
b=lowest(z)
c=highest(z)

fib0 = (((hpivot - lpivot)) + lpivot)
fib1 = (((hpivot - lpivot)*.21) + lpivot)
fib2 = (((hpivot - lpivot)*.3) + lpivot)
fib3 = (((hpivot - lpivot)*.5) + lpivot)
fib4 = (((hpivot - lpivot)*.62) + lpivot)
fib5 = (((hpivot - lpivot)*.7) + lpivot)
fib6 = (((hpivot - lpivot)* 1.00) + lpivot)
fib7 = (((hpivot - lpivot)* 1.27) + lpivot)
fib8 = (((hpivot - lpivot)* 2) + lpivot)
fib9 = (((hpivot - lpivot)* -.27) + lpivot)
fib10 = (((hpivot - lpivot)* -1) + lpivot)

notna = nz(fib10[60])
entry = 0.0
if fibEntry == "1"
    entry := fib10
if fibEntry == "2"
    entry := fib9
if fibEntry == "3"
    entry := fib0
if fibEntry == "4"
    entry := fib1
if fibEntry == "5"
    entry := fib2
if fibEntry == "6"
    entry := fib3
if fibEntry == "7"
    entry := fib4
if fibEntry == "8"
    entry := fib5
if fibEntry == "9"
    entry := fib6
if fibEntry == "10"
    entry := fib7
profit = avg+avg*(tp/100)
pause = 0
pause := nz(pause[1])
paused = time < pause

fill = 0.0
fill := nz(fill[1])
count = 0.0
count := nz(fill[1])

filled = count > 0 ? entry > fill-fill/100*dca : 0
signal = testPeriod and notna and not paused and not filled ? 1 : 0

neworder = crossover(signal, signal[1])
moveorder = entry != entry[1] and signal and not neworder ? true : false
cancelorder = crossunder(signal, signal[1]) and not paused
filledorder = crossunder(low[1], entry[1]) and signal[1]

last_profit = 0.0
last_profit := nz(last_profit[1])

// if neworder and signal
//     strategy.order("New", 1, 0.0001, alert_message='New Order|e=binancefuturestestnet s=btcusdt b=long q=0.0011 fp=' + tostring(entry))
// if moveorder
//     strategy.order("Move", 1, 0.0001, alert_message='Move Order|e=binancefuturestestnet s=btcusdt b=long c=order|e=binancefuturestestnet s=btcusdt b=long q=0.0011 fp=' + tostring(entry))
if filledorder and size < 1
    fill := entry
    count := count+1
    pause := time + 60000
    p = close+close*(tp/100)
    strategy.entry("Buy", 1, 1,  alert_message='Long|e=binancefuturestestnet s=btcusdt b=long q=0.0011 t=market')
if filledorder and size >= 1
    fill := entry
    count := count+1
    pause := time + 60000
    strategy.entry("Buy", 1, 1,  alert_message='Long|e=binancefuturestestnet s=btcusdt b=long q=0.0011 t=market')

// if cancelorder and not filledorder
//     pause := time + 60000
//     strategy.order("Cancel", 1, 0.0001,  alert_message='Cancel Order|e=binancefuturestestnet s=btcusdt b=long c=order')

if filledorder
    last_profit := profit

closeit = crossover(high, profit) and size >= 1
if closeit
    strategy.entry("Close ALL", 0, 0, alert_message='Close Long|e=binancefuturestestnet s=btcusdt b=long c=position t=market')
    count := 0
    fill := 0.0
    last_profit := 0.0

//Plots
// bottom = signal ? color.green : filled ? color.red : color.white
// plot(entry, "Entry", bottom)Published by ChaoZhang on the FMZ strategy square · last modified 2024-02-04. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Adaptive-Bollinger-Bands-Trend-Tracking-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Incremental Order Size Fibonacci Retracement Trend Following StrategyPine Script · Trend following · 1d
- Going with the Trend Moving Average Crossover StrategyPine Script · Trend following · 1d
- Ichimoku Cloud Trend Following StrategyPine Script · Trend following · 1h
- MACD EMA Multi Period Dynamic Crossover Quantitative Trading SystemPine Script · Trend following · 1h
- Concise Dynamic Trend StrategyPine Script · Trend following · 2h
- Price Drop Buy Strategy in Downtrend with Stop LossPine Script · Trend following · 30m