Adaptive Dual Breakthrough Trading Strategy
The adaptive dual breakthrough trading strategy is a quantitative strategy that makes judgments and trading operations based on the relationship between the opening price and closing price of stocks. This strategy…
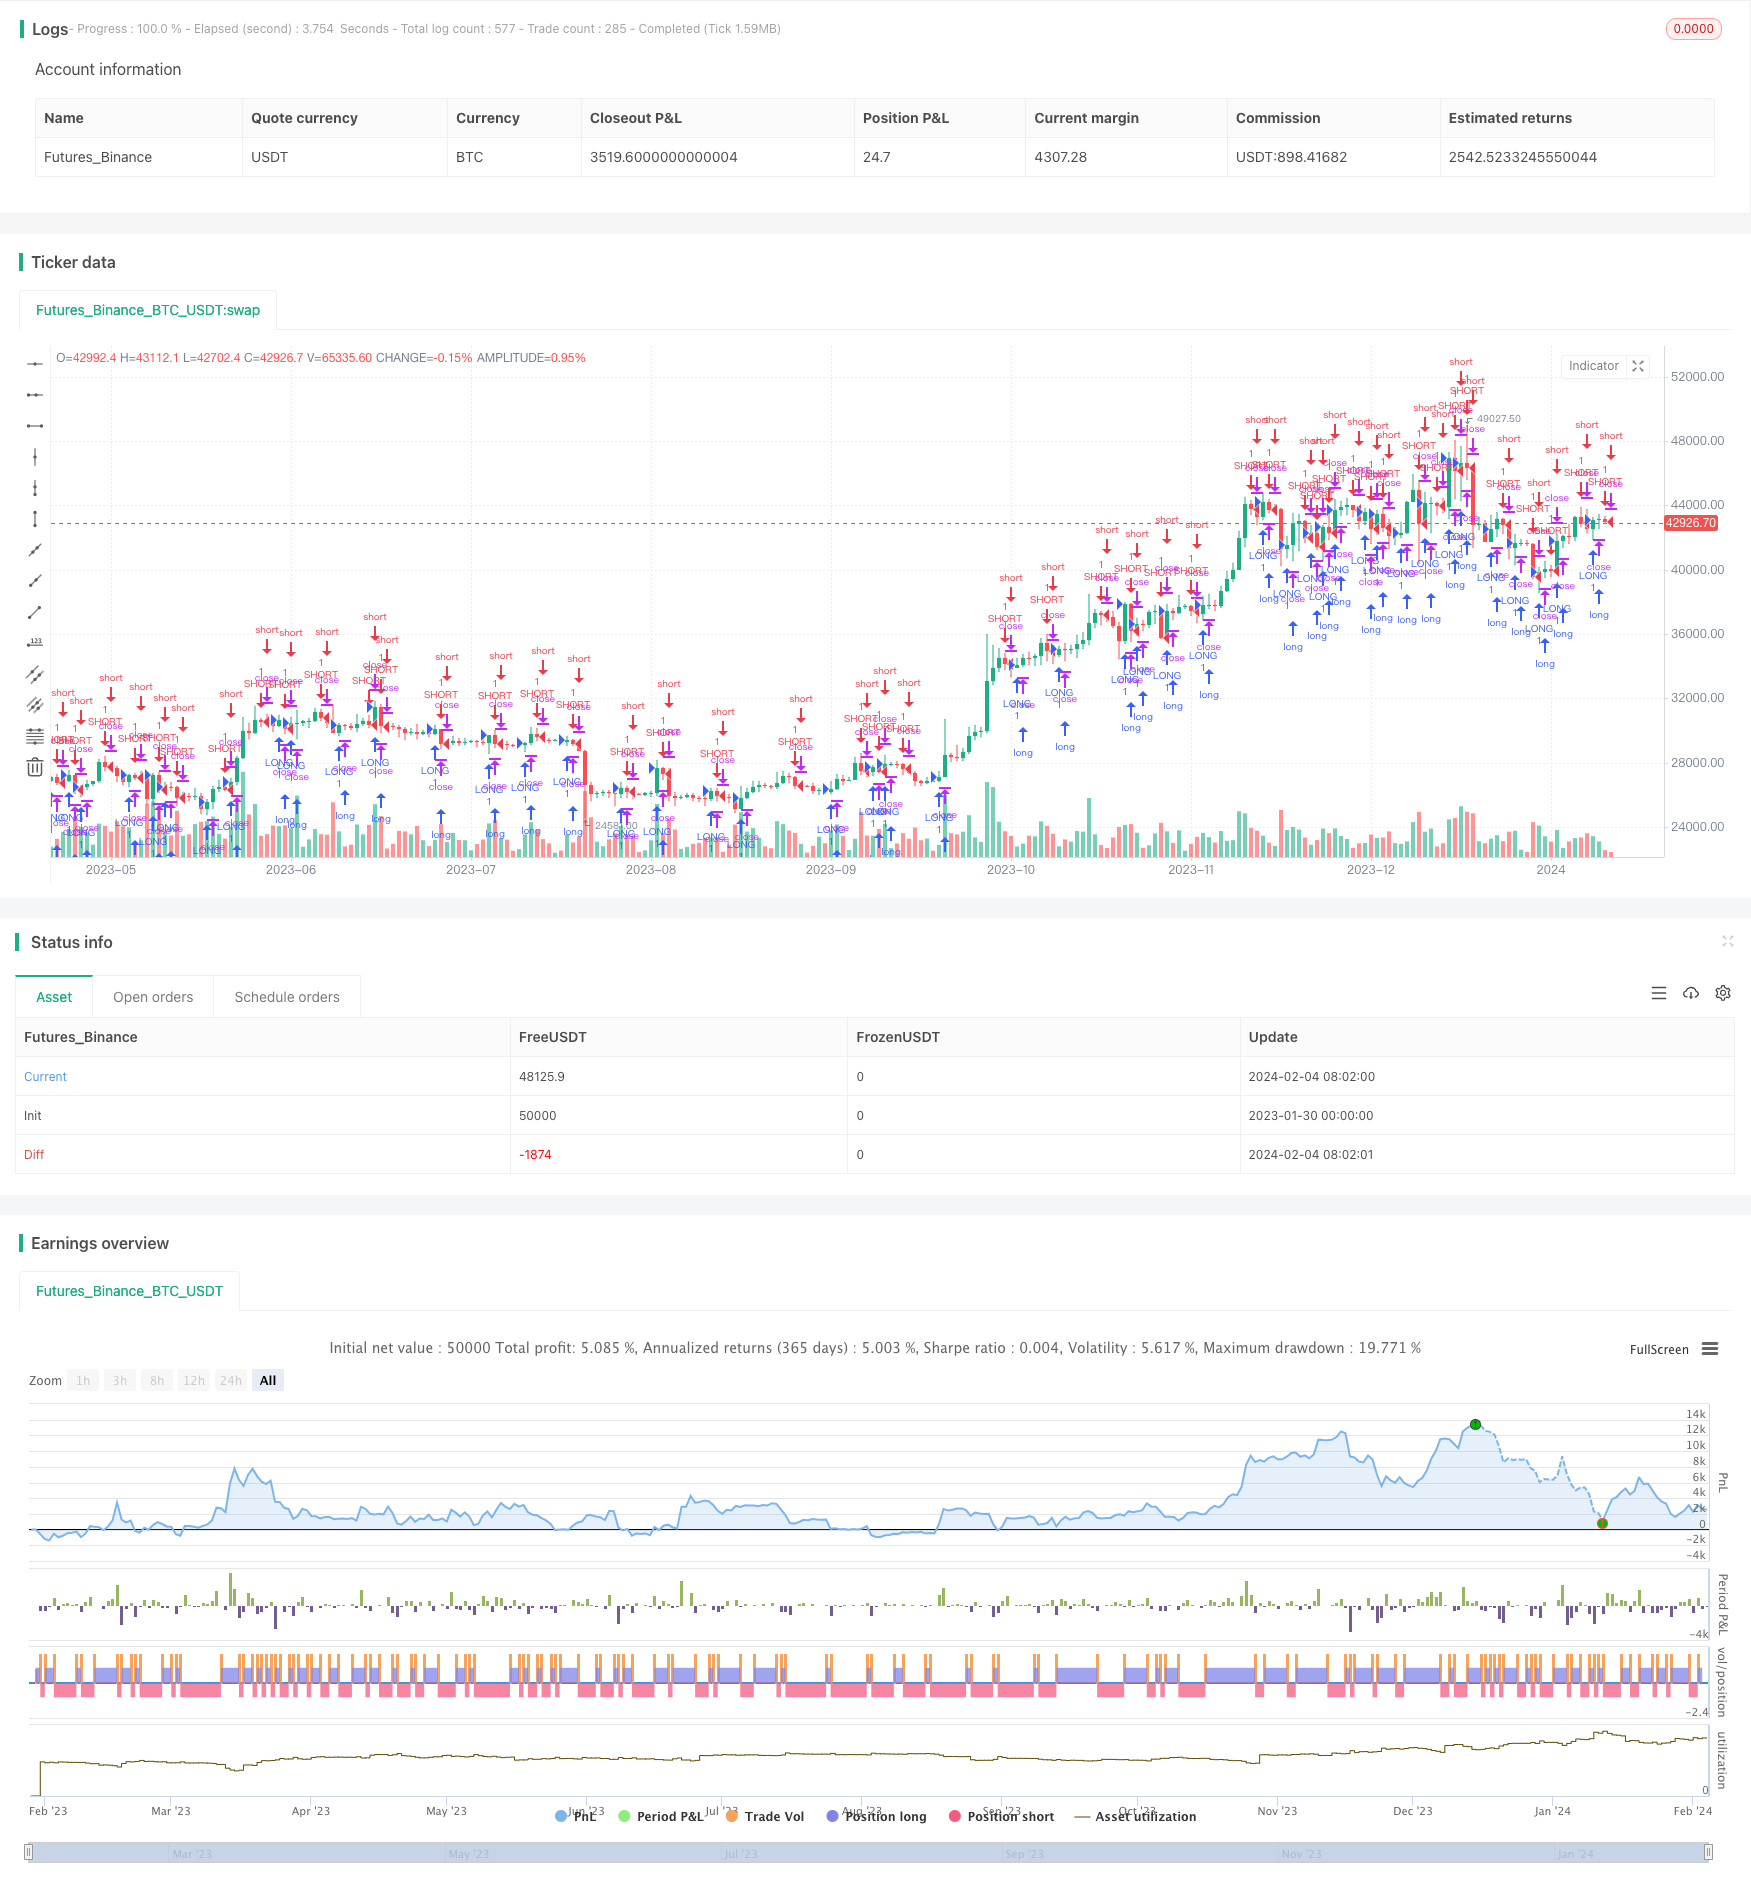
Overview
The adaptive dual breakthrough trading strategy is a quantitative strategy that makes judgments and trading operations based on the relationship between the opening price and closing price of stocks. This strategy will take long or short positions when the set parameter conditions are met. At the same time, it has an adaptive exit mechanism that can decide when to exit the current position based on recent changes in opening and closing prices.
Strategy Principle
The core logic of this strategy is to judge the direction based on the size relationship between opening price and closing price. Specifically, if the closing price is higher than the opening price exceeding the set threshold val1, a long signal is generated; if the opening price is higher than the closing price exceeding the threshold val1, a short signal is generated. Once a position is entered, the strategy will continue to monitor price changes. If the opening and closing prices reverse beyond the set threshold val2, the exit operation will be executed. It can be seen that this strategy includes both opening position logic and exit logic, forming a relatively complete trading framework.
In terms of code implementation, the strategy first defines the long and short position conditions, and places orders when the opening position logic is met. It then continuously detects whether the exit condition has been triggered, and once the exit condition is met, it executes the closing operation. So this strategy monitors market changes in real time and is adaptive and flexible.
Advantages of the Strategy
The adaptive dual breakthrough trading strategy has the following advantages:
- Clear and simple operation, easy to understand and implement
- Dynamically adjust positions to adapt to market changes
- Has stop loss function to control risks
- Can be applied to different varieties by adjusting parameters
- Easy to optimize algorithms with large expansion space
Risks of the Strategy
Although this strategy has certain advantages, it also has the following risks:
- Stop loss strategies may fail during violent market fluctuations
- Unable to catch long-term trends, frequent position switching
- Improper parameter settings can lead to over-trading
- System failures may result in inability to stop losses
These risks need to be closely monitored during live trading to promptly adjust parameters or optimize algorithms.
Optimization Directions
The main aspects for optimizing this strategy include:
- Enhance stop loss optimization to control frequent position switching while ensuring sensitivity.
- Add trend judgment indicators to reduce trading frequency in non-trend environments.
- Combine short-term intraday trading strategies to improve strategy returns.
- Optimize adaptive parameter mechanisms for dynamic threshold adjustment.
- Add machine learning models to judge trend directions.
Through algorithm and model optimization, the overall stability and profitability of the strategy can be improved.
Summary
The adaptive dual breakthrough trading strategy combines trend judgment and adaptive exit mechanisms, which can effectively control risks. Its simple principles and flexible parameters make it easy to understand and expand, making it a recommended and worthwhile quantitative strategy to study deeply.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 123 | val1 |
| v_input_2 | 234 | val2 |
| v_input_3 | 2018 | from_year |
| v_input_4 | 6 | from_month |
| v_input_5 | true | from_day |
| v_input_6 | 2019 | to_year |
| v_input_7 | 12 | to_month |
| v_input_8 | 31 | to_day |
Source Pine Script
/*backtest
start: 2023-01-30 00:00:00
end: 2024-02-05 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=3
strategy("Repaint in version 3", overlay=true, calc_on_every_tick=true, calc_on_order_fills=true) // Repaint?
// strategy("Repaint in version 3", overlay=true, calc_on_every_tick=true) // Correct

val1 = input(123)
val2 = input(234)

from_year=input(2018, minval=2000, maxval=2020)
from_month=input(6, minval=1, maxval=12)
from_day=input(1, minval=1, maxval=31)

to_year=input(2019, minval=2007, maxval=2020)
to_month=input(12, minval=1, maxval=12)
to_day=input(31, minval=1, maxval=31)

long = (close-open) > val1
short = (open-close) > val1

exitLong = (open-close) > val2
exitShort = (close-open) > val2

term = true

strategy.entry("LONG", strategy.long, when=long and term)
strategy.close("LONG",  when = exitLong and not short and term)

strategy.entry("SHORT", strategy.short, when=short and term)
strategy.close("SHORT", when = exitShort and not long and term)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-02-06. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Adaptive-Dual-Breakthrough-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- 5 Day Moving Average Channel Breakout Strategy Combined With Mileage ConceptPine Script · Breakout · 1d
- ATR Trailing Stops StrategyPine Script · Breakout · 1h
- ATR Trend Breakout StrategyPine Script · Breakout · 1d
- Adaptive Bollinger Breakout with Moving Average Quantitative Strategy SystemPine Script · Breakout · 1h
- Adaptive Channel Breakout StrategyPine Script · Breakout · 1d
- Adaptive Multi Period Trading Strategy Based on Wave Trend Momentum BreakoutPine Script · Breakout · 2h