Strategy vault / Mean reversion
Adaptive Dual Indicator Cross Smart Timing Trading Strategy
This is an adaptive trading strategy based on dual technical indicators RSI and CCI. The strategy monitors the cross-state of RSI and CCI indicators under different time periods, combined with EMA trend, to build a…
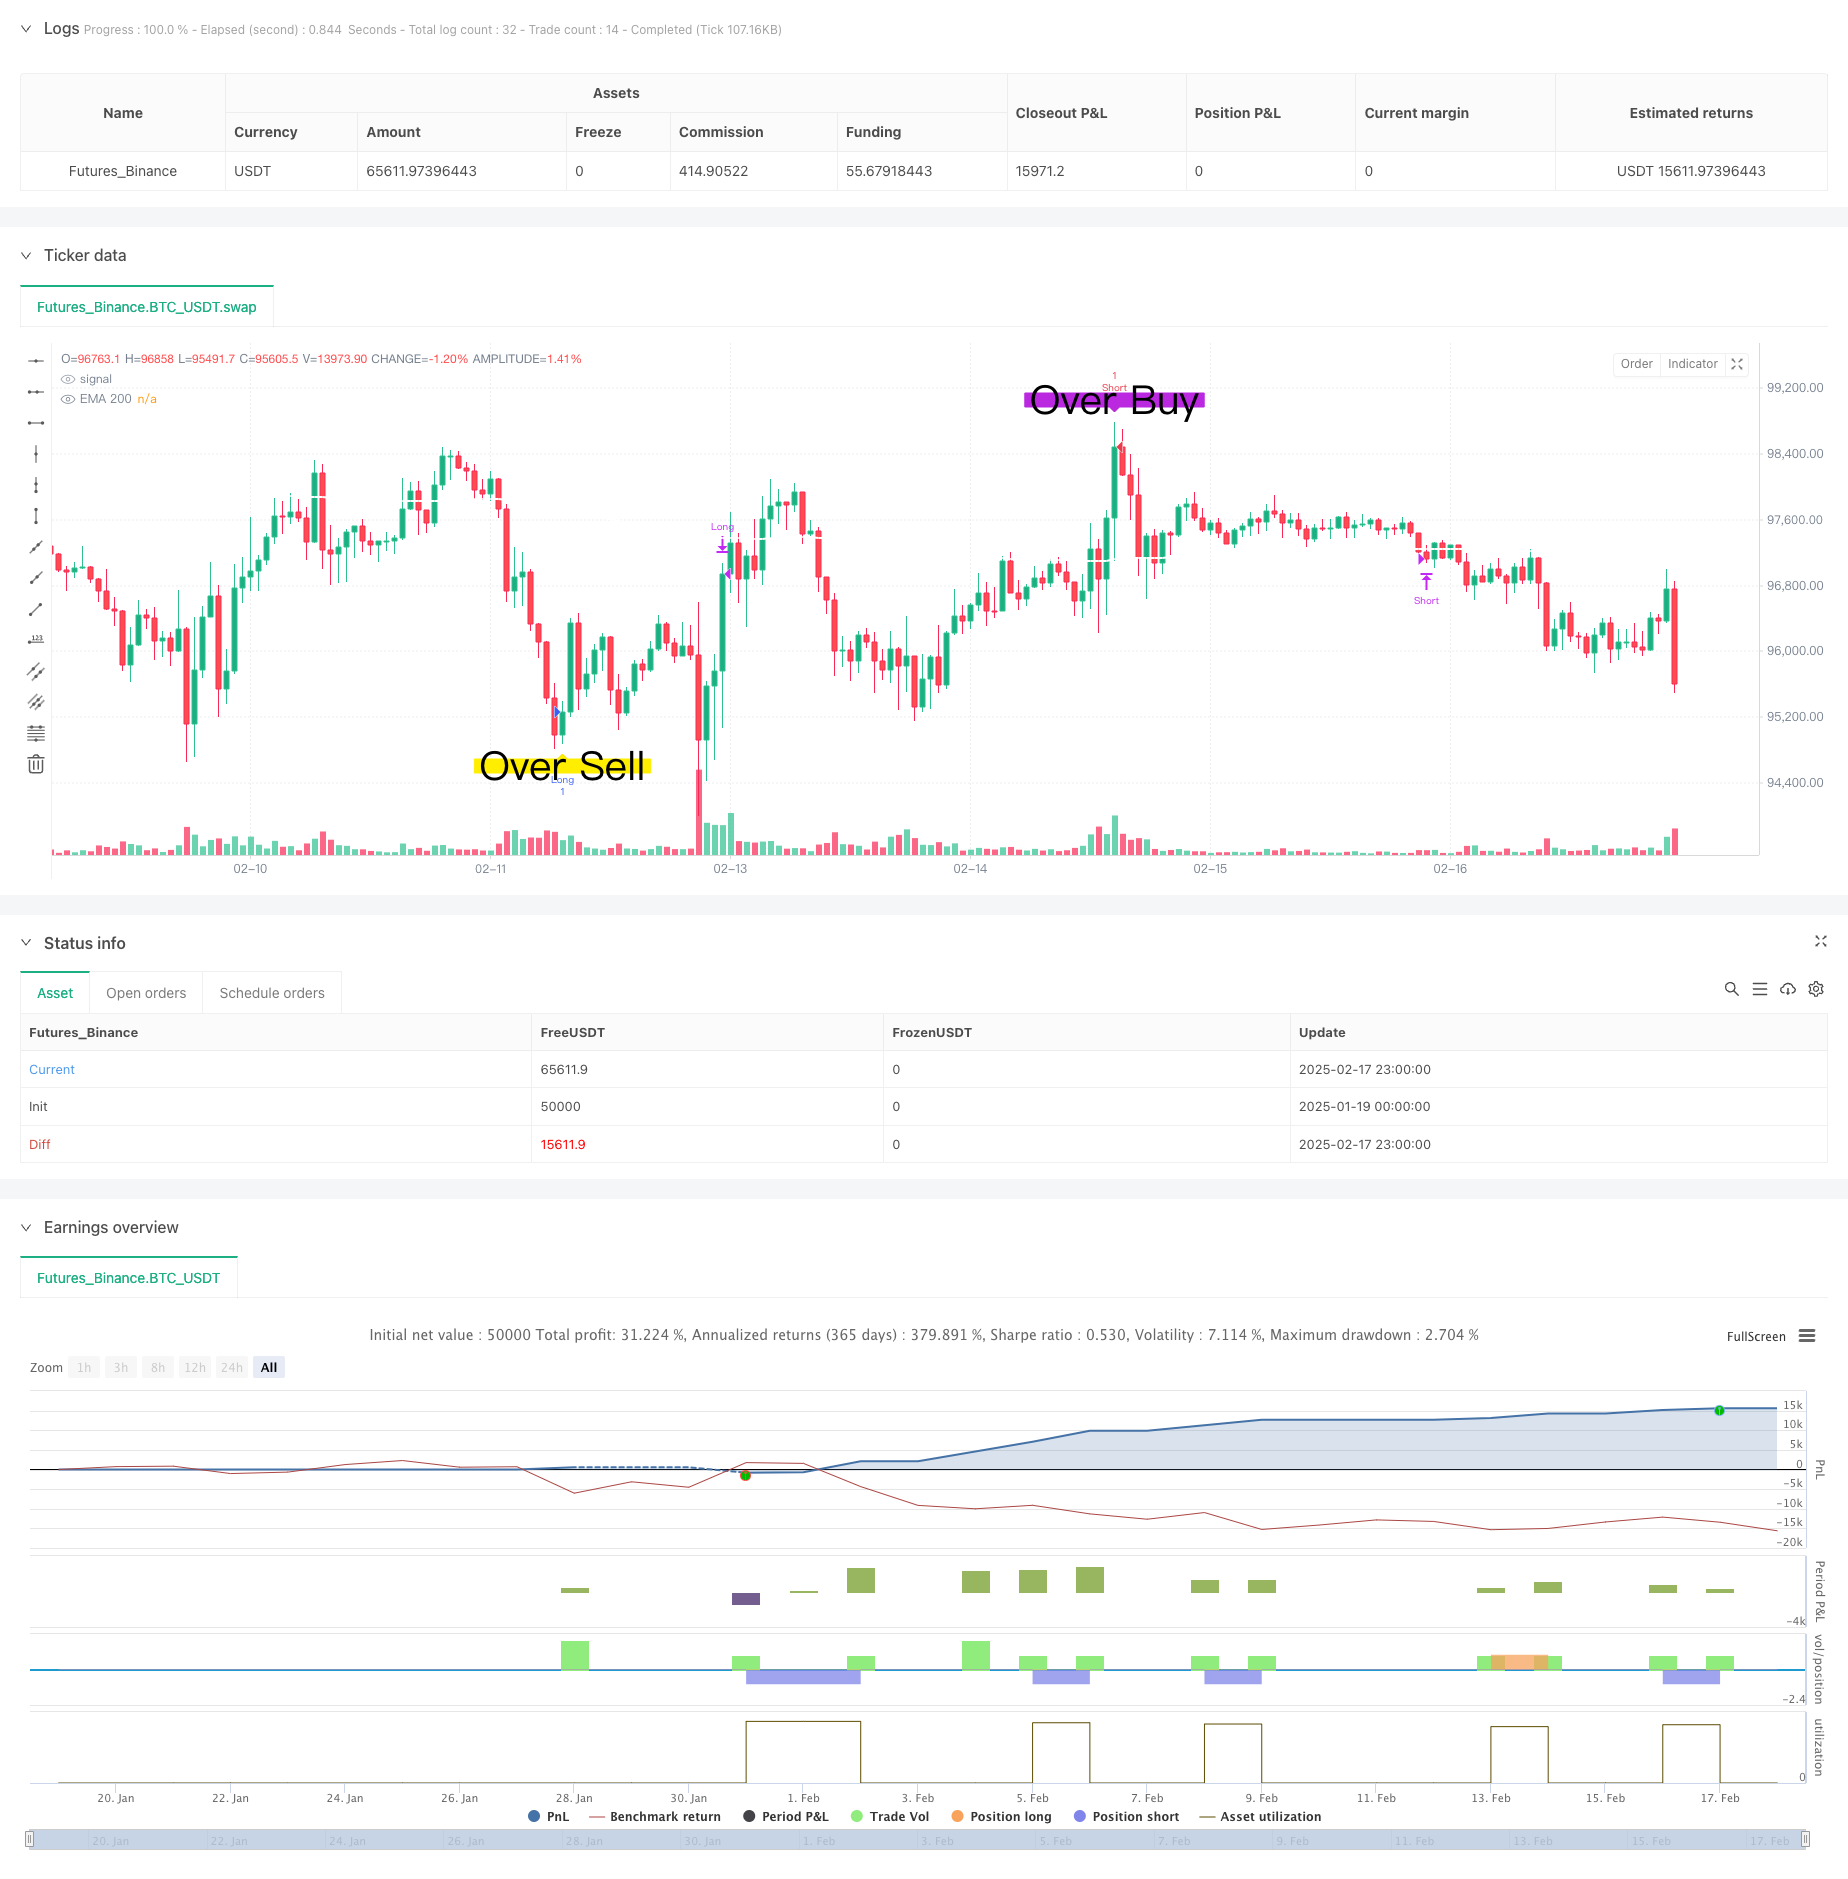
Overview
This is an adaptive trading strategy based on dual technical indicators RSI and CCI. The strategy monitors the cross-state of RSI and CCI indicators under different time periods, combined with EMA trend, to build a complete trading system. The strategy features strong adaptability and stable signals, effectively capturing market overbought and oversold opportunities.
Strategy Principle
The core logic includes:
- Time period adaptation: Dynamically adjusts RSI and CCI parameters based on different time periods (1 minute to 4 hours).
- Dual indicator confirmation: Uses combination of RSI (Relative Strength Index) and CCI (Commodity Channel Index) to filter trading signals. Trading signals are generated only when both RSI and CCI meet specific conditions.
- Signal persistence verification: Ensures signal stability through minimum duration settings (stayTimeFrames).
- Dynamic profit/loss limits: Sets dynamic take-profit and stop-loss levels based on entry RSI and CCI levels.
- Trend confirmation: Uses 200-period EMA as trend reference.
Strategy Advantages
- Strong adaptability: Strategy automatically adjusts parameters for different time periods.
- High signal reliability: Cross-confirmation through dual technical indicators significantly improves signal reliability.
- Comprehensive risk control: Dynamic profit/loss mechanism effectively controls risk.
- Clear operation rules: Entry and exit conditions are clear for practical operation.
- Good extensibility: Flexible strategy framework allows addition of new filtering conditions.
Strategy Risks
- Parameter sensitivity: Optimal parameters may vary in different market environments.
- Range-bound market risk: False signals may occur during market consolidation.
- Slippage impact: High-frequency trading may face slippage effects.
- Signal delay: Multiple confirmation mechanisms may cause slight delays in entry timing.
- Market environment dependence: May perform better in trending markets than ranging markets.
Strategy Optimization
- Parameter adaptation: Introduce adaptive parameter optimization mechanism for dynamic adjustment based on market conditions.
- Market environment recognition: Add market state identification module for different trading strategies in various market conditions.
- Volatility adaptation: Introduce volatility indicators to adjust profit/loss parameters based on volatility levels.
- Signal filtering: Add more technical indicators and pattern recognition to filter false signals.
- Risk management: Improve money management plan, enhance position time and size control.
Summary
The strategy builds a robust trading system by combining the advantages of RSI and CCI indicators. Its adaptive features and comprehensive risk control mechanisms provide good practicality. Through continuous optimization and improvement, the strategy shows promise for better performance in actual trading. Traders are advised to conduct thorough backtesting and parameter optimization before live implementation.
Source Pine Script
/*backtest
start: 2025-01-19 00:00:00
end: 2025-02-18 00:00:00
period: 1h
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=6
strategy("RSI & CCI Strategy with Alerts", overlay=true)

// Detect current chart timeframe
tf = timeframe.period

// Define settings for different timeframes
rsiLength = tf == "1" ? 30 : tf == "5" ? 30 : tf == "15" ? 30 : tf == "30" ? 30 : 30  // Default
cciLength = tf == "1" ? 15 : tf == "5" ? 20 : tf == "15" ? 20 : tf == "30" ? 20 : 20  // Default
cciBuyThreshold = tf == "1" ? -100 : tf == "5" ? -100 : tf == "15" ? -100 : tf == "30" ? -100 : -100
cciSellThreshold = tf == "1" ? 100 : tf == "5" ? 100 : tf == "15" ? 100 : tf == "30" ? 100 : 100  // Default
stayTimeFrames = tf == "1" ? 1 : tf == "5" ? 1 : tf == "15" ? 1 : tf == "30" ? 1 : tf == "240" ? 1 : 2  // Default
stayTimeFramesOver =tf == "1" ? 1 : tf == "5" ? 2 : tf == "15" ? 2 : tf == "30" ? 3 : 2 // Default

// Calculate RSI & CCI
rsi = ta.rsi(close, rsiLength)
rsiOver = ta.rsi(close, 14)
cci = ta.cci(close, cciLength)

// EMA 50
ema200 = ta.ema(close, 200)
plot(ema200, color=color.rgb(255, 255, 255), linewidth=2, title="EMA 200")

// CCI candle threshold tracking
var int cciEntryTimeLong = na
var int cciEntryTimeShort = na

// Store entry time when CCI enters the zone
if (cci < cciBuyThreshold)
    if na(cciEntryTimeLong)
        cciEntryTimeLong := bar_index
else
    cciEntryTimeLong := na

if (cci > cciSellThreshold)
    if na(cciEntryTimeShort)
        cciEntryTimeShort := bar_index
else
    cciEntryTimeShort := na

// Confirming CCI has stayed in the threshold for required bars
cciStayedBelowNeg100 = not na(cciEntryTimeLong) and (bar_index - cciEntryTimeLong >= stayTimeFrames) and rsi >= 53
cciStayedAbove100 = not na(cciEntryTimeShort) and (bar_index - cciEntryTimeShort >= stayTimeFrames) and rsi <= 47


// CCI & RSI candle threshold tracking for Buy Over and Sell Over signals
var int buyOverEntryTime = na
var int sellOverEntryTime = na

// Track entry time when RSI and CCI conditions are met
if (rsiOver <= 31 and cci <= -120)
    if na(buyOverEntryTime)
        buyOverEntryTime := bar_index
else
    buyOverEntryTime := na

if (rsiOver >= 69 and cci >= 120)
    if na(sellOverEntryTime)
        sellOverEntryTime := bar_index
else
    sellOverEntryTime := na

// Confirm that conditions are met for the required stayTimeFrames
buyOverCondition = not na(buyOverEntryTime) and (bar_index - buyOverEntryTime >= stayTimeFramesOver)
sellOverCondition = not na(sellOverEntryTime) and (bar_index - sellOverEntryTime <= stayTimeFramesOver)

//Buy and sell for over bought or sell
conditionOverBuy = buyOverCondition
conditionOverSell = sellOverCondition

// Buy and sell conditions
buyCondition = cciStayedBelowNeg100
sellCondition = cciStayedAbove100

// // Track open positions
var bool isLongOpen = false
var bool isShortOpen = false

// // Strategy logic for backtesting
// if (buyCondition and not isLongOpen)
//     strategy.entry("Long", strategy.long)
//     isLongOpen := true
//     isShortOpen := false

// if (sellCondition and not isShortOpen)
//     strategy.entry("Short", strategy.short)
//     isShortOpen := true
//     isLongOpen := false

// // Close positions based on EMA 50
// if (isLongOpen and exitLongCondition)
//     strategy.close("Long")
//     isLongOpen := false

// if (isShortOpen and exitShortCondition)
//     strategy.close("Short")
//     isShortOpen := false


// Track RSI at position entry
var float entryRSILong = na
var float entryRSIShort = na

// Track CCI at position entry
var float entryCCILong = na
var float entryCCIShort = na

if (buyOverCondition and not isLongOpen)
    strategy.entry("Long", strategy.long)
    entryRSILong := rsi  // Store RSI at entry
    entryCCILong := cci
    isLongOpen := true
    isShortOpen := false

if (sellOverCondition and not isShortOpen)
    strategy.entry("Short", strategy.short)
    entryRSIShort := rsi  // Store RSI at entry
    entryCCIShort := cci  // Stpre CCI at entry
    isShortOpen := true
    isLongOpen := false

exitLongRSICondition = isLongOpen and not na(entryRSILong) and rsi >= (entryRSILong + 12)  or rsi <= (entryRSILong -8)
exitShortRSICondition = isShortOpen and not na(entryRSIShort) and rsi <= (entryRSIShort - 12)  or rsi >= (entryRSIShort +8)

exitLongCCICondition = isLongOpen and not na(entryCCILong) and cci <= (entryCCILong -100)
exitShortCCICondition = isShortOpen and not na(entryCCIShort) and cci >= (entryCCIShort +100)

// Close positions based on EMA 50 or RSI change
if (isLongOpen and (exitLongRSICondition) or (exitLongCCICondition))
    strategy.close("Long")
    isLongOpen := false
    entryRSILong := na
    entryCCILong := na
    isLongOpen := false

if (isShortOpen and (exitShortRSICondition) or (exitShortCCICondition))
    strategy.close("Short")
    isShortOpen := false
    entryRSIShort := na
    entryCCIShort := na
    isShortOpen := false


// Plot buy and sell signals
plotshape(buyCondition, style=shape.labelup, location=location.belowbar, color=color.green, size=size.large, title="Buy Signal", text="BUY")
plotshape(sellCondition, style=shape.labeldown, location=location.abovebar, color=color.red, size=size.large, title="Sell Signal", text="SELL")

//Plot buy and sell OverBought
plotshape(conditionOverBuy, style=shape.labelup, location=location.belowbar, color=color.rgb(255, 238, 0), size=size.large, title="OverBuy Signal", text="Over Sell")
plotshape(conditionOverSell, style=shape.labeldown, location=location.abovebar, color=color.rgb(186, 40, 223), size=size.large, title="OverSell Signal", text="Over Buy")

// Alerts
alertcondition(buyCondition, title="Buy Alert", message="Buy Signal Triggered")
alertcondition(sellCondition, title="Sell Alert", message="Sell Signal Triggered")
Published by ChaoZhang on the FMZ strategy square · last modified 2025-02-19. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Adaptive-Dual-Indicator-Cross-Smart-Timing-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Four Indicator Momentum Reversal StrategyPine Script · Mean reversion · 45m
- MACD RSI and EMA StrategyPine Script · Mean reversion · 1d
- RSI amp CCI Combination Quantitative Trading StrategyPine Script · Mean reversion · 1h
- Rainbow OscillatorPine Script · Mean reversion · 1h
- EMA Assisted Extreme Point Reversal Trading StrategyPine Script · Mean reversion · 3d
- A Momentum Tracking Mean Reversion StrategyPine Script · Mean reversion · 1h