Adaptive Intelligent Grid Trading Strategy
This strategy is an adaptive intelligent grid trading strategy based on the TradingView platform, written in Pine Script v4. It overlays on the price chart and creates a grid within specified bounds to generate buy…
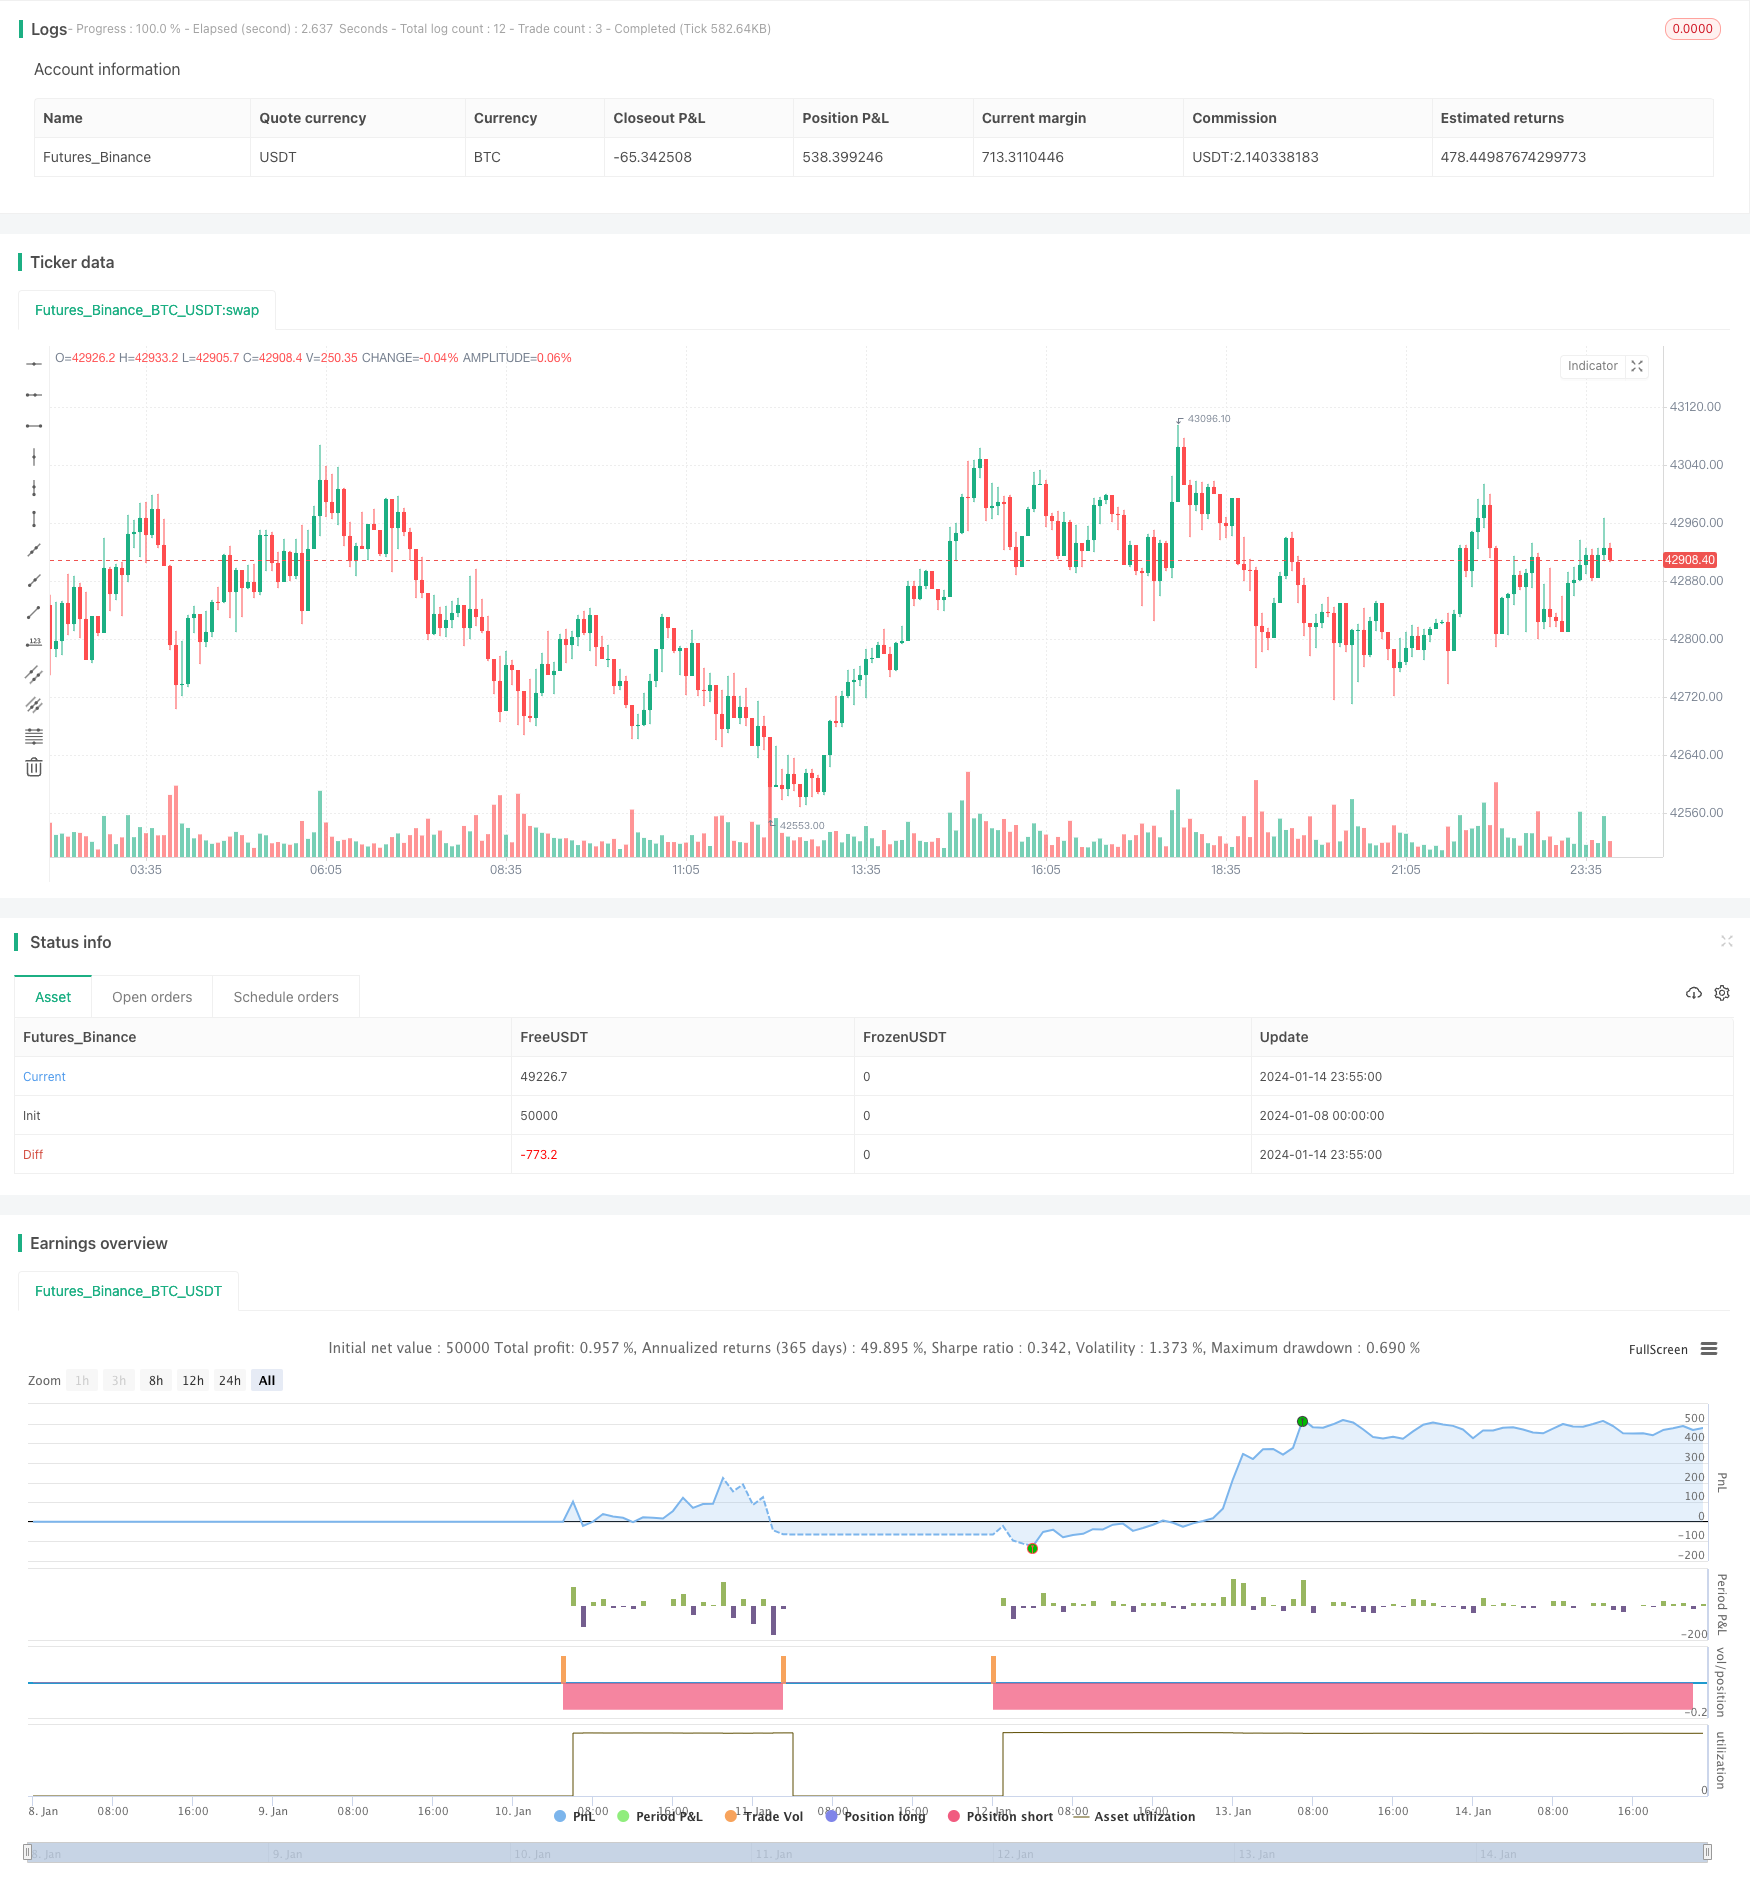
Overview
This strategy is an adaptive intelligent grid trading strategy based on the TradingView platform, written in Pine Script v4. It overlays on the price chart and creates a grid within specified bounds to generate buy and sell signals.
Strategy Logic
Key Features
Pyramiding and Money Management:
- Allows up to 14 additions in the same direction (pyramiding),
- Uses a cash-based strategy to manage position sizes,
- Initial capital is set at 100 USD for simulation purposes,
- A small commission of 0.1% is charged for each trade.
Grid Bounds:
- Users can opt to use auto-calculated bounds or manually set the upper and lower boundaries of the grid,
- Auto bounds can be derived from either the recent High & Low of the price or from a Simple Moving Average (SMA),
- Users can define the lookback period for the bounds calculation and adjust the deviation to widen or narrow the bounds.
Grid Lines:
- The strategy allows for a customizable number of grid lines within the bounds, with a recommended range between 3 and 15,
- The grid lines are evenly spaced between the upper and lower bounds.
Strategy Logic
Entry:
- The script places buy orders when the price falls below a grid line and no existing order is associated with that grid line.
- Each buy order quantity is calculated based on the initial capital divided by the number of grid lines, adjusted for the current price.
Exit:
- Sell orders are triggered when the price rises above a grid line, provided there is an open order corresponding to the next lower grid line.
Adaptive Grid:
- If set to auto bounds, the grid adapts to changing market conditions by recalculating the upper and lower bounds and adjusting the grid accordingly.
Advantage Analysis
The strategy integrates the systematic nature and efficient execution of grid trading. Allowing pyramiding and using money management can effectively control risks. The auto-adapting grid fits different market conditions. The adjustable parameters cater to different trading styles.
Risk Analysis
A price breakout beyond the grid bounds may cause severe losses. Parameters should be adjusted properly or combined with a stop loss to control risks. Also, excessive trading increases transaction costs.
Optimization Directions
Consider combining with a trend filter or optimizing grid parameters. A stop loss may also help prevent risks from extreme market moves.
Conclusion
This strategy systematically generates entries and exits while managing positions. Through parameter tuning it adapts to different preferences. It combines the rules-based nature of grid trading with the flexibility of trend trading, easing operation complexity while retaining robustness.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | true | (?Grid Bounds)Use Auto Bounds? |
| v_input_2 | 0 | (Auto) Bound Source: Hi & Low | Average |
| v_input_3 | 250 | (Auto) Bound Lookback |
| v_input_4 | 0.1 | (Auto) Bound Deviation |
| v_input_5 | 0.285 | (Manual) Upper Boundry |
| v_input_6 | 0.225 | (Manual) Lower Boundry |
| v_input_7 | 8 | (?Grid Lines)Grid Line Quantity |
Source Pine Script
/*backtest
start: 2024-01-08 00:00:00
end: 2024-01-15 00:00:00
period: 5m
basePeriod: 1m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4
strategy("(IK) Grid Script", overlay=true, pyramiding=14, close_entries_rule="ANY", default_qty_type=strategy.cash, initial_capital=100.0, currency="USD", commission_type=strategy.commission.percent, commission_value=0.1)
i_autoBounds    = input(group="Grid Bounds", title="Use Auto Bounds?", defval=true, type=input.bool)                             // calculate upper and lower bound of the grid automatically? This will theorhetically be less profitable, but will certainly require less attention
i_boundSrc      = input(group="Grid Bounds", title="(Auto) Bound Source", defval="Hi & Low", options=["Hi & Low", "Average"])     // should bounds of the auto grid be calculated from recent High & Low, or from a Simple Moving Average
i_boundLookback = input(group="Grid Bounds", title="(Auto) Bound Lookback", defval=250, type=input.integer, maxval=500, minval=0) // when calculating auto grid bounds, how far back should we look for a High & Low, or what should the length be of our sma
i_boundDev      = input(group="Grid Bounds", title="(Auto) Bound Deviation", defval=0.10, type=input.float, maxval=1, minval=-1)  // if sourcing auto bounds from High & Low, this percentage will (positive) widen or (negative) narrow the bound limits. If sourcing from Average, this is the deviation (up and down) from the sma, and CANNOT be negative.
i_upperBound    = input(group="Grid Bounds", title="(Manual) Upper Boundry", defval=0.285, type=input.float)                      // for manual grid bounds only. The upperbound price of your grid
i_lowerBound    = input(group="Grid Bounds", title="(Manual) Lower Boundry", defval=0.225, type=input.float)                      // for manual grid bounds only. The lowerbound price of your grid.
i_gridQty       = input(group="Grid Lines",  title="Grid Line Quantity", defval=8, maxval=15, minval=3, type=input.integer)       // how many grid lines are in your grid

f_getGridBounds(_bs, _bl, _bd, _up) =>
    if _bs == "Hi & Low"
        _up ? highest(close, _bl) * (1 + _bd) : lowest(close, _bl)  * (1 - _bd)
    else
        avg = sma(close, _bl)
        _up ? avg * (1 + _bd) : avg * (1 - _bd)

f_buildGrid(_lb, _gw, _gq) =>
    gridArr = array.new_float(0)
    for i=0 to _gq-1
        array.push(gridArr, _lb+(_gw*i))
    gridArr

f_getNearGridLines(_gridArr, _price) =>
    arr = array.new_int(3)
    for i = 0 to array.size(_gridArr)-1
        if array.get(_gridArr, i) > _price
            array.set(arr, 0, i == array.size(_gridArr)-1 ? i : i+1)
            array.set(arr, 1, i == 0 ? i : i-1)
            break
    arr

var upperBound      = i_autoBounds ? f_getGridBounds(i_boundSrc, i_boundLookback, i_boundDev, true) : i_upperBound  // upperbound of our grid
var lowerBound      = i_autoBounds ? f_getGridBounds(i_boundSrc, i_boundLookback, i_boundDev, false) : i_lowerBound // lowerbound of our grid
var gridWidth       = (upperBound - lowerBound)/(i_gridQty-1)                                                       // space between lines in our grid
var gridLineArr     = f_buildGrid(lowerBound, gridWidth, i_gridQty)                                                 // an array of prices that correspond to our grid lines
var orderArr        = array.new_bool(i_gridQty, false)                                                              // a boolean array that indicates if there is an open order corresponding to each grid line

var closeLineArr    = f_getNearGridLines(gridLineArr, close)                                                        // for plotting purposes - an array of 2 indices that correspond to grid lines near price
var nearTopGridLine = array.get(closeLineArr, 0)                                                                    // for plotting purposes - the index (in our grid line array) of the closest grid line above current price
var nearBotGridLine = array.get(closeLineArr, 1)                                                                    // for plotting purposes - the index (in our grid line array) of the closest grid line below current price
strategy.initial_capital = 50000
for i = 0 to (array.size(gridLineArr) - 1)
    if close < array.get(gridLineArr, i) and not array.get(orderArr, i) and i < (array.size(gridLineArr) - 1)
        buyId = i
        array.set(orderArr, buyId, true)
        strategy.entry(id=tostring(buyId), long=true, qty=(strategy.initial_capital/(i_gridQty-1))/close, comment="#"+tostring(buyId))
    if close > array.get(gridLineArr, i) and i != 0
        if array.get(orderArr, i-1)
            sellId = i-1
            array.set(orderArr, sellId, false)
            strategy.close(id=tostring(sellId), comment="#"+tostring(sellId))

if i_autoBounds
    upperBound  := f_getGridBounds(i_boundSrc, i_boundLookback, i_boundDev, true)
    lowerBound  := f_getGridBounds(i_boundSrc, i_boundLookback, i_boundDev, false)
    gridWidth   := (upperBound - lowerBound)/(i_gridQty-1)
    gridLineArr := f_buildGrid(lowerBound, gridWidth, i_gridQty)

closeLineArr    := f_getNearGridLines(gridLineArr, close)
nearTopGridLine := array.get(closeLineArr, 0)
nearBotGridLine := array.get(closeLineArr, 1)Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-16. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a grid bot with inventory caps and order deduplication from strategies/Adaptive-Intelligent-Grid-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Adaptive Bollinger Bands Grid Trading Strategy with Dynamic Level AdjustmentPine Script · Grid · 1d
- Adaptive Grid Trading Strategy Based on Quantitative Trading PlatformPine Script · Grid · 1h
- Assassins Grid B A Dynamic Grid Trading StrategyPine Script · Grid · 1d
- Bollinger Fibonacci Grid Tracking Trend StrategyPine Script · Grid · 1h
- Grid Trading Risk Hedging StrategyPine Script · Grid · 5m
- Multi Zone MA100 Price Retracement Smart Grid Trading StrategyPine Script · Grid · 1d