Strategy vault / Mean reversion
Adaptive Momentum Mean Reversion Crossover Strategy
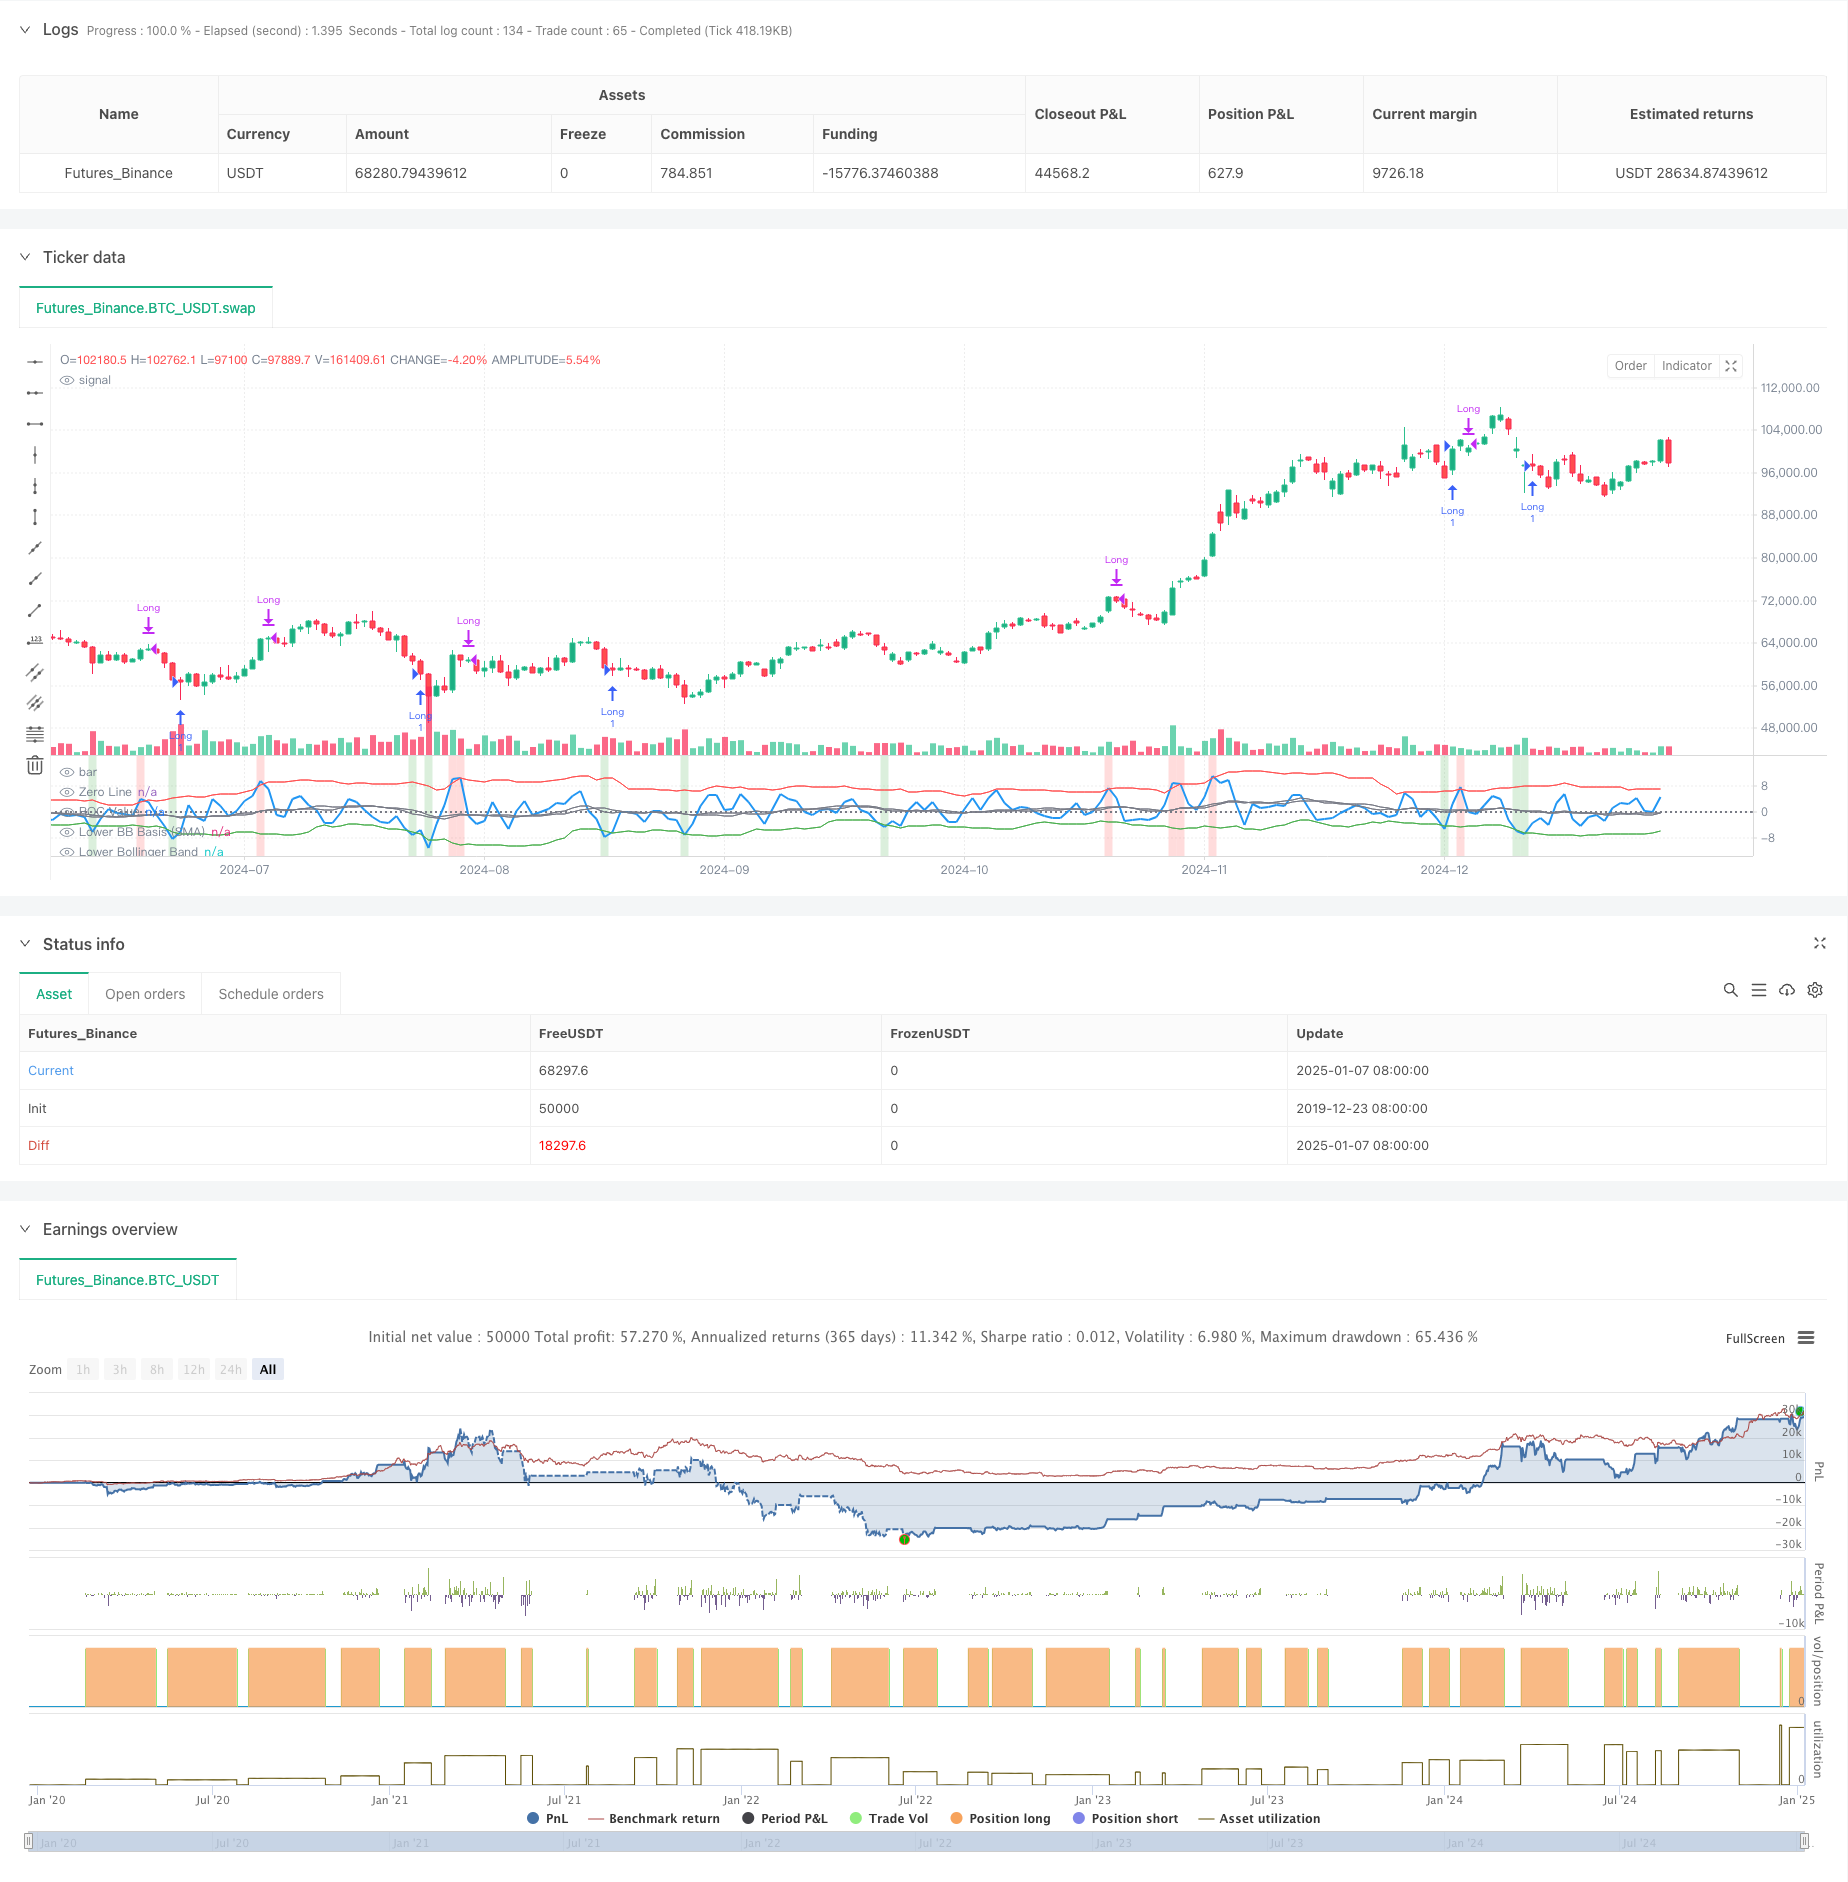
This strategy is a hybrid trading system that combines momentum and mean reversion theories. It identifies market overbought and oversold conditions using the Rate of Change (ROC) indicator and Bollinger Bands…
Overview
This strategy is a hybrid trading system that combines momentum and mean reversion theories. It identifies market overbought and oversold conditions using the Rate of Change (ROC) indicator and Bollinger Bands, triggering trades when specific thresholds are crossed. The core concept is to detect momentum shifts and capitalize on price reversions to their mean.
Strategy Principles
The strategy employs a 2-period ROC indicator to calculate short-term price changes, along with two sets of Bollinger Bands: short-term (18-period, 1.7 standard deviations) for oversold conditions and entry signals, and long-term (21-period, 2.1 standard deviations) for overbought conditions and exit signals. Long positions are initiated when ROC crosses above the lower Bollinger Band, indicating a shift from weak to strong momentum, and positions are closed when ROC crosses below the upper Bollinger Band, signaling weakening momentum. The strategy also uses background colors to highlight overbought (red) and oversold (green) zones.
Strategy Advantages
- High Adaptability: Bollinger Bands automatically adjust their width based on market volatility, maintaining effectiveness across different market conditions
- Robust Risk Control: Pyramiding is disabled (pyramiding=0), ensuring only one position at a time
- Reliable Signals: Combination of momentum and mean reversion strategies provides better market turning point identification
- Practicality: Includes transaction costs and slippage considerations for real-world trading conditions
Strategy Risks
- Choppy Market Risk: May generate frequent trades leading to losses in range-bound markets
- False Breakout Risk: ROC indicator may produce false breakthrough signals
- Parameter Sensitivity: Strategy performance heavily depends on Bollinger Bands and ROC parameter settings
- Market Environment Dependency: Strategy performs better in trending markets but may fail during extreme volatility
Strategy Optimization Directions
- Introduce Trend Filter: Add long-term moving averages to filter market trends and improve directional accuracy
- Optimize Parameters: Conduct historical data backtesting to find optimal ROC period and Bollinger Bands parameter combinations
- Add Stop-Loss Mechanisms: Implement fixed or trailing stop-losses for risk control
- Include Volume Confirmation: Incorporate volume indicators to validate price breakouts
Summary
The Adaptive Momentum Mean-Reversion Crossover Strategy builds a trading system capable of adapting to different market environments by combining ROC indicators and dual Bollinger Bands. While maintaining flexibility, the strategy emphasizes risk control and demonstrates practical value. Through continuous optimization and improvement, this strategy shows promise for better performance in actual trading.
Source Pine Script
/*backtest
start: 2019-12-23 08:00:00
end: 2025-01-08 08:00:00
period: 1d
basePeriod: 1d
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=6
strategy("Adaptive Momentum Reversion Strategy ", overlay=false, initial_capital=50000, pyramiding=0, commission_type=strategy.commission.cash_per_contract, commission_value=0.05, slippage=1)

// Input: ROC Period
rocPeriod = input.int(2, title="ROC Period", minval=1)

// Input: Bollinger Bands Settings (Lower Band)
bbLowerLength = input.int(18, title="Lower Bollinger Band Length", minval=1)
bbLowerStdDev = input.float(1.7, title="Lower Bollinger Band StdDev", minval=0.1, step=0.1)

// Input: Bollinger Bands Settings (Upper Band)
bbUpperLength = input.int(21, title="Upper Bollinger Band Length", minval=1)
bbUpperStdDev = input.float(2.1, title="Upper Bollinger Band StdDev", minval=0.1, step=0.1)

// ROC Calculation
rocValue = (close - close[rocPeriod]) / close[rocPeriod] * 100

// Bollinger Bands Calculation
bbLowerBasis = ta.sma(rocValue, bbLowerLength)  // Basis for Lower Band
bbLower = bbLowerBasis - bbLowerStdDev * ta.stdev(rocValue, bbLowerLength)  // Lower Band

bbUpperBasis = ta.sma(rocValue, bbUpperLength)  // Basis for Upper Band
bbUpper = bbUpperBasis + bbUpperStdDev * ta.stdev(rocValue, bbUpperLength)  // Upper Band

// Plot ROC
plot(rocValue, color=color.blue, linewidth=2, title="ROC Value")

// Plot Bollinger Bands
plot(bbLowerBasis, color=color.gray, linewidth=1, title="Lower BB Basis (SMA)")
plot(bbLower, color=color.green, linewidth=1, title="Lower Bollinger Band")
plot(bbUpperBasis, color=color.gray, linewidth=1, title="Upper BB Basis (SMA)")
plot(bbUpper, color=color.red, linewidth=1, title="Upper Bollinger Band")

// Add Zero Line for Reference
hline(0, "Zero Line", color=color.gray, linestyle=hline.style_dotted)

// Entry Condition: Long when ROC crosses above the lower Bollinger Band
longCondition = ta.crossover(rocValue, bbLower)
if (longCondition)
    strategy.entry("Long", strategy.long)

// Exit Condition: Exit on Upper Bollinger Band Cross or ROC drops below Lower Band again
exitCondition = ta.crossunder(rocValue, bbUpper)
if (exitCondition)
    strategy.close("Long")

// Background Color for Extreme Conditions
bgcolor(rocValue > bbUpper ? color.new(color.red, 80) : na, title="Overbought (ROC above Upper BB)")
bgcolor(rocValue < bbLower ? color.new(color.green, 80) : na, title="Oversold (ROC below Lower BB)")
Published by ChaoZhang on the FMZ strategy square · last modified 2025-01-10. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Adaptive-Momentum-Mean-Reversion-Crossover-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Multi Indicator Reversal Point Capture Trading StrategyPine Script · Mean reversion · 1d
- Multi Timeframe Adaptive Mean Reversion with Volume Analysis StrategyPine Script · Mean reversion · 1h
- Mean Reversion Bollinger Bands StrategyPine Script · Mean reversion · 1d
- Momentum Reversal Quantitative Trading Strategy Combining Bollinger Bands and RSIPine Script · Mean reversion · 1h
- Bollinger Bands Mean Reversion Trading Strategy with Volume FilterPine Script · Mean reversion · 1h
- Dual Technical Indicator Momentum Reversal Trading Strategy with Risk Management SystemPine Script · Mean reversion · 3h