Adaptive Multi State EMA RSI Momentum Strategy with Choppiness Index Filter System
This strategy is an adaptive system combining trend following and range trading, using the Choppiness Index (CI) to determine market conditions and applying corresponding trading logic. In trending markets, the…
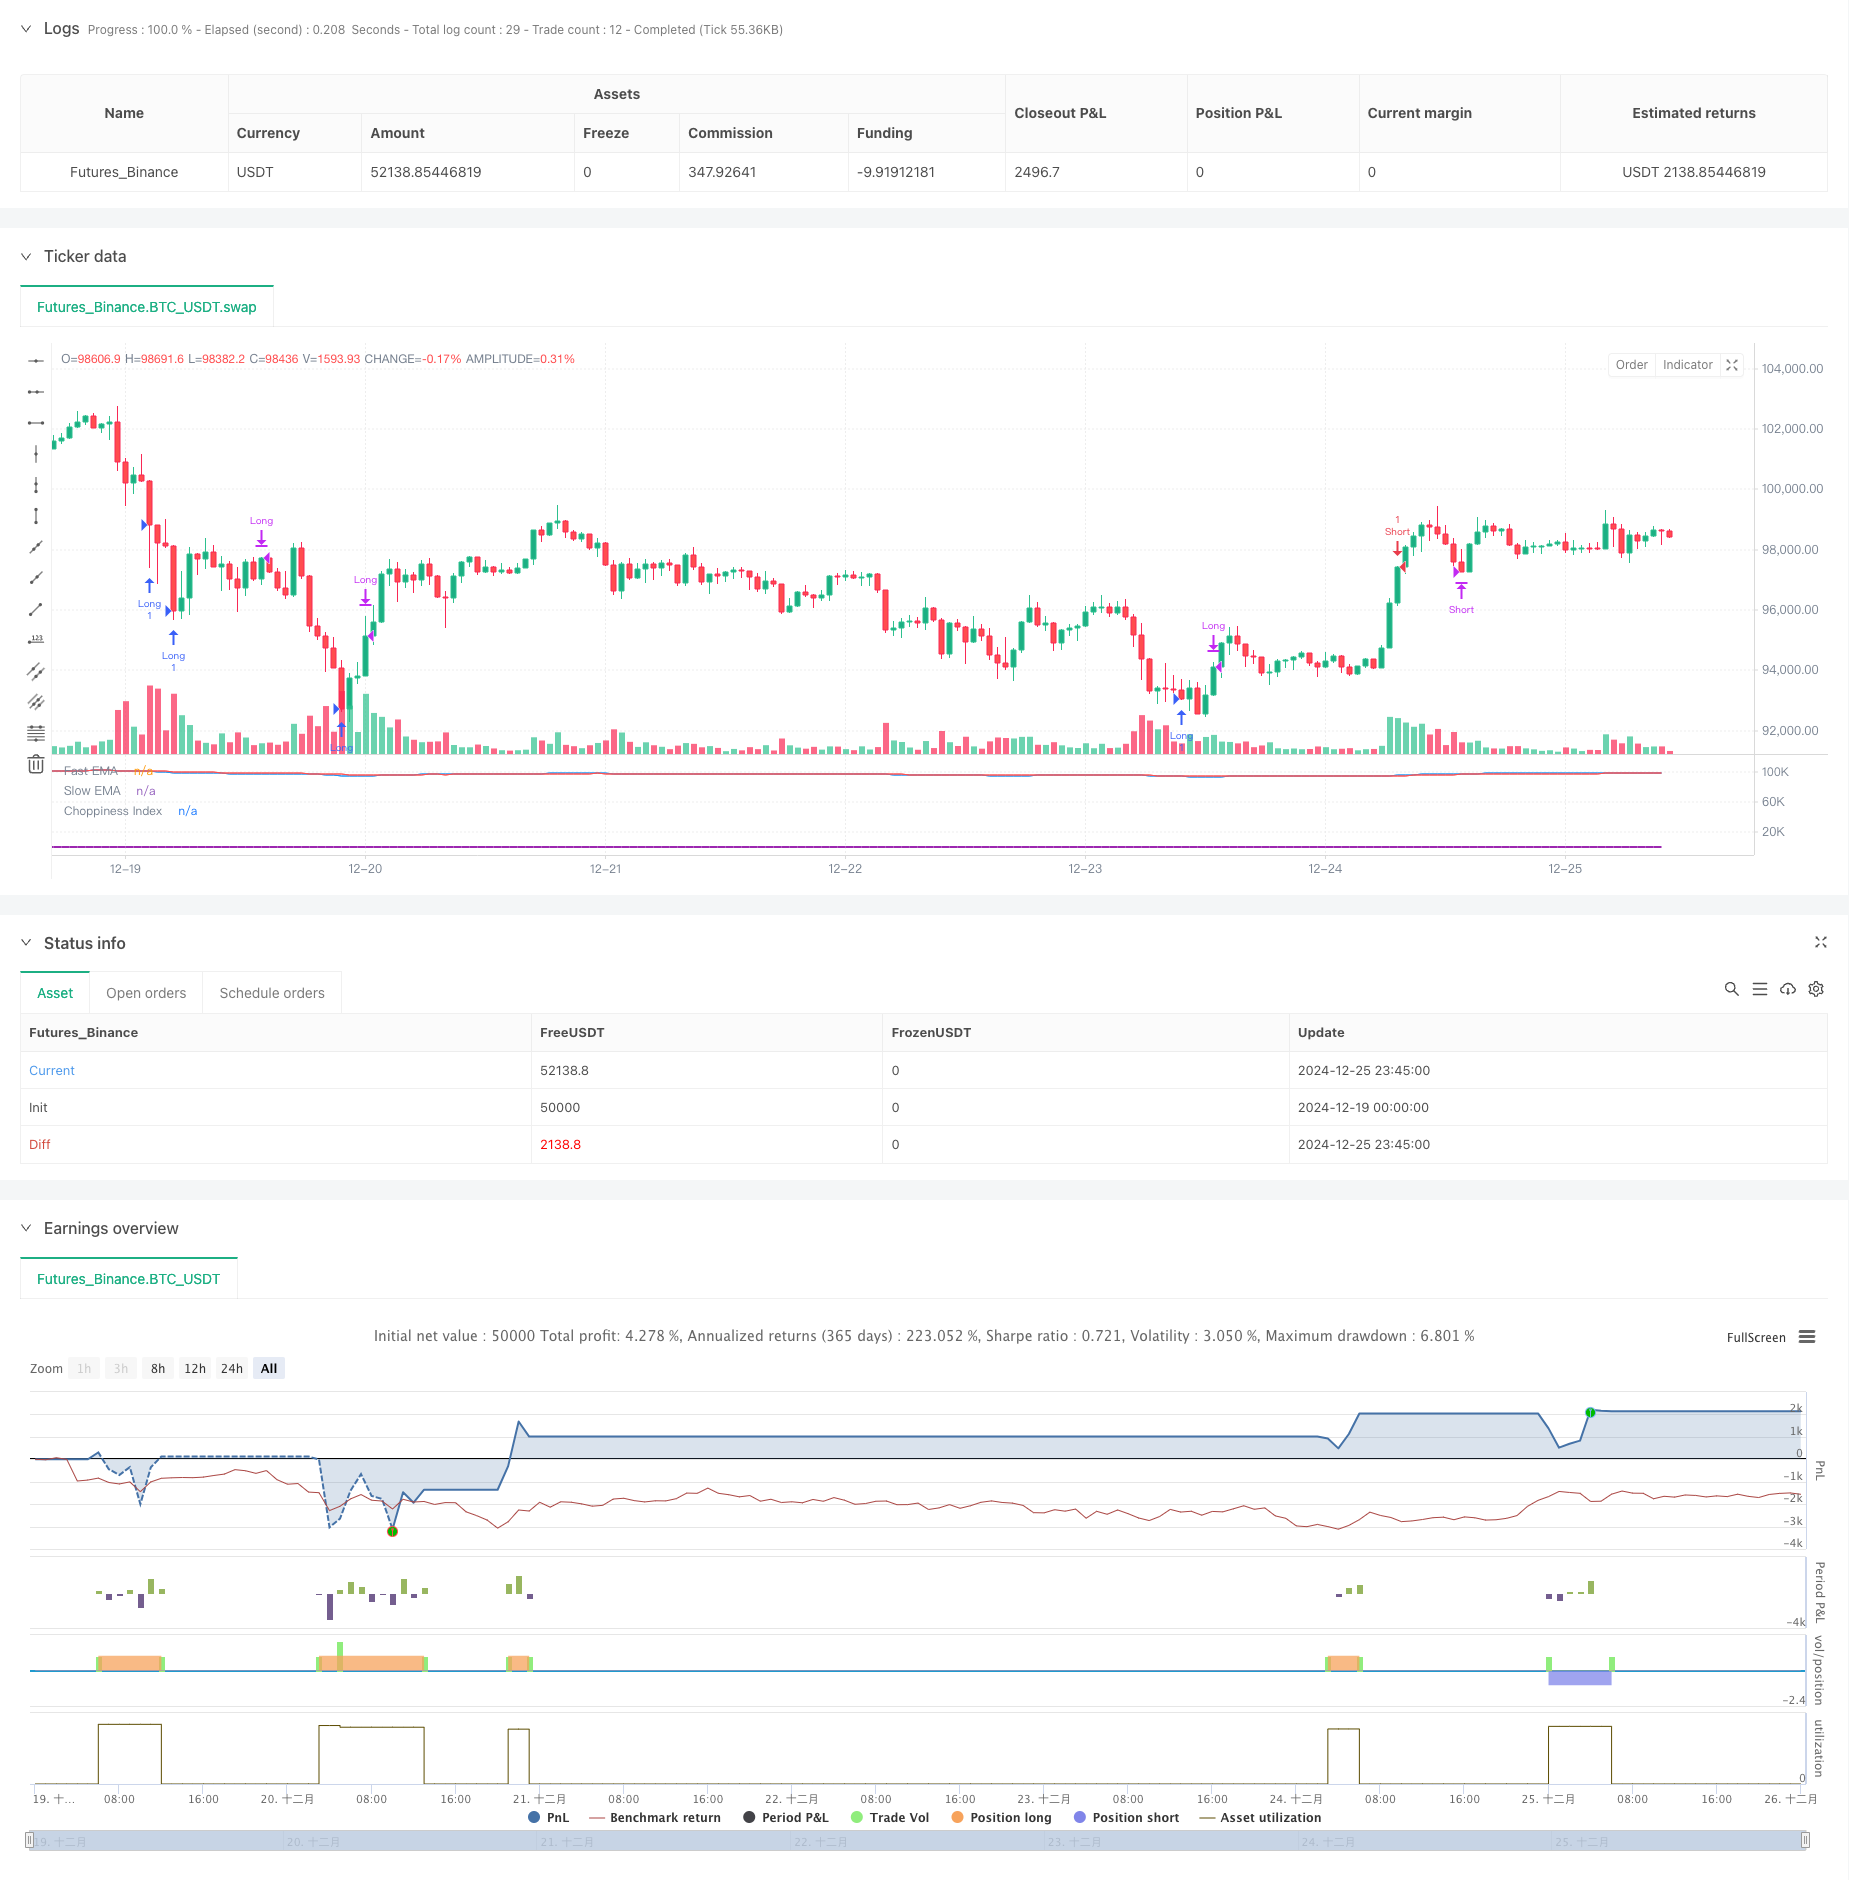
Overview
This strategy is an adaptive system combining trend following and range trading, using the Choppiness Index (CI) to determine market conditions and applying corresponding trading logic. In trending markets, the strategy utilizes EMA crossovers and RSI overbought/oversold signals for trading; in ranging markets, it primarily relies on RSI extreme values. The strategy also includes stop-loss and take-profit mechanisms to control risk and lock in profits.
Strategy Principles
The core of the strategy lies in using the Choppiness Index (CI) to classify the market into trending (CI<38.2) and ranging (CI>61.8) states. In trending markets, long positions are opened when the fast EMA (9-period) crosses above the slow EMA (21-period) and RSI is below 70, while short positions are opened when the slow EMA crosses above the fast EMA and RSI is above 30. In ranging markets, long positions are opened when RSI is below 30, and short positions when RSI is above 70. The strategy includes corresponding exit conditions with 2% stop-loss and 4% take-profit levels.
Strategy Advantages
- High market adaptability: Identifies market states through CI indicator, enabling flexible strategy switching in different market environments
- Multiple signal confirmation: Combines moving averages, momentum indicators, and volatility index for improved signal reliability
- Comprehensive risk management: Includes stop-loss and take-profit mechanisms for effective risk control
- Clear trading logic: Distinguishes between trending and ranging market states with explicit trading rules
- High win rate: Demonstrates 70-80% win rate on 15-minute timeframe
Strategy Risks
- Parameter sensitivity: Multiple technical indicators require complex parameter optimization
- False breakout risk: Potential false signals during market state transitions
- Slippage impact: Possible significant slippage in low liquidity market conditions
- Overtrading: Frequent market state transitions may lead to excessive trading
- Market dependency: Strategy performance may be heavily influenced by specific market conditions
Strategy Optimization Directions
- Dynamic parameter optimization: Adjust indicator parameters based on different market environments
- Additional filters: Add volume and volatility filters to improve signal quality
- Stop-loss optimization: Consider dynamic stop-loss mechanisms like ATR stops or trailing stops
- State identification improvement: Refine market state classification, add neutral market handling logic
- Signal confirmation system development: Implement additional signal confirmation mechanisms to reduce false signals
Summary
This strategy builds an adaptive trading system by combining multiple technical indicators, maintaining stable performance across different market environments. Its core advantages lie in market adaptability and comprehensive risk management mechanisms, while attention must be paid to parameter optimization and market condition dependencies. Through continuous optimization and improvement, the strategy shows promise for achieving better trading results across various market conditions.
Source Pine Script
/*backtest
start: 2024-12-19 00:00:00
end: 2024-12-26 00:00:00
period: 45m
basePeriod: 45m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This Pine Script™ code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © nopology

//@version=6

strategy("CI, EMA, RSI", overlay=false)

// Input parameters
lengthCI = input(14, title="CI Length")
lengthRSI = input(14, title="RSI Length")
fastLength = input(9, title="Fast EMA Length")
slowLength = input(21, title="Slow EMA Length")

// Calculate CI
atr = ta.atr(lengthCI)
highLowRange = math.log10(math.max(high[lengthCI], high) - math.min(low[lengthCI], low))
sumATR = math.sum(atr, lengthCI)
ci = 100 * (math.log10(sumATR / highLowRange) / math.log10(lengthCI))

// Calculate RSI
rsi = ta.rsi(close, lengthRSI)

// Calculate EMAs
fastEMA = ta.ema(close, fastLength)
slowEMA = ta.ema(close, slowLength)

// Define conditions
trendingMarket = ci < 38.2
rangingMarket = ci > 61.8
bullishSignal = ta.crossover(fastEMA, slowEMA) and rsi < 70
bearishSignal = ta.crossover(slowEMA, fastEMA) and rsi > 30

// Plot indicators for visualization
plot(ci, title="Choppiness Index", color=color.purple, linewidth=2)
plot(fastEMA, title="Fast EMA", color=color.blue)
plot(slowEMA, title="Slow EMA", color=color.red)

// Strategy Execution
if (trendingMarket)
    if (bullishSignal)
        strategy.entry("Long", strategy.long)
    if (bearishSignal)
        strategy.entry("Short", strategy.short)
else if (rangingMarket)
    if (rsi < 30)
        strategy.entry("Long", strategy.long)
    if (rsi > 70)
        strategy.entry("Short", strategy.short)

// Close positions when conditions no longer met or reverse
if (trendingMarket and not bullishSignal)
    strategy.close("Long")
if (trendingMarket and not bearishSignal)
    strategy.close("Short")
if (rangingMarket and rsi > 40)
    strategy.close("Long")
if (rangingMarket and rsi < 60)
    strategy.close("Short")

// Optional: Add stop loss and take profit
stopLossPerc = input.float(2, title="Stop Loss (%)", minval=0.1, step=0.1) / 100
takeProfitPerc = input.float(4, title="Take Profit (%)", minval=0.1, step=0.1) / 100

strategy.exit("Exit Long", "Long", stop=close*(1-stopLossPerc), limit=close*(1+takeProfitPerc))
strategy.exit("Exit Short", "Short", stop=close*(1+stopLossPerc), limit=close*(1-takeProfitPerc))Published by ChaoZhang on the FMZ strategy square · last modified 2024-12-27. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Adaptive-Multi-State-EMA-RSI-Momentum-Strategy-with-Choppiness-Index-Filter-System.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Advanced Multi Indicator Trend Following and Momentum Quantitative Trading StrategyPine Script · Momentum · 1h
- Cross Period Momentum EMA Strategy with RSI and Dynamic ATR Stop LossPine Script · Momentum · 1d
- Dual EMA Crossover with RSI Momentum Enhanced Trading StrategyPine Script · Momentum · 1d
- Dynamic Trend Channel and Relative Strength Momentum Trading StrategyPine Script · Momentum · 3h
- KST EMA Momentum Trend Following StrategyPine Script · Momentum · 1d
- Multi EMA Trend Momentum Trading Strategy with Risk Management SystemPine Script · Momentum · 1h