Strategy vault / Trend following
Adaptive Range Volatility Trend Following Trading Strategy
This is an adaptive trend-following strategy that combines volatility and Williams Percent Range indicators. The strategy adjusts trend determination sensitivity by calculating price range and custom counters…
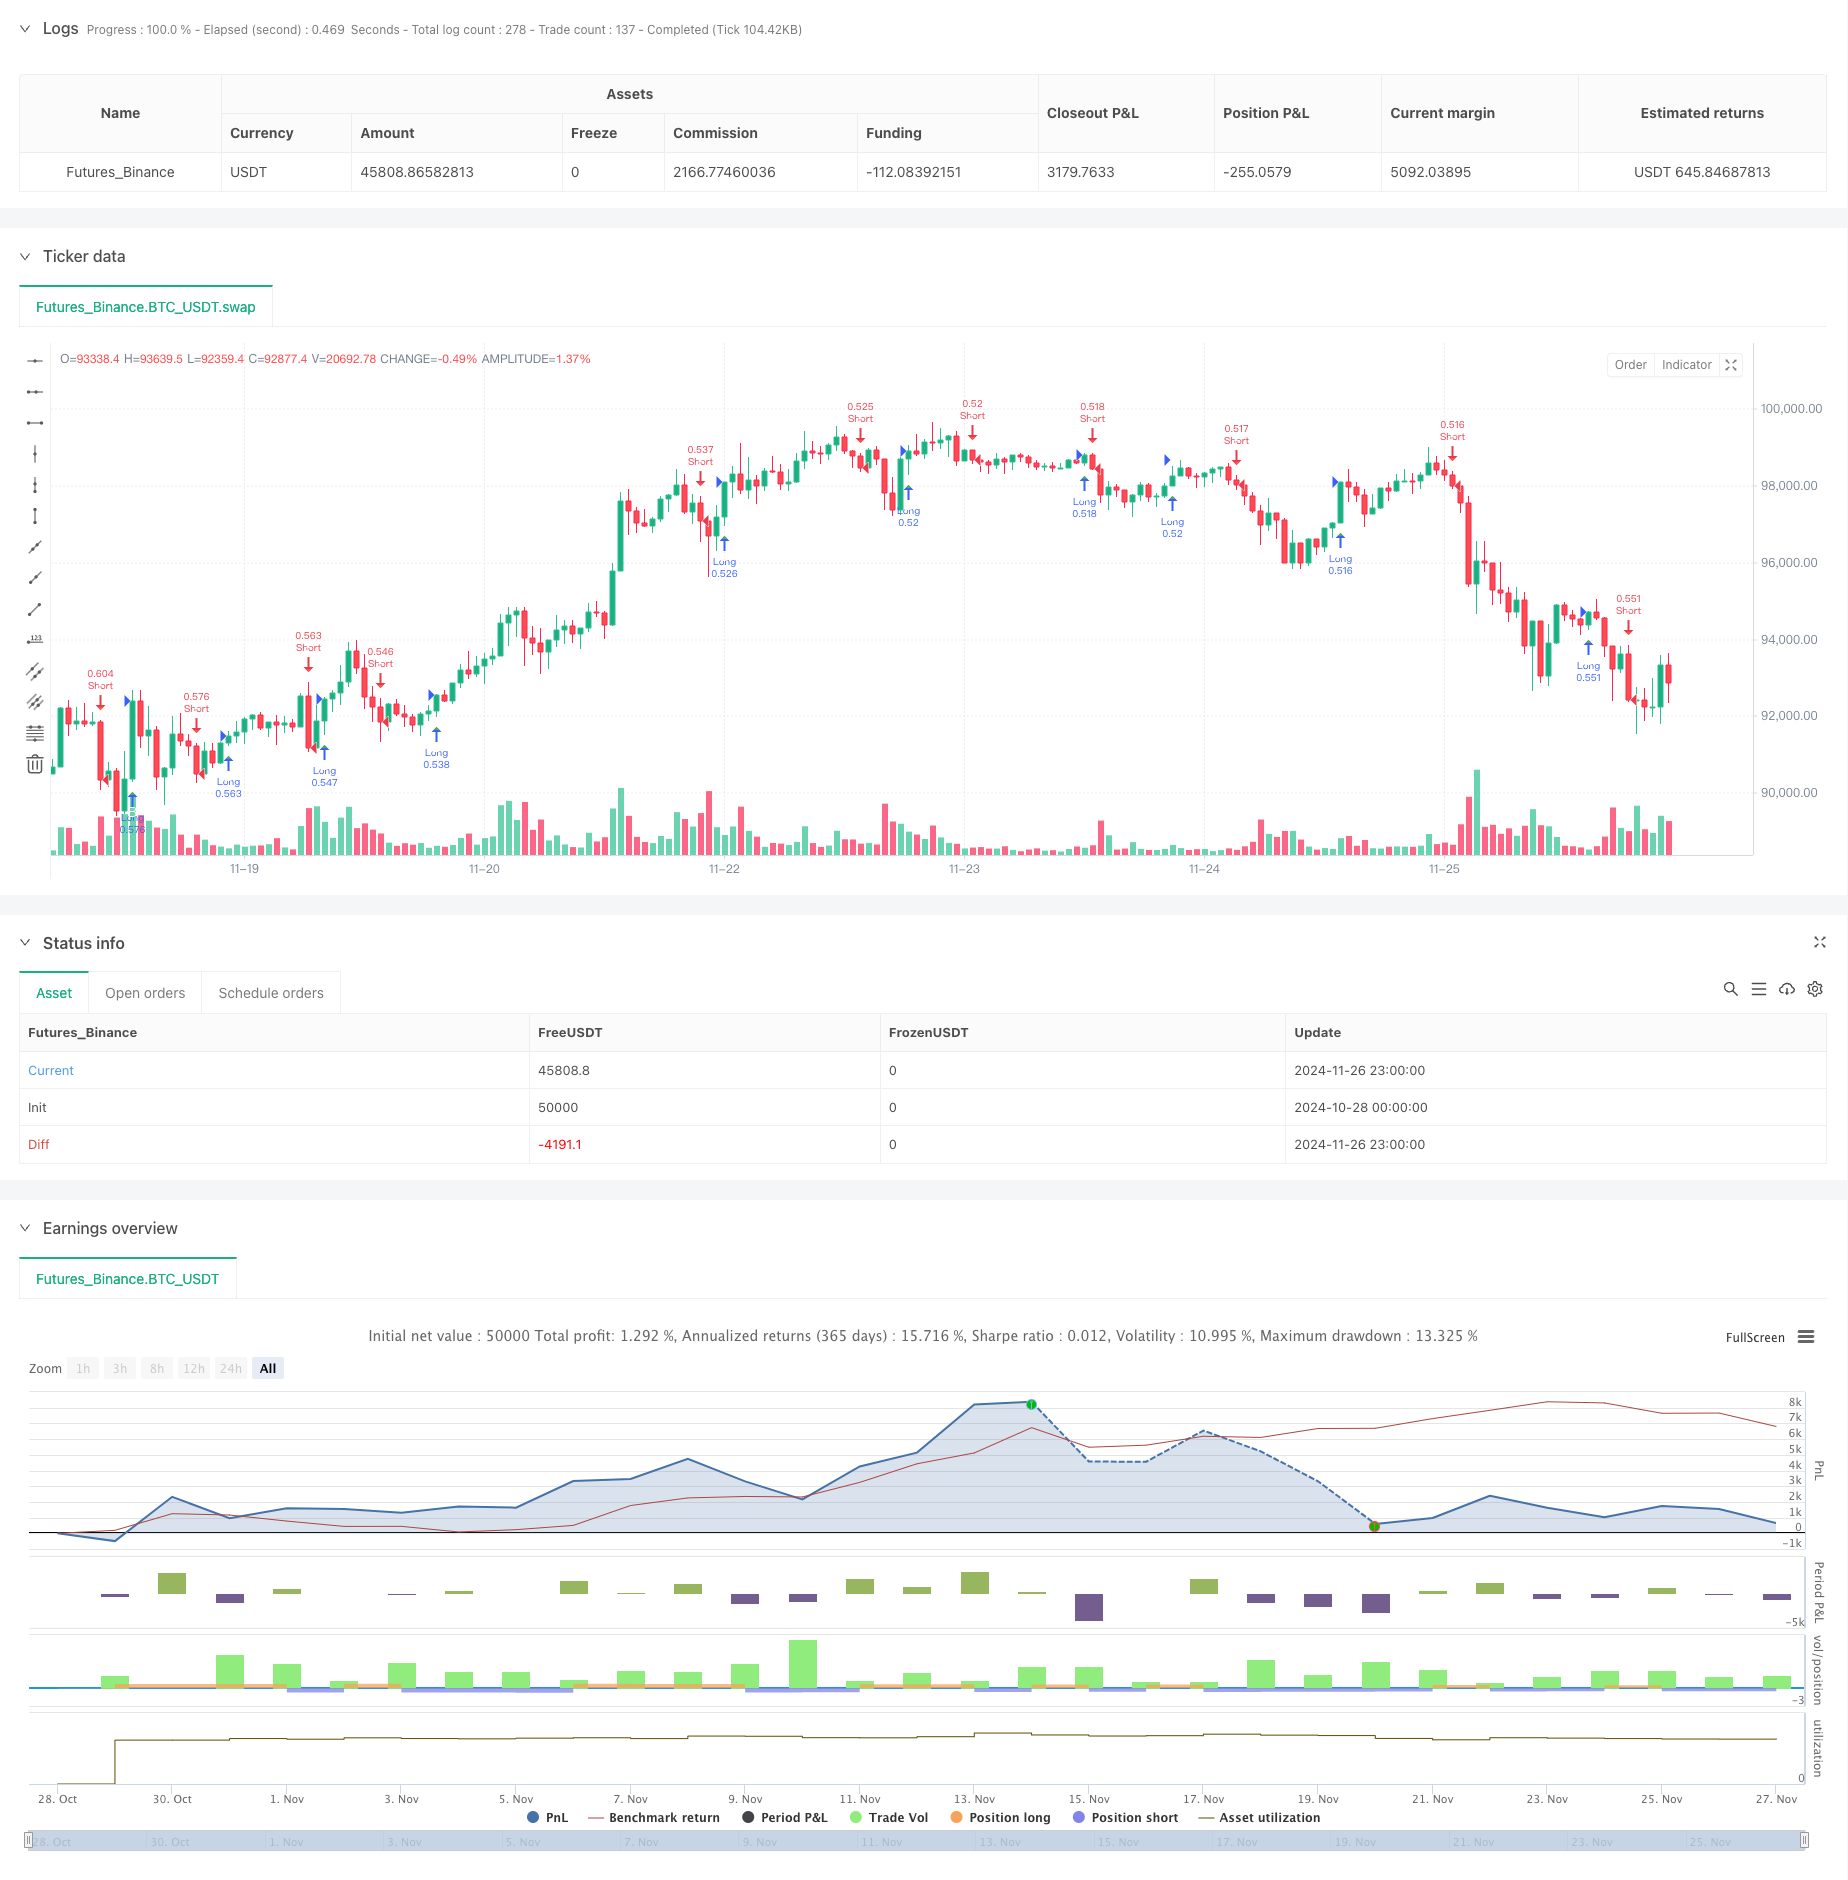
Overview
This is an adaptive trend-following strategy that combines volatility and Williams Percent Range indicators. The strategy adjusts trend determination sensitivity by calculating price range and custom counters, achieving better adaptability in different market conditions. The core mechanism involves dynamically adjusting Williams indicator parameters based on price volatility to more accurately capture market trend transition points.
Strategy Principles
The strategy begins by calculating price range and its moving average (AvgRange) within a period. By comparing real-time price changes with average volatility range, it establishes two counters (TrueCount and TrueCount2) to record significant volatility frequency. These counters are used to dynamically adjust Williams indicator calculation parameters, allowing the strategy to automatically adapt its sensitivity based on market volatility conditions. Buy or sell signals are generated when the adjusted Williams indicator values break through preset thresholds.
Strategy Advantages
- Strong Adaptability - Strategy maintains stable performance across different market environments through volatility adaptation mechanism
- Comprehensive Risk Control - Built-in RISK parameter allows traders to adjust strategy aggressiveness based on risk preference
- Clear Signals - Uses clear breakthrough signal mechanism to avoid false signals
- Good Scalability - Strategy framework allows integration of other technical indicators for optimization
- High Computational Efficiency - Uses simple and efficient calculation methods suitable for real-time trading
Strategy Risks
- Parameter Sensitivity - Choice of ASClength and RISK parameters significantly affects strategy performance
- Market Environment Dependency - May generate excessive trading signals in oscillating markets
- Latency - Use of moving averages may cause entry and exit delays
- False Breakouts - False signals may occur during high volatility periods Recommend optimizing parameters through backtesting and combining with other confirmation indicators to reduce risks.
Optimization Directions
- Incorporate Volume Indicators - Confirm trend change validity through volume analysis
- Optimize Counter Logic - Consider using more complex statistical methods to evaluate market volatility
- Add Stop Loss Mechanism - Suggest implementing dynamic stop loss for better risk control
- Market Environment Filtering - Add market condition assessment module to avoid trading in unsuitable conditions
- Parameter Adaptation - Develop parameter auto-optimization mechanism to improve strategy adaptability
Summary
This innovative strategy combines volatility analysis and trend following, improving strategy stability and reliability through adaptive mechanisms. While inherent risks exist, the strategy can maintain stable performance across various market conditions through proper parameter settings and optimization implementation. The strategy framework allows for further expansion and optimization, showing good development potential.
Source Pine Script
/*backtest
start: 2024-10-28 00:00:00
end: 2024-11-27 00:00:00
period: 1h
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("ASCTrend", shorttitle="ASCTrend", overlay=true, default_qty_type=strategy.percent_of_equity, default_qty_value=100)

eternalfg = input(false, title="eternal Confirm")
eternal = eternalfg ? 1 : 0
ASClength = input.int(title="ASC Length", minval=4, defval=10)
RISK = input.int(title="RISK", minval=0, defval=3)

// Custom sum function
customSum(source, length) =>
    sum = 0.0
    for i = 0 to length - 1
        sum := sum + source[i]
    sum

x1 = 67 + RISK
x2 = 33 - RISK
Range = ta.highest(ASClength) - ta.lowest(ASClength)
AvgRange = ta.sma(Range, ASClength)
CountFg = math.abs(open - close) >= AvgRange * 2.0 ? 1 : 0
TrueCount = customSum(CountFg, ASClength)
CountFg2 = math.abs(close[3] - close) >= AvgRange * 4.6 ? 1 : 0
TrueCount2 = customSum(CountFg2, ASClength - 3)
wpr3RR = ta.wpr(3 + RISK + RISK)
wpr3 = ta.wpr(3)
wpr4 = ta.wpr(4)
WprAbs = 100 + (TrueCount2 > 0 ? wpr4 : TrueCount > 0 ? wpr3 : wpr3RR)
ASC_Trend = 0
ASC_Trend := WprAbs[eternal] < x2[eternal] ? -1 : WprAbs[eternal] > x1[eternal] ? 1 : ASC_Trend[1]

if (ta.crossover(ASC_Trend, 0))
    strategy.entry("Long", strategy.long)

if (ta.crossunder(ASC_Trend, 0))
    strategy.entry("Short", strategy.short)

plotshape(ta.crossover(ASC_Trend, 0), location=location.belowbar, color=color.green, style=shape.triangleup, size=size.small, text="B", textcolor=color.white)
plotshape(ta.crossunder(ASC_Trend, 0), location=location.abovebar, color=color.red, style=shape.triangledown, size=size.small, text="S", textcolor=color.white)

alertcondition(ta.crossover(ASC_Trend, 0), title="ASC_Trend UP", message="ASC_Trend UP")
alertcondition(ta.crossunder(ASC_Trend, 0), title="ASC_Trend Down", message="ASC_Trend Down")
Published by ChaoZhang on the FMZ strategy square · last modified 2024-11-28. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Adaptive-Range-Volatility-Trend-Following-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ADX MA and EMA Long Only Trend Tracking StrategyPine Script · Trend following · 1d
- ATR and Moving Average Crossover Hybrid StrategyPine Script · Trend following · 1h
- Adaptive FVG Detection and MA Trend Trading Strategy with Dynamic ResistancePine Script · Trend following · 1d
- Adaptive Risk Management Strategy Based on Dynamic ATR and Moving Average CrossoverPine Script · Trend following · 2h
- Adaptive Trading Strategy Based on Stochastic RSI Dual Line CrossoverPine Script · Trend following · 4h
- Adaptive Volatility Based Trend Following Short Strategy with Time Delay and Stop Loss ProtectionPine Script · Trend following · 2m