Adaptive Stop Loss Rail Strategy
The main idea of this strategy is to combine Kalman filter and tracking stop loss to build a dynamically adjusted stop loss rail. The Kalman filter is used to track prices and give predicted values. The stop loss…
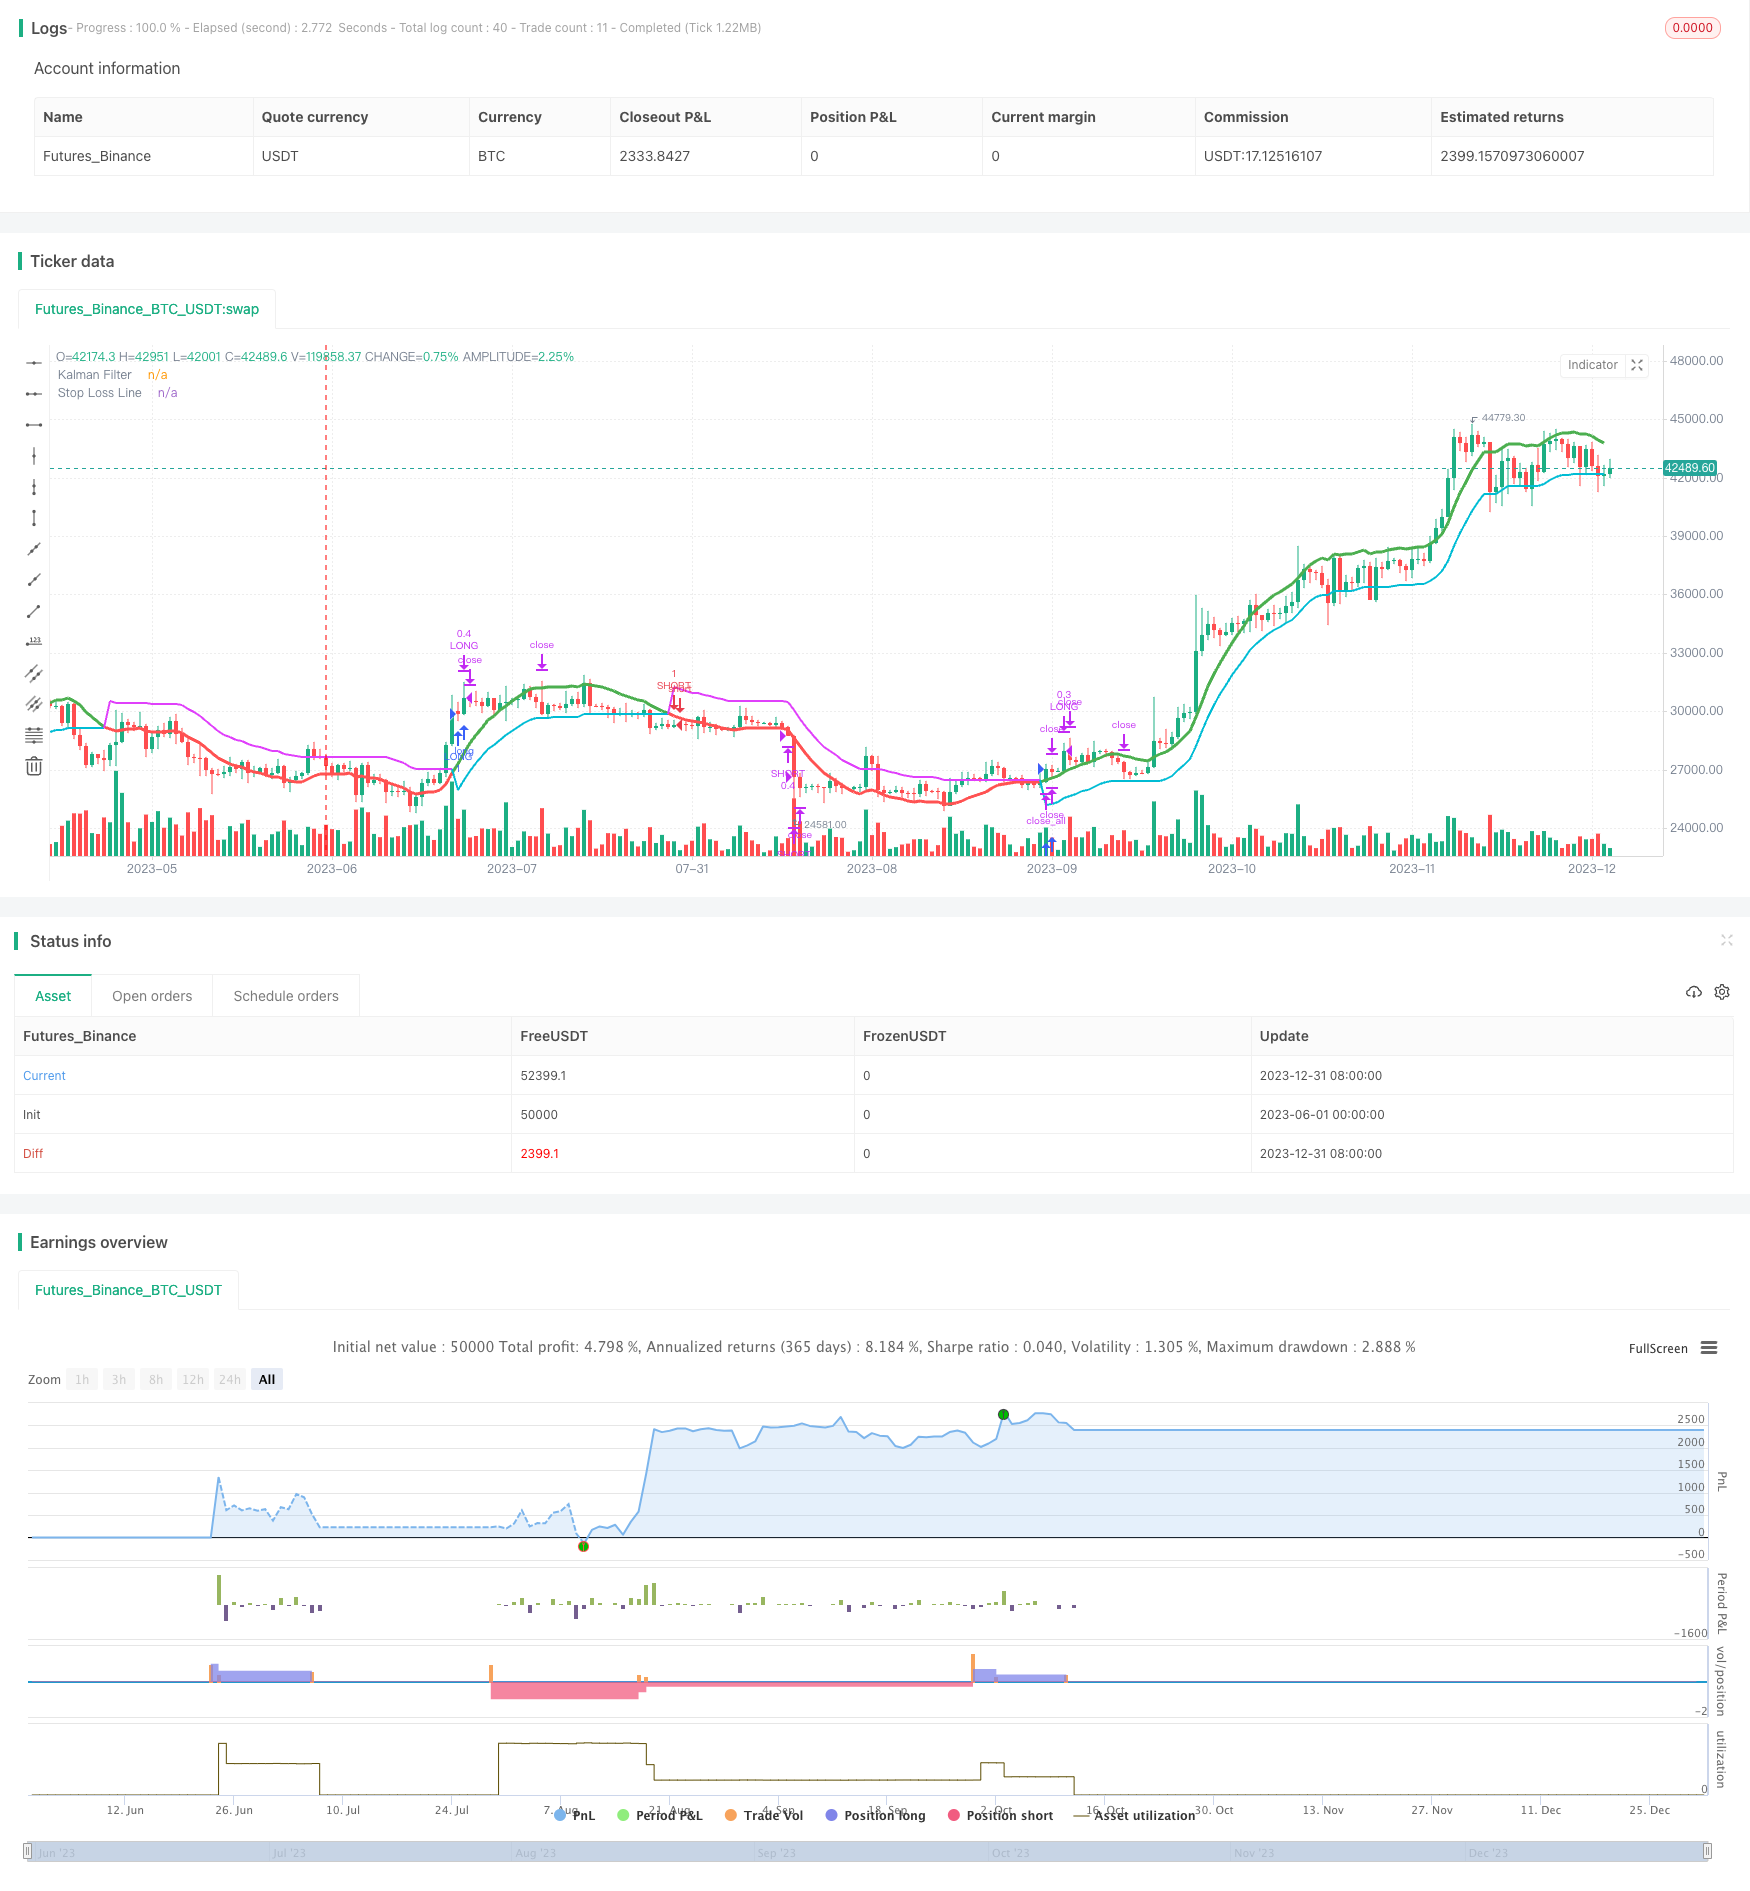
Overview
The main idea of this strategy is to combine Kalman filter and tracking stop loss to build a dynamically adjusted stop loss rail. The Kalman filter is used to track prices and give predicted values. The stop loss rail is constructed based on predictions at a certain percentage to achieve dynamic tracking of prices. This allows maximum profit during the trend phase while timely stop loss during reversal.
The whole strategy can achieve good results in trending markets.
Strategy Principle
The strategy consists of the following main parts:
Kalman filter
- Predict prices using recursive algorithm
- Smooth prices and give predicted values
Stop loss rail
- Constructed based on predicted values at set ratio
- The ratio will decrease gradually approaching predictions as bars progress
- Stop loss when price breaks the rail
Pyramiding and taking profit
- Use martingale method to add position on losses
- Set up multiple take profit points
The main operating flow of the whole strategy is:
- Kalman filter predicts prices
- Set stop loss rail based on predicted price and ratio
- As price moves towards favorable direction, stop loss rail approaches progressively to maximize profit
- If price breaks the rail, stop loss kicks in
- Increase position size to pyramid on losses
- Set up multiple take profit points to secure profit
Advantage Analysis
The main advantages of this strategy:
- Utilize Kalman filter to predict prices, smoother and more accurate than other indicators
- Adaptive stop loss rail can adjust based on actual situation to maximize profit
- Pyramiding and multiple take profit mechanism to yield more profit in trending moves
- Highly configurable parameters for flexible adjustments
Risk Analysis
The main risks of this strategy:
- StartStop may trigger frequently in ranging moves, increasing trading frequency and fees
- Although pyramiding mechanism can amplify gains in trends, it also increases risks and DD
- Although multiple take profit secures profit, it also reduces profit potential
Risks can be reduced through:
- Suspend trading in ranging market
- Adjust pyramiding and take profit parameters to lower risk
Optimization Direction
The strategy can be further optimized through:
- Add filters to identify trends and ranges
- Incorporate more indicators to filter false signals
- Consider clearing all positions if losses exceed certain threshold
- Add position sizing module
- Different parameter sets can be backtested and optimized for different markets
Summary
In summary, this adaptive stop loss rail strategy uniquely combines Kalman prediction and dynamic stop loss. With proper parameter tuning, it can achieve good results. Further modularization and optimization can make this strategy more complete for application in more markets.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_float_1 | 100 | Kalman Gain: |
| v_input_1_close | 0 | Source:: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_float_2 | 5 | Beginning Approach(%) |
| v_input_float_3 | true | Final Approach(%) |
| v_input_float_4 | 0.001 | Approach Decrease Step |
| v_input_float_5 | 100 | Base Order Quantity |
| v_input_int_1 | 4 | Max Safe Order Attemp |
| v_input_float_6 | 3 | Safe Order Deviation |
| v_input_float_7 | true | Profit Deviation |
| v_input_float_8 | 25 | Max Take Profit(%) |
| v_input_float_9 | true | Max Order Quantity |
| v_input_float_10 | true | TP1(%) |
| v_input_int_2 | 40 | QT1(%): |
| v_input_float_11 | 3 | TP2(%) |
| v_input_int_3 | 30 | QT2(%): |
| v_input_float_12 | 5 | TP3(%) |
| v_input_int_4 | 30 | QT3(%): |
| v_input_float_13 | false | Stop Loss(%) |
| v_input_bool_1 | true | Long Entry |
| v_input_bool_2 | true | Short Entry |
| v_input_bool_3 | true | Safe Stop After TP2 |
| v_input_bool_4 | false | Safe Stop After TP1 |
| v_input_int_5 | true | From Date: |
| v_input_int_6 | true | / |
| v_input_int_7 | 2021 | / |
| v_input_int_8 | 30 | To__ Date: |
| v_input_int_9 | 12 | / |
| v_input_int_10 | 2022 | / |
Source Pine Script
/*backtest
start: 2023-06-01 00:00:00
end: 2024-01-01 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © BigCoinHunter

    //  ____  _        _____      _       _    _             _
    // |  _ \(_)      / ____|    (_)     | |  | |           | |
    // | |_) |_  __ _| |     ___  _ _ __ | |__| |_   _ _ __ | |_ ___ _ __
    // |  _ <| |/ _` | |    / _ \| | '_ \|  __  | | | | '_ \| __/ _ \ '__|
    // | |_) | | (_| | |___| (_) | | | | | |  | | |_| | | | | ||  __/ |
    // |____/|_|\__, |\_____\___/|_|_| |_|_|  |_|\__,_|_| |_|\__\___|_|
    //           __/ |
    //          |___/

//@version=5
strategy(title='Loft Strategy V4', overlay=true,
     pyramiding=0, default_qty_type=strategy.cash,
     default_qty_value=100, initial_capital=10000,
     currency=currency.USD, commission_value=0.05,
     commission_type=strategy.commission.percent,
     process_orders_on_close=true)

//-------------- fetch user inputs ------------------
gain = input.float(title="Kalman Gain:", defval=100.0, minval=1, maxval=10000.0, step=1)
src = input(defval=close, title='Source:')

stopPercentBase = input.float(title='Beginning Approach(%)', defval=5.0, minval=0.1, maxval=30.0, step=0.1)
stopPercentMin = input.float(title='Final Approach(%)', defval=1.0, minval=0.1, maxval=30.0, step=0.1)
downStep = input.float(title='Approach Decrease Step', defval=0.001, minval=0.0, maxval = 5, step=0.001)
//stopPercentDeviation = input.float(title="Approach Deviation", defval=1.0, minval=0.1, maxval = 5.0, step=0.1)

baseOrderQty = input.float(title="Base Order Quantity", defval=100.0, minval=0.001)
maxOrderCount = input.int(title="Max Safe Order Attemp", defval=4, minval=1)
priceDeviation = input.float(title="Safe Order Deviation", defval=3, minval=1.0, step=0.1)
profitDeviation = input.float(title="Profit Deviation", defval=1.0, minval=1.0, maxval=10, step=0.1)
maxTakeProfit = input.float(title="Max Take Profit(%)", defval=25.0, maxval=100, step=0.1)
maxOrderQty = input.float(title="Max Order Quantity", defval=1.0, minval=0.01)

baseTP1 = input.float(title="TP1(%)", defval=1.0, minval=0.0, maxval=100.0, step=0.1, inline="0")
qt1     = input.int(title="QT1(%):", defval=40, minval=1, maxval=100, step=5, inline="0")

baseTP2 = input.float(title="TP2(%)", defval=3.0, minval=0.0, maxval=100.0, step=0.1, inline="1")
qt2     = input.int(title="QT2(%):", defval=30, minval=1, maxval=100, step=5, inline="1")

baseTP3 = input.float(title="TP3(%)", defval=5.0, minval=0.0, maxval=100.0, step=0.1, inline="2")
qt3     = input.int(title="QT3(%):", defval=30, minval=1, maxval=100, step=5, inline="2")

initialStopLoss = input.float(title="Stop Loss(%)", defval=0.0, minval=0.0, maxval=100.0, step=0.1)

longEntry = input.bool(defval=true, title= 'Long Entry', inline="3")
shortEntry = input.bool(defval=true, title='Short Entry', inline="3")

useSafeStop2 = input.bool(defval = true, title="Safe Stop After TP2", inline="6")
useSafeStop1 = input.bool(defval = false, title="Safe Stop After TP1", inline="6")

//---------- backtest range setup ------------
fromDay   = input.int(defval = 1, title = "From Date:", minval = 1, maxval = 31, inline="4")
fromMonth = input.int(defval = 1, title = "/", minval = 1, maxval = 12, inline="4")
fromYear  = input.int(defval = 2021, title = "/", minval = 2010, inline="4")
toDay     = input.int(defval = 30, title = "To__ Date:", minval = 1, maxval = 31, inline="5")
toMonth   = input.int(defval = 12, title = "/", minval = 1, maxval = 12, inline="5")
toYear    = input.int(defval = 2022, title = "/", minval = 2010, inline="5")

//------------ time interval setup -----------
start     = timestamp(fromYear, fromMonth, fromDay, 00, 00)  // backtest start window
finish    = timestamp(toYear, toMonth, toDay, 23, 59)        // backtest finish window
window()  => true // create function "within window of time"


//------- define the order comments ------
enterLongComment = ""
exitLongComment = ""

enterShortComment = ""
exitShortComment = ""

longTPSL = ""
longTP = ""
longSL = ""

shortTPSL = ""
shortTP = ""
shortSL = ""

//--------- Define global variables -----------
var bool long = true
var bool stoppedOutLong = false
var bool stoppedOutShort = false
var float kf = 0.0
var float velo = 0.0

var float orderQty = baseOrderQty
var float stopLoss = initialStopLoss
var bool isProfit = false
var int barindex = 1
var int winCounter = 0
var int winCounterBuffer = 0
var int failCounter = 0

var float tp1 = baseTP1
var float tp2 = baseTP2
var float tp3 = baseTP3

var bool isTakeTP1 = false
var bool isTakeTP2 = false
var bool isTakeTP3 = false
var bool isLastProfit = true

var float stopPercentMax = stopPercentBase
var float stopPercent = stopPercentBase
var float stopLine = 0.0

var labelColor = color.blue


//------ kalman filter calculation --------
dk = src - nz(kf[1], src)
smooth = nz(kf[1], src) + dk * math.sqrt(gain / 10000 * 2)
velo := nz(velo[1], 0) + gain / 10000 * dk
kf := smooth + velo


//--------- calculate the loft stopLoss line ---------
//stopPercentMax := isLastProfit ? stopPercentBase : (stopPercentBase * stopPercentDeviation)

if long == true
    stopLine := kf - (kf * (stopPercent / 100))

    if long[1] == true and stopLine <= stopLine[1]
        stopLine := stopLine[1]
    else if (long[1] == true)
        stopPercent := stopPercent - downStep
        if(stopPercent < stopPercentMin)
            stopPercent := stopPercentMin

    if(kf < stopLine)
        long := false
        stopPercent := stopPercentMax
        stopLine := kf + (kf * (stopPercent / 100))

else
    stopLine := kf + (kf * (stopPercent / 100))

    if long[1] == false and stopLine >= stopLine[1]
        stopLine := stopLine[1]
    else if(long[1] == false)
        stopPercent := stopPercent - downStep
        if(stopPercent < stopPercentMin)
            stopPercent := stopPercentMin

    if(kf > stopLine)
        long := true
        stopPercent := stopPercentMax
        stopLine := kf - (kf * (stopPercent / 100))


//------------------- determine buy and sell points ---------------------
buySignall = window() and long  and (not stoppedOutLong)
sellSignall = window() and (not long)  and (not stoppedOutShort)


if longEntry and shortEntry

    if buySignall and baseTP1 <= 0.0

        if strategy.position_size < 0
            if close < strategy.position_avg_price
                isLastProfit := true
        else if strategy.position_size == 0
            if strategy.wintrades > winCounter //strategy.wintrades[ barindex ]
                isLastProfit := true
        else
            isLastProfit := false

    else if sellSignall and baseTP1 <= 0.0

        if strategy.position_size > 0
            if close > strategy.position_avg_price
                isLastProfit := true
        else if strategy.position_size == 0
            if strategy.wintrades > winCounter //strategy.wintrades[ barindex ]
                isLastProfit := true
        else
            isLastProfit := false

    else if isTakeTP2 == true
        isLastProfit := true
    else
        isLastProfit := false

else if longEntry
    if sellSignall
        winCounterBuffer := winCounter
    if buySignall
        if winCounter > winCounterBuffer
            isLastProfit := true
        else
            isLastProfit := false

else if shortEntry
    if buySignall
        winCounterBuffer := winCounter
    if sellSignall
        if winCounter > winCounterBuffer
            isLastProfit := true
        else
            isLastProfit := false


//------------- set the deviations ------------
var float maxOrderSize = (baseOrderQty * math.pow(priceDeviation, maxOrderCount - 1))

if buySignall or sellSignall

    if isLastProfit == false

        orderQty := orderQty * priceDeviation

        tp1 := tp1 * profitDeviation
        tp2 := tp2 * profitDeviation
        tp3 := tp3 * profitDeviation

        tp1 := math.min(tp1, maxTakeProfit)
        tp2 := math.min(tp2, maxTakeProfit)
        tp3 := math.min(tp3, maxTakeProfit)

        if orderQty > maxOrderSize
            failCounter := failCounter + 1
            orderQty := baseOrderQty
            tp1 := baseTP1
            tp2 := baseTP2
            tp3 := baseTP3

    else
        orderQty := baseOrderQty
        tp1 := baseTP1
        tp2 := baseTP2
        tp3 := baseTP3


// ----------------- put debug labels -------------------
if orderQty == maxOrderSize
    labelColor := color.red
else
    labelColor := isLastProfit ? color.lime : color.yellow

if longEntry and shortEntry
    if buySignall or sellSignall
        label.new( x=bar_index, y=high, text="Qty:"+str.tostring(math.min(orderQty, maxOrderQty))+" | Worst Case:"+str.tostring(failCounter) ,color = labelColor  )
else if longEntry
    if buySignall
        label.new( x=bar_index, y=high, text="Qty:"+str.tostring(math.min(orderQty, maxOrderQty))+" | Worst Case:"+str.tostring(failCounter) ,color = labelColor  )
else if shortEntry
    if sellSignall
        label.new( x=bar_index, y=high, text="Qty:"+str.tostring(math.min(orderQty, maxOrderQty))+" | Worst Case:"+str.tostring(failCounter) ,color = labelColor  )


//---------- execute the strategy -----------------
nz(orderQty, baseOrderQty)

if longEntry and shortEntry

    if long
        strategy.close_all( when = buySignall, comment = exitShortComment)
        strategy.entry("LONG", strategy.long, when = buySignall, qty=math.min(orderQty, maxOrderQty), comment = enterLongComment)
        stoppedOutLong := true
        stoppedOutShort := false

    else
        strategy.close_all(when=sellSignall, comment = exitLongComment)
        strategy.entry("SHORT", strategy.short, when = sellSignall, qty=math.min(orderQty, maxOrderQty), comment = enterShortComment)
        stoppedOutLong  := false
        stoppedOutShort := true

else if(longEntry)
    strategy.entry("LONG", strategy.long,  when = buySignall, qty=math.min(orderQty, maxOrderQty), comment = enterLongComment)
    strategy.close("LONG", when = sellSignall, comment = exitLongComment)
    if long
        stoppedOutLong := true
        stoppedOutShort := false
    else
        stoppedOutLong  := false
        stoppedOutShort := true

else if(shortEntry)
    strategy.entry("SHORT", strategy.short, when = sellSignall, qty=math.min(orderQty, maxOrderQty), comment = enterShortComment)
    strategy.close("SHORT", when = buySignall, comment = exitShortComment)
    if not long
        stoppedOutShort := true
        stoppedOutLong  := false
    else
        stoppedOutShort := false
        stoppedOutLong := true


//--------- calculate the TP/SL entries -----------
longProfitPrice1  = strategy.position_avg_price * (1 + tp1 * 0.01)
longProfitPrice2  = strategy.position_avg_price * (1 + tp2 * 0.01)
longProfitPrice3  = strategy.position_avg_price * (1 + tp3 * 0.01)

shortProfitPrice1  = strategy.position_avg_price * (1 - tp1 * 0.01)
shortProfitPrice2  = strategy.position_avg_price * (1 - tp2 * 0.01)
shortProfitPrice3  = strategy.position_avg_price * (1 - tp3 * 0.01)

longStopPrice = strategy.position_avg_price * (1 - stopLoss * 0.01)
shortStopPrice = strategy.position_avg_price * (1 + stopLoss * 0.01)

shortSafeStopPrice2 = strategy.position_avg_price * (1 - 0.2 * 0.01)
longSafeStopPrice2 = strategy.position_avg_price * (1 + 0.2 * 0.01)

longSafeStopPrice1 = stopLine
shortSafeStopPrice1 = stopLine

//----------- calculate TP quantity values -----------
takeQty1 = math.min(orderQty, maxOrderQty) * qt1 / 100
takeQty2 = math.min(orderQty, maxOrderQty) * qt2 / 100
takeQty3 = math.min(orderQty, maxOrderQty) * qt3 / 100


//----------------- take profit and stop loss processes -----------------
if strategy.position_size > 0

    if close > longProfitPrice1 and tp1 > 0 and isTakeTP1 == false
        strategy.close(id="LONG", qty=takeQty1, comment = "longTP 1")
        isTakeTP1 := true

    if close > longProfitPrice2 and tp2 > 0 and isTakeTP2 == false
        strategy.close(id="LONG", qty=takeQty2, comment = "longTP 2")
        isTakeTP2 := true

    if close > longProfitPrice3 and tp3 > 0 and isTakeTP3 == false
        strategy.close(id="LONG", qty=takeQty3, comment = "longTP 3")
        isTakeTP3 := true

    if isTakeTP2 == true and useSafeStop2
        strategy.exit(id="LONG", stop=longSafeStopPrice2, comment = "Long Safe Stop2")
    if isTakeTP1 == true and useSafeStop1
        strategy.exit(id="LONG", stop=longSafeStopPrice1, comment = "Long Safe Stop1")


if strategy.position_size < 0

    if close < shortProfitPrice1 and tp1 > 0 and isTakeTP1 == false
        strategy.close(id="SHORT", qty=takeQty1, comment = "Short TP 1")
        isTakeTP1 := true

    if close < shortProfitPrice2 and tp2 > 0 and isTakeTP2 == false
        strategy.close(id="SHORT", qty=takeQty2, comment = "Short TP 2")
        isTakeTP2 := true

    if close < shortProfitPrice3 and tp3 > 0 and isTakeTP3 == false
        strategy.close(id="SHORT", qty=takeQty3, comment = "Short TP 3")
        isTakeTP3 := true

    if isTakeTP2 == true and useSafeStop2
        strategy.exit(id="SHORT", stop=shortSafeStopPrice2, comment = "Short Safe Stop2")
    if isTakeTP1 == true and useSafeStop1
        strategy.exit(id="SHORT", stop=shortSafeStopPrice1, comment = "Short Safe Stop1")

if(initialStopLoss>0.0)
    if ( strategy.position_size > 0 )
        strategy.exit(id="LONG",  stop=longStopPrice, comment = "Long Stop Loss")

    else if ( strategy.position_size < 0 )
        strategy.exit(id="SHORT",  stop=shortStopPrice,  comment = "Short Stop Loss")


if buySignall or sellSignall

    isTakeTP1 := false
    isTakeTP2 := false
    isTakeTP3 := false

    // winCounter := strategy.wintrades


//------------- plot charts ---------------------
lineColor1 = long ? color.green : color.red
lineColor2 = long ? color.aqua : color.fuchsia

kalmanPlot = plot(kf, color=lineColor1, linewidth=3, title = "Kalman Filter")
stopPlot = plot(stopLine, color=lineColor2, linewidth=2, title = "Stop Loss Line")
Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-02. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Adaptive-Stop-Loss-Rail-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Bollinger Bands Strategy Profit Taking and Martingale DoublingPine Script · Martingale
- MACD KDJ Combined Martingale Pyramiding Quantitative Trading StrategyPine Script · Martingale · 1h
- Modified Bollinger Bands Strategy Take Profit and Martingale DoublingPine Script · Martingale
- Multiple Indicator Quantitative Trading StrategyPine Script · Martingale · 1h
- RSI Quantitative Trading StrategyPine Script · Martingale · 1h
- blackcat L1 MartinGale Scalping StrategyPine Script · Martingale