Strategy vault / Trend following
Advanced Flexible Multi Period Moving Average Crossover Strategy
This strategy is an advanced quantitative trading system based on multiple moving averages and time periods. It allows traders to flexibly choose different types of moving averages (including SMA, EMA, WMA, HMA, and…
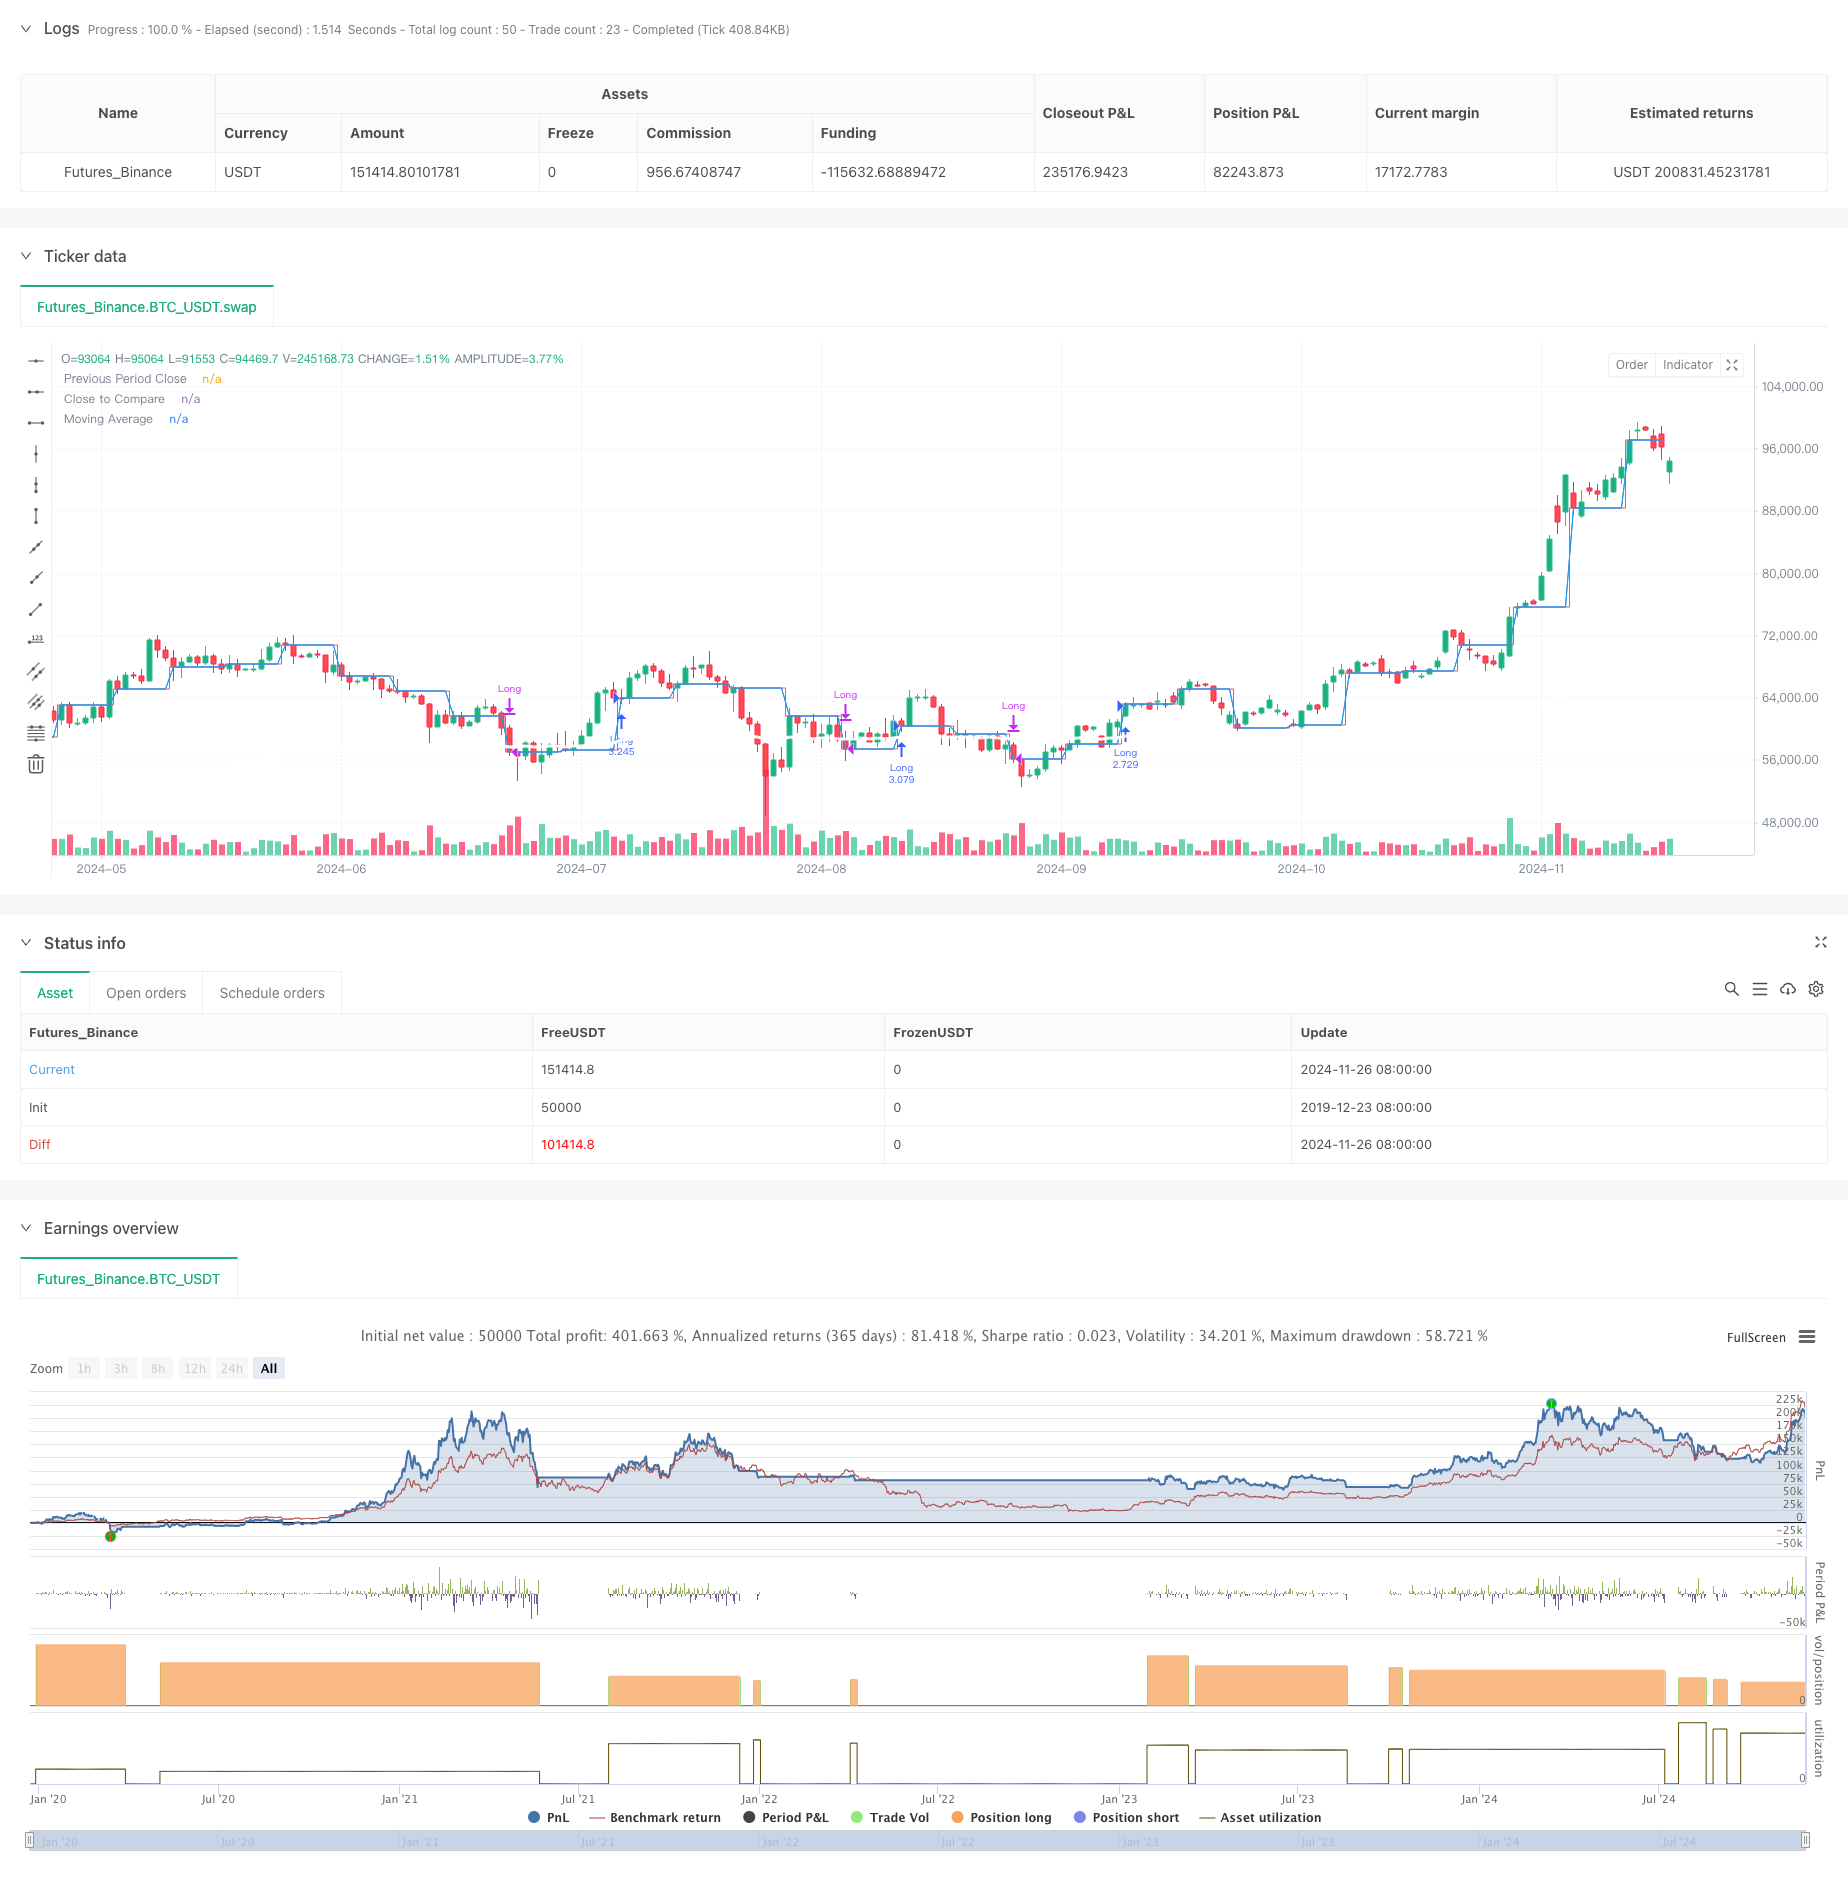
Overview
This strategy is an advanced quantitative trading system based on multiple moving averages and time periods. It allows traders to flexibly choose different types of moving averages (including SMA, EMA, WMA, HMA, and SMMA) and switch between multiple time periods such as daily, weekly, or monthly timeframes according to market conditions. The core logic determines buy and sell signals by comparing the closing price with the selected moving average position, while combining different time period reviews to improve trading accuracy.
Strategy Principles
The strategy employs a modular design with four core components: moving average type selection module, time period selection module, signal generation module, and position management module. When the closing price crosses above the selected moving average, the system generates a long signal at the beginning of the next trading period; when the closing price crosses below the moving average, the system generates a closing signal. The strategy implements cross-period data calculation through the request.security function, ensuring signal accuracy across different time frames. Additionally, the strategy includes automatic position closing at the end of backtesting to ensure capital safety.
Strategy Advantages
- High Flexibility: Supports combinations of multiple moving average types and time periods, adapting to different market environments
- Comprehensive Risk Control: Prevents missed opportunities through end-of-period automatic checking mechanism
- Rational Capital Management: Employs position percentage management for effective risk control
- Strong Signal Stability: Reduces false signals through multiple confirmation mechanisms
- Wide Adaptability: Applicable to various trading instruments and market environments
Strategy Risks
- Lag Risk: Moving average indicators inherently have some lag, potentially causing delayed entry and exit timing
- Oscillation Risk: May generate frequent false breakout signals in sideways markets
- Cross-Period Risk: Signals from different time periods may contradict each other, requiring effective signal prioritization
- Capital Management Risk: Fixed percentage positions may be too aggressive under certain market conditions
Strategy Optimization Directions
- Incorporate Volatility Indicators: Suggested addition of ATR or Bollinger Bands for dynamic position sizing
- Add Trend Filters: Can add long-period trend judgment mechanisms to only open positions in the main trend direction
- Optimize Signal Confirmation: Consider introducing volume and other auxiliary indicators to improve signal reliability
- Improve Stop-Loss Mechanism: Suggested addition of trailing stop-loss functionality for better profit protection
- Add Market Sentiment Indicators: Suggested introduction of RSI or MACD to judge market overbought/oversold conditions
Summary
This strategy is a well-designed trading system with clear logic, providing traders with a reliable trading tool through flexible parameter settings and multiple confirmation mechanisms. The strategy's modular design gives it strong scalability, and its performance can be further enhanced through continuous optimization. It is recommended that traders fully test various parameter combinations in a backtesting environment before live trading to find the most suitable strategy configuration for their needs.
Source Pine Script
/*backtest
start: 2019-12-23 08:00:00
end: 2024-11-27 00:00:00
period: 1d
basePeriod: 1d
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("Flexible Moving Average Strategy", overlay=true, initial_capital=10000, default_qty_type=strategy.percent_of_equity, default_qty_value=100)

// Input to select the review frequency (Daily, Weekly, Monthly)
check_frequency = input.string("Weekly", title="Review Frequency", options=["Daily", "Weekly", "Monthly"])

// Input to select the Moving Average method (SMA, EMA, WMA, HMA, SMMA)
ma_method = input.string("EMA", title="Moving Average Method", options=["SMA", "EMA", "WMA", "HMA", "SMMA"])

// Input to select the length of the Moving Average
ma_length = input.int(30, title="Moving Average Length", minval=1)

// Input to select the timeframe for Moving Average calculation
ma_timeframe = input.string("W", title="Moving Average Timeframe", options=["D", "W", "M"])

// Calculate all Moving Averages on the selected timeframe
sma_value = request.security(syminfo.tickerid, ma_timeframe, ta.sma(close, ma_length), lookahead=barmerge.lookahead_off)
ema_value = request.security(syminfo.tickerid, ma_timeframe, ta.ema(close, ma_length), lookahead=barmerge.lookahead_off)
wma_value = request.security(syminfo.tickerid, ma_timeframe, ta.wma(close, ma_length), lookahead=barmerge.lookahead_off)
hma_value = request.security(syminfo.tickerid, ma_timeframe, ta.hma(close, ma_length), lookahead=barmerge.lookahead_off)
smma_value = request.security(syminfo.tickerid, ma_timeframe, ta.rma(close, ma_length), lookahead=barmerge.lookahead_off) // Smoothed Moving Average (SMMA)

// Select the appropriate Moving Average based on user input
ma = ma_method == "SMA" ? sma_value :
     ma_method == "EMA" ? ema_value :
     ma_method == "WMA" ? wma_value :
     ma_method == "HMA" ? hma_value :
     smma_value  // Default to SMMA

// Variable initialization
var float previous_close = na
var float previous_ma = na
var float close_to_compare = na
var float ma_to_compare = na

// Detect the end of the period (Daily, Weekly, or Monthly) based on the selected frequency
var bool is_period_end = false

if check_frequency == "Daily"
    is_period_end := ta.change(time('D')) != 0
else if check_frequency == "Weekly"
    is_period_end := ta.change(time('W')) != 0
else if check_frequency == "Monthly"
    is_period_end := ta.change(time('M')) != 0

// Store the close and Moving Average values at the end of the period
if is_period_end
    previous_close := close[0]  // Closing price of the last day of the period
    previous_ma := ma[0]  // Moving Average value at the end of the period

// Strategy logic
is_period_start = is_period_end

// Check if this is the first bar of the backtest
is_first_bar = barstate.isfirst

if (is_period_start or is_first_bar)
    // If the previous period values are not available, use current values
    close_to_compare := not na(previous_close) ? previous_close : close[0]
    ma_to_compare := not na(previous_ma) ? previous_ma : ma[0]

    if close_to_compare < ma_to_compare
        // Close price below the MA -> Sell
        if strategy.position_size > 0
            strategy.close("Long")
    else
        // Close price above the MA -> Buy/Hold
        if strategy.position_size == 0
            strategy.entry("Long", strategy.long)

// Close all positions at the end of the backtest period
if barstate.islastconfirmedhistory
    strategy.close_all(comment="Backtest End")

// Plot the previous period's close price for comparison
plot(previous_close, color=color.red, title="Previous Period Close", style=plot.style_stepline)
plot(close_to_compare, color=color.blue, title="Close to Compare", style=plot.style_line)

// Plot the selected Moving Average
plot(ma, color=color.white, title="Moving Average", style=plot.style_line, linewidth=3)Published by ChaoZhang on the FMZ strategy square · last modified 2024-11-28. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Advanced-Flexible-Multi-Period-Moving-Average-Crossover-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ATR and Moving Average Crossover Hybrid StrategyPine Script · Trend following · 1h
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- Dual Moving Average Crossover Dynamic Position Optimization Strategy with EMA Cross Signal SystemPine Script · Trend following · 1h
- EMA Cross Trend Following Strategy with SMA Stop Loss and Re Entry MechanismPine Script · Trend following · 1h
- EMA and RSI Trend Trading StrategyPine Script · Trend following · 1d
- Adaptive Trend Following StrategyPine Script · Trend following · 4h