Strategy vault / Mean reversion
Advanced Volatility Mean Reversion Trading Strategy Multi Dimensional Quantitative Trading System Based on VIX and Moving Average
This strategy is a quantitative trading system based on the behavior of the Volatility Index (VIX) relative to its 10-day moving average. The strategy utilizes the deviation between VIX and its moving average as…
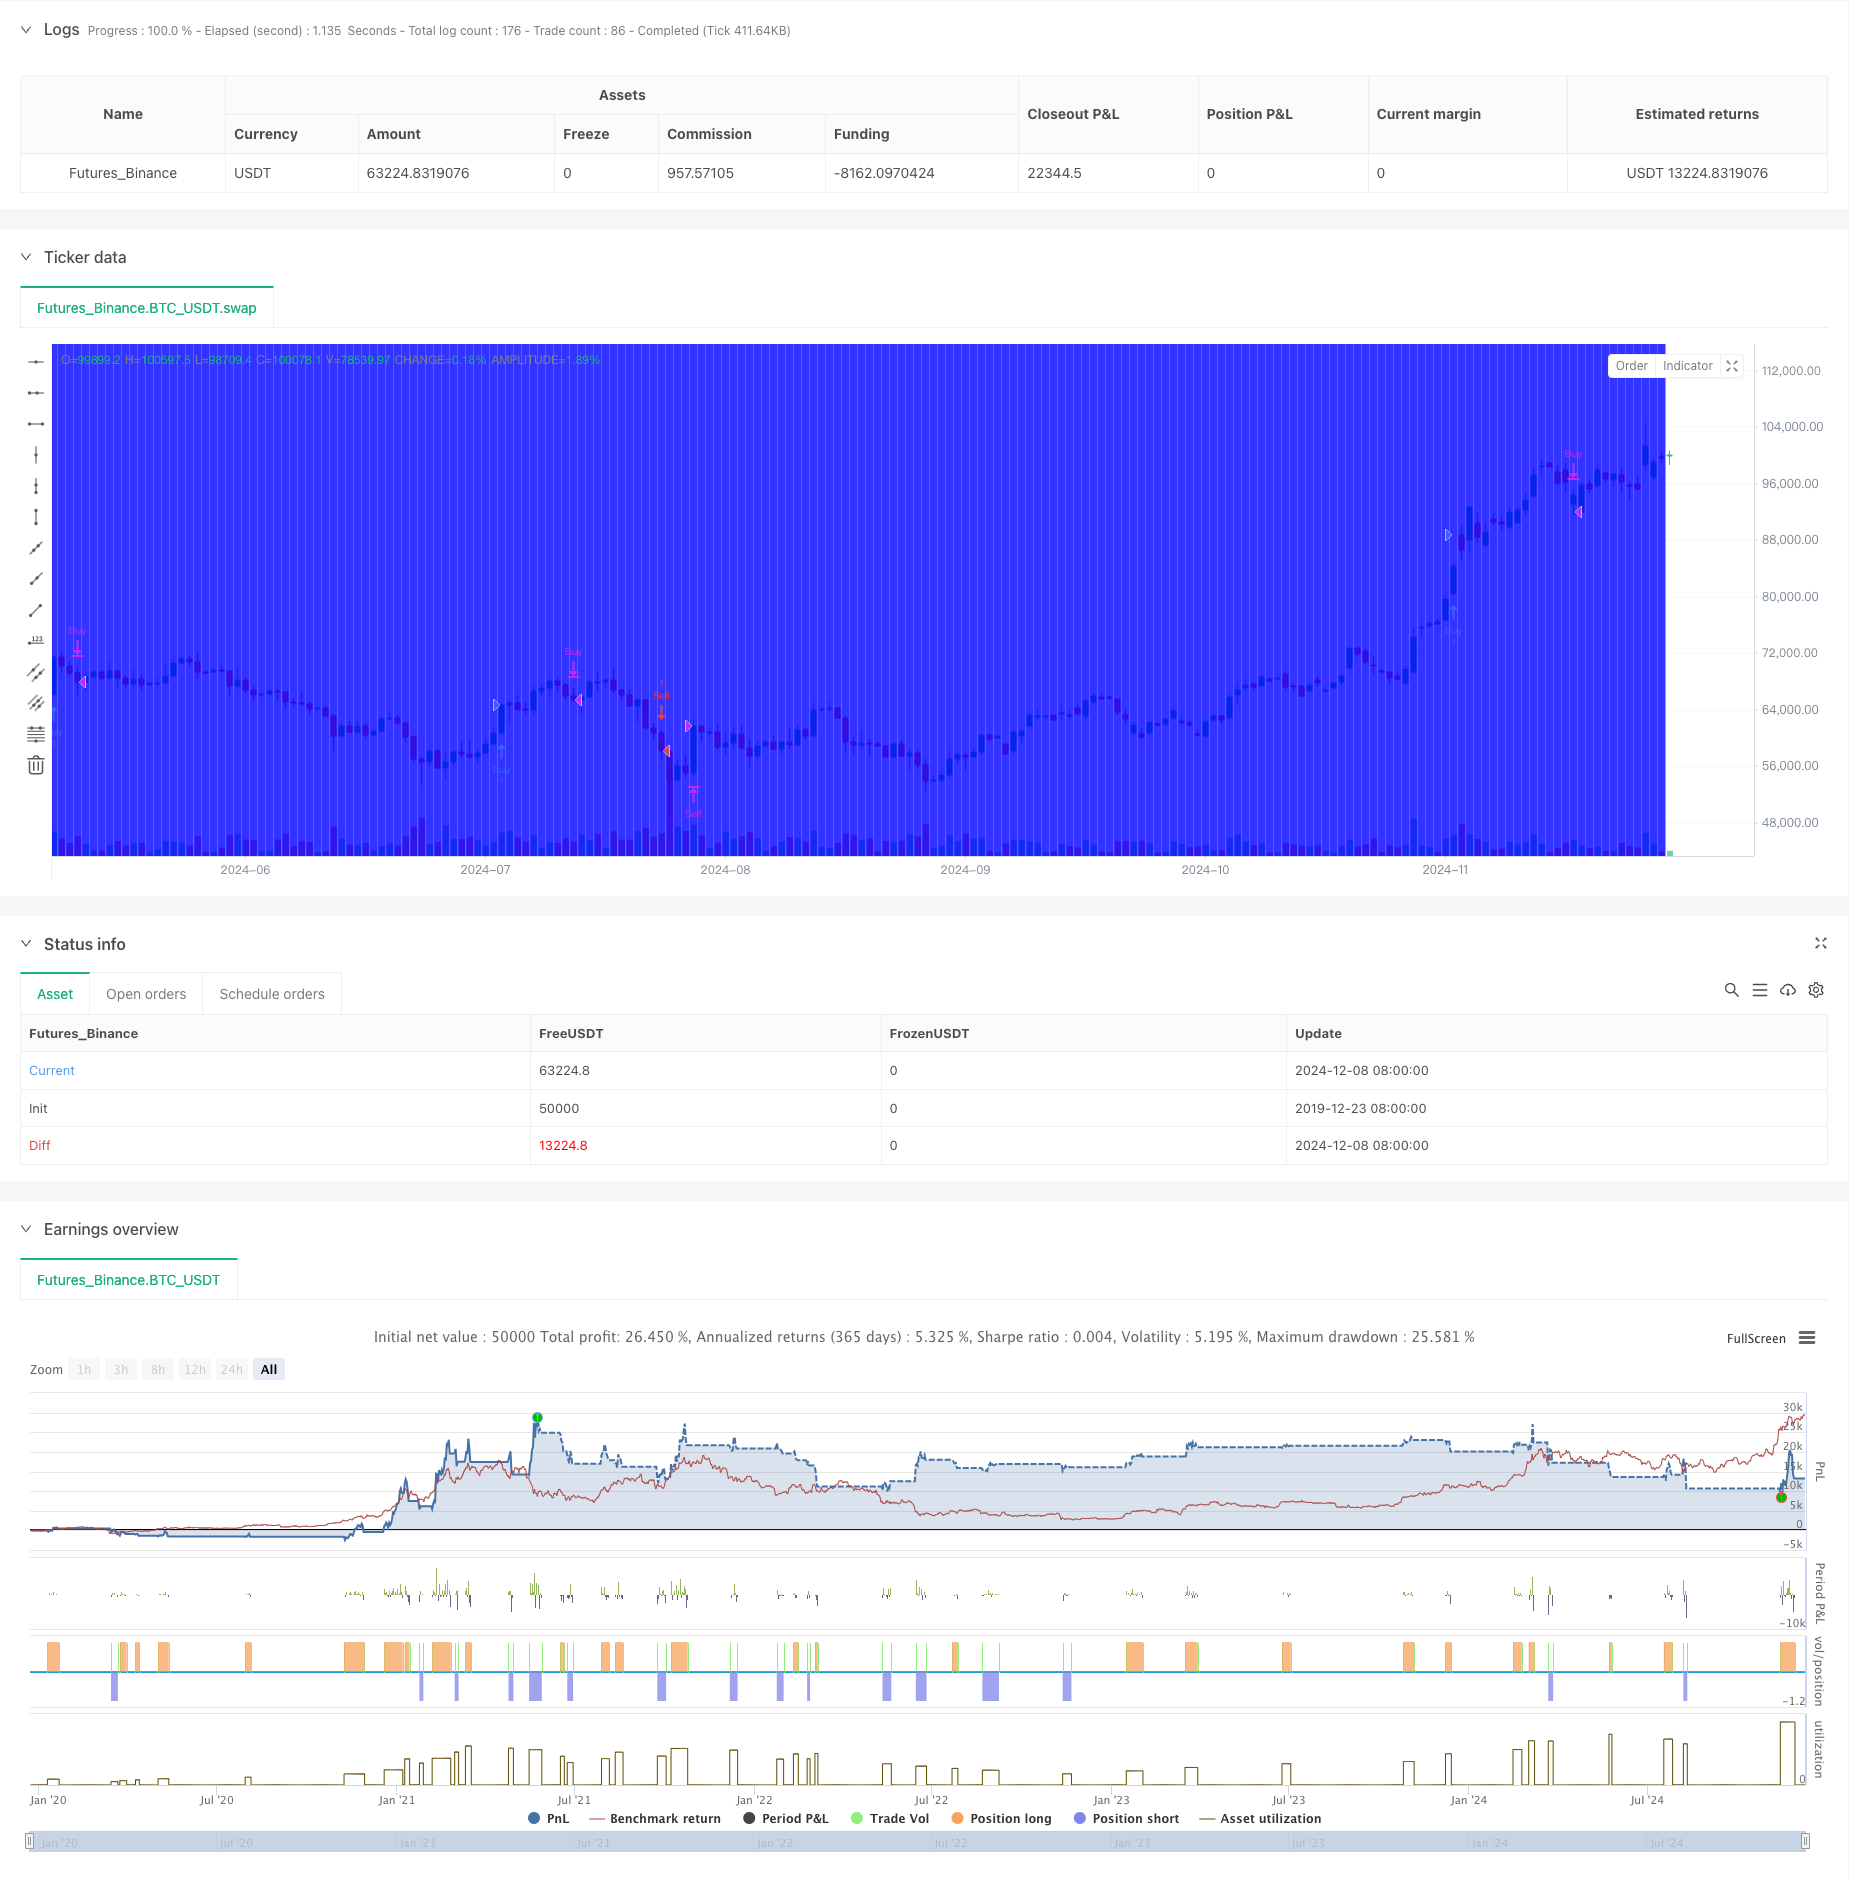
Overview
This strategy is a quantitative trading system based on the behavior of the Volatility Index (VIX) relative to its 10-day moving average. The strategy utilizes the deviation between VIX and its moving average as trading signals, combining technical analysis and statistical arbitrage concepts. The core idea is to capture extreme changes in market sentiment by trading when VIX shows significant deviations and waiting for mean reversion.
Strategy Principles
The strategy employs a bi-directional trading mechanism with both long and short dimensions: Long conditions require VIX's low to be above its 10-day moving average, and the closing price must be at least 10% above the moving average. When both conditions are met, the system generates a buy signal at market close. Short conditions require VIX's high to be below its 10-day moving average, and the closing price must be at least 10% below the moving average. When both conditions are met, the system generates a sell signal at market close. Exit rules are also based on VIX's relationship with the moving average: long positions are closed when VIX trades below the previous day's 10-day moving average intraday; short positions are closed when VIX trades above the previous day's 10-day moving average intraday.
Strategy Advantages
- Clear quantitative indicators: The strategy uses specific numerical indicators and clear trading rules, avoiding subjective judgment.
- Bi-directional trading mechanism: Profits can be made in different market volatility phases, increasing profit opportunities.
- Comprehensive risk control: Clear entry and exit conditions help control risk.
- Reliable technical indicators: Based on VIX, a market-recognized volatility indicator, with good market adaptability.
Strategy Risks
- Market volatility risk: VIX itself measures market volatility, and the strategy may face sudden market swings.
- Overfitting risk: Strategies based on specific conditions may suffer from overfitting issues.
- Mean reversion assumption risk: The mean reversion assumption may fail in trending markets.
- Liquidity risk: May face liquidity shortages and slippage during extreme market volatility.
Strategy Optimization Directions
- Parameter optimization: Optimize moving average periods and deviation thresholds.
- Additional filters: Incorporate other technical indicators to improve signal reliability.
- Dynamic thresholds: Adjust deviation thresholds based on market conditions.
- Risk management optimization: Add stop-loss and money management mechanisms.
Conclusion
This strategy is a mean reversion strategy based on market volatility, using quantitative methods to capture extreme changes in market sentiment. The strategy has clear trading rules and risk control mechanisms but requires attention to how changing market environments affect strategy performance. Through continuous optimization and improvement, this strategy has the potential to maintain stable performance across different market conditions.
Source Pine Script
/*backtest
start: 2019-12-23 08:00:00
end: 2024-12-09 08:00:00
period: 1d
basePeriod: 1d
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This Pine Script™ code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © EdgeTools

//@version=5
strategy("Connors VIX Reversal III invented by Dave Landry", overlay=true)

// Inputs
vixSymbol = input("swap", "VIX Symbol")
lengthMA = input(10, title="Length of Moving Average")
percentThreshold = input(10, title="Percentage Threshold")
buyColor = input(color.rgb(0, 255, 0,90), title="Buy Signal Color")
sellColor = input(color.rgb(255, 0, 0,90), title="Sell Signal Color")
exitColor = input(color.rgb(0, 0, 255,90), title="Exit Signal Color")

// Fetch VIX data
vixClose = request.security(vixSymbol, "D", close)
vixHigh = request.security(vixSymbol, "D", high)
vixLow = request.security(vixSymbol, "D", low)

// Calculate 10-day Moving Average of VIX
vixMA = ta.sma(vixClose, lengthMA)

// Calculate yesterday's 10-day Moving Average
vixMA_yesterday = ta.sma(vixClose[1], lengthMA)

// Buy Rules
buyCondition1 = vixLow > vixMA
buyCondition2 = vixClose > vixMA * (1 + percentThreshold / 100)
buySignal = buyCondition1 and buyCondition2

// Sell Rules
sellCondition1 = vixHigh < vixMA
sellCondition2 = vixClose < vixMA * (1 - percentThreshold / 100)
sellSignal = sellCondition1 and sellCondition2

// Exit Rules
buyExit = vixLow < vixMA_yesterday
sellExit = vixHigh > vixMA_yesterday

// Plot Buy/Sell Signals
bgcolor(buySignal ? buyColor : na)
bgcolor(sellSignal ? sellColor : na)

// Exit Signals
bgcolor(buyExit ? exitColor : na)
bgcolor(sellExit ? exitColor : na)

// Strategy
if (buySignal)
    strategy.entry("Buy", strategy.long)
if (sellSignal)
    strategy.entry("Sell", strategy.short)

if (buyExit)
    strategy.close("Buy")
if (sellExit)
    strategy.close("Sell")
Published by ChaoZhang on the FMZ strategy square · last modified 2024-12-11. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Advanced-Volatility-Mean-Reversion-Trading-Strategy-Multi-Dimensional-Quantitative-Trading-System-Based-on-VIX-and-Moving-Average.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- 3 10 Oscillator Profile Flagging StrategyPine Script · Mean reversion · 1d
- A Trend Reversal Strategy Based on Moving Averages Price Patterns and VolumePine Script · Mean reversion · 1d
- Adaptive Mean Reversion Trading Strategy Based on Chande Momentum OscillatorPine Script · Mean reversion · 1d
- Adaptive Trading Strategy Combining Dynamic Trend Reversal and Stochastic IndicatorPine Script · Mean reversion · 1d
- Advanced 15 Minute Chart Trading Signal StrategyPine Script · Mean reversion · 3h
- Advanced Momentum EMA Trend Following with RSI Overbought Oversold Trading StrategyPine Script · Mean reversion · 1d