Strategy vault / Trend following
ADX Filtered SuperTrend Pivot Trading Strategy
This strategy combines SuperTrend pivot points and the ADX indicator for high-frequency trading. The SuperTrend lines dynamically calculate the latest support and resistance levels to determine price trends and…
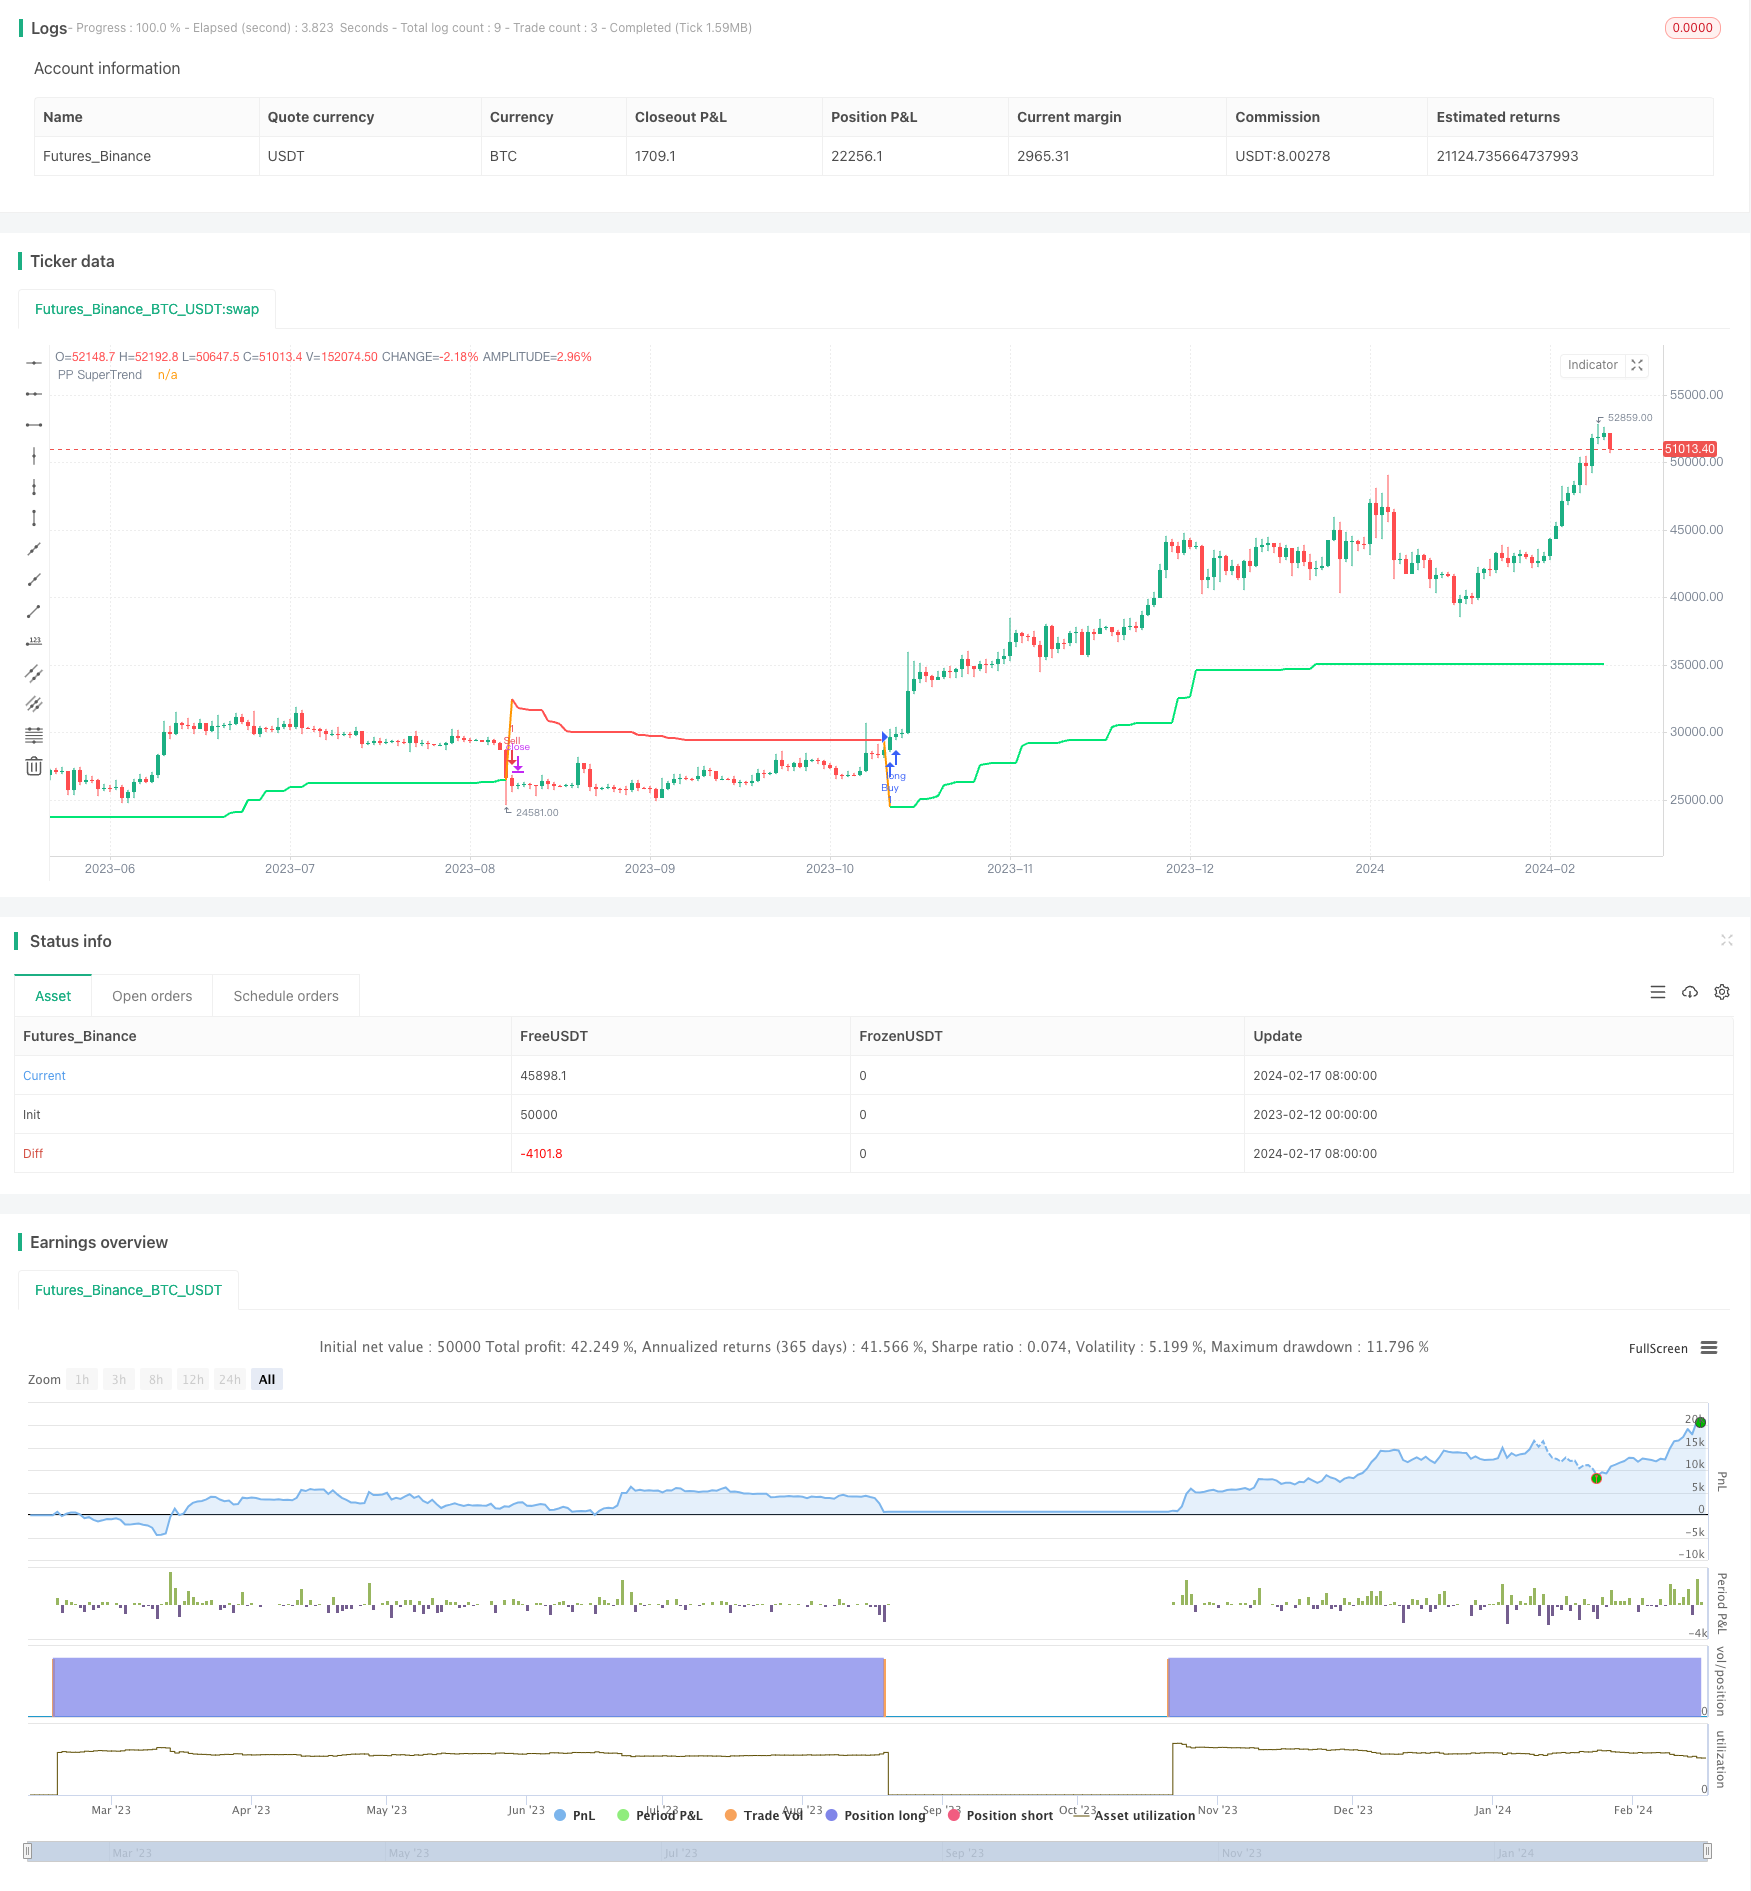
Overview
This strategy combines SuperTrend pivot points and the ADX indicator for high-frequency trading. The SuperTrend lines dynamically calculate the latest support and resistance levels to determine price trends and generate trading signals. The ADX indicator measures trend strength and acts as a filter, only taking trades when the trend is strong enough.
Strategy Logic
Calculate pivot support and resistance lines. Take the closing price and add/subtract an ATR range above and below. Breaks of these lines signal trend reversions.
ADX determines trend strength. High ADX values indicate a strong trend.
Combine both for trade signals. Go long/short only on pivot breaks and high ADX.
Advantage Analysis
Advantages of this strategy:
Dynamic SuperTrend lines quickly identify breakouts.
ADX filter avoids false signals during range-bound markets.
Good risk-reward ratio and drawdown control.
Risk Analysis
Risks of this strategy:
Gap moves can invalidate SuperTrend lines.
Poor ADX threshold setting impacts performance.
High trading frequency increases transaction costs.
Solutions:
Optimize parameters to allow wider breakout ranges.
Test for better ADX values.
Reduce trade frequency.
Optimization Directions
Areas for improvement:
Optimize ATR multiplier for more robust lines.
Test different ADX parameters.
Add stop-loss to limit losses.
Conclusion
This strategy combines the strengths of SuperTrend and ADX to identify high-probability trend reversal points, filtered by ADX for quality. With parameter tuning and mechanisms adjustments, it can become a steady profit-generating high-frequency strategy.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1_close | 0 | EMA Source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_2 | 2 | Pivot Point Period |
| v_input_3 | 5 | ATR Factor |
| v_input_4 | 20 | ATR Period |
| v_input_5_close | 0 | Source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_6 | false | Offset |
Source Pine Script
/*backtest
start: 2023-02-12 00:00:00
end: 2024-02-18 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4
strategy("STPP20 + ADX", overlay = true)

///////////////////////////
// SuperTrend + Pivot Point
//////////////////////////

src =  input(close, title="EMA Source")
PPprd = input(defval = 2, title="Pivot Point Period", minval = 1, maxval = 50)
AtrFactor=input(defval = 5, title = "ATR Factor", minval = 1, step = 0.1)
AtrPd=input(defval = 20, title = "ATR Period", minval=1)

float ph = na
float pl = na
ph := pivothigh(PPprd, PPprd)
pl := pivotlow(PPprd, PPprd)

float center = na
center := center[1]
float lastpp = ph ? ph : pl ? pl : na
if lastpp
    if na(center)
        center := lastpp
    else
        center := (center * 2 + lastpp) / 3

Up = center - (AtrFactor * atr(AtrPd))
Dn = center + (AtrFactor * atr(AtrPd))

float TUp = na
float TDown = na
Trend = 0
TUp := close[1] > TUp[1] ? max(Up, TUp[1]) : Up
TDown := close[1] < TDown[1] ? min(Dn, TDown[1]) : Dn
Trend := close > TDown[1] ? 1: close < TUp[1]? -1: nz(Trend[1], 1)
Trailingsl = Trend == 1 ? TUp : TDown

// Lines
linecolor = Trend == 1 and nz(Trend[1]) == 1 ? color.lime : Trend == -1 and nz(Trend[1]) == -1 ? color.red : na
plot(Trailingsl, color = linecolor ,  linewidth = 2, title = "PP SuperTrend")

bsignalSSPP = close > Trailingsl
ssignalSSPP = close < Trailingsl


///////
// ADX
//////

lenADX = 14
th = 25
TrueRange = max(max(high-low, abs(high-nz(close[1]))), abs(low-nz(close[1])))
DirectionalMovementPlus = high-nz(high[1]) > nz(low[1])-low ? max(high-nz(high[1]), 0): 0
DirectionalMovementMinus = nz(low[1])-low > high-nz(high[1]) ? max(nz(low[1])-low, 0): 0
SmoothedTrueRange = 0.0
SmoothedTrueRange := nz(SmoothedTrueRange[1]) - (nz(SmoothedTrueRange[1])/lenADX) + TrueRange
SmoothedDirectionalMovementPlus = 0.0
SmoothedDirectionalMovementPlus := nz(SmoothedDirectionalMovementPlus[1]) - (nz(SmoothedDirectionalMovementPlus[1])/lenADX) + DirectionalMovementPlus
SmoothedDirectionalMovementMinus = 0.0
SmoothedDirectionalMovementMinus := nz(SmoothedDirectionalMovementMinus[1]) - (nz(SmoothedDirectionalMovementMinus[1])/lenADX) + DirectionalMovementMinus
DIPlus = SmoothedDirectionalMovementPlus / SmoothedTrueRange * 100
DIMinus = SmoothedDirectionalMovementMinus / SmoothedTrueRange * 100
DX = abs(DIPlus-DIMinus) / (DIPlus+DIMinus)*100
ADX = sma(DX, lenADX)


//////
// MA
/////

lenMA = 21
srcMA = input(close, title="Source")
offsetMA = input(title="Offset", type=input.integer, defval=0, minval=-500, maxval=500)
outMA = sma(srcMA, lenMA)


// Buy - Sell Entries
buy = bsignalSSPP and outMA < close and ADX > th
sell = ssignalSSPP

if (buy)
    // .order // Tuned version
    strategy.entry("Buy", strategy.long)


if (sell) and (strategy.position_size > 0)
strategy.order("Sell", false, when = sell)Published by ChaoZhang on the FMZ strategy square · last modified 2024-02-19. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/ADX-Filtered-SuperTrend-Pivot-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Multi Indicator Dynamic Trend Following Strategy Based on EMA and SMAPine Script · Trend following · 1d
- Trend Tracking and Short term Trading Strategy Based on ADX IndicatorPine Script · Trend following · 1d
- Trend Tracking Trailing Stop StrategyPine Script · Trend following · 1d
- Trend Following Short term Trading StrategyPine Script · Trend following · 1h
- Multi Factor Trend Price Action Strategy with Dynamic Risk Management SystemPine Script · Trend following · 2h
- Trend Following Strategy Based on PMax IndicatorPine Script · Trend following · 5m