ADX Momentum Trend Strategy
This strategy uses the ADX indicator to determine the market trend, combines with the DMI indicator to determine direction, utilizes the ADX slope to gauge trend strength, sets the ADX key level to filter…
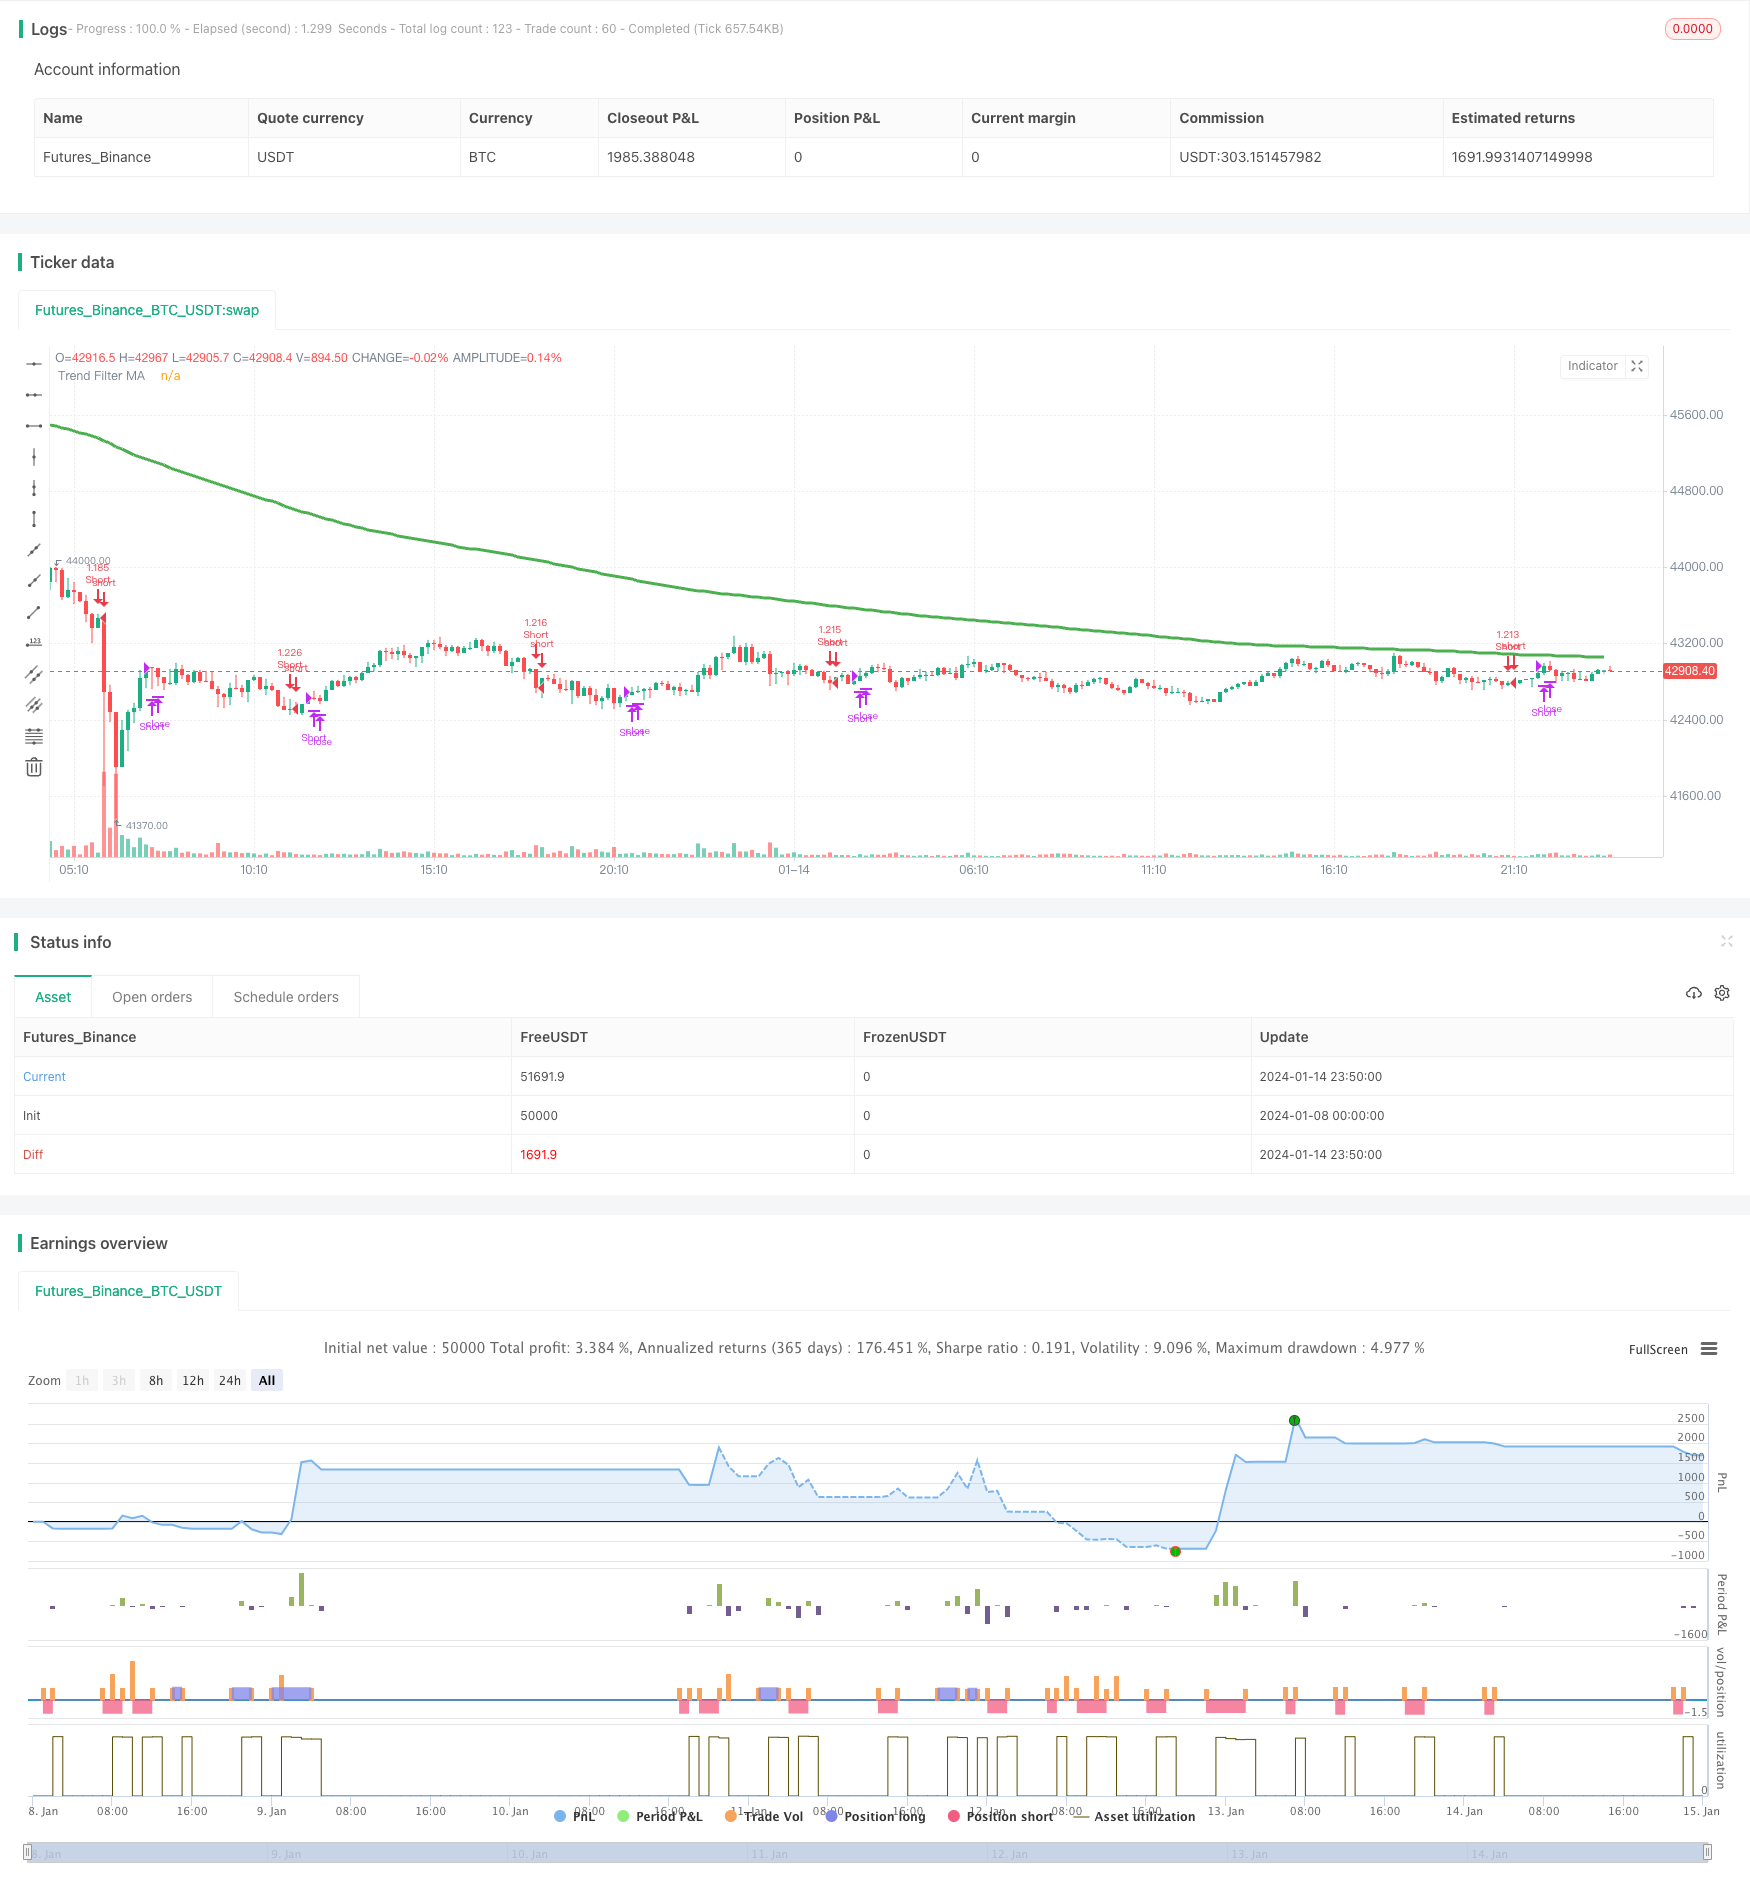
Overview
This strategy uses the ADX indicator to determine the market trend, combines with the DMI indicator to determine direction, utilizes the ADX slope to gauge trend strength, sets the ADX key level to filter non-trending markets, and uses a moving average to filter trade signals.
Strategy Logic
- Calculate the ADX, DI+, and DI- indicators.
- ADX slope > 0 indicates an increasing trend; key level is set to 23 to filter non-trending markets.
- DI+ above DI- signifies bullish momentum overrides bearish momentum, giving a buy signal.
- When moving average filter is enabled, only generate buy signals when close is above the moving average.
- Close positions when ADX slope < 0, indicating fading trend.
Advantage Analysis
- MA filter reduces noise trades in non-trending markets.
- ADX slope accurately determines trend strength.
- DI indicates direction combined with ADX for strength forms a robust trend trading system.
- Expect lower drawdown and higher profit factor than simple MA strategies.
Risk Analysis
- ADX results vary significantly with different input parameters.
- DMI may give false signals before direction is clearly determined.
- Some lag exists, reducing strategy efficiency.
Optimization Directions
- Optimize ADX parameters for best results.
- Add stop loss to limit loss on single trades.
- Try combining other indicators to filter signals, e.g. RSI, Bollinger Bands.
Summary
This strategy fully utilizes ADX's strength in determining trend and momentum, combined with DMI for direction analysis, forming a complete trend following system. The MA filter effectively reduces noise. Further parameter tuning and indicator combinations may improve robustness and efficiency. In summary, by incorporating trend, momentum and direction analysis, this strategy has the potential to achieve strong returns.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 2019 | From Year |
| v_input_2 | true | From Month |
| v_input_3 | true | From Day |
| v_input_4 | 9999 | To Year |
| v_input_5 | true | To Month |
| v_input_6 | true | To Day |
| v_input_7 | 14 | ADX Smoothing |
| v_input_8 | 14 | DI Period |
| v_input_9 | 23 | Keylevel for ADX |
| v_input_10 | 3 | Lookback Period for Slope |
| v_input_11 | true | Use MA for Filtering? |
| v_input_12 | 0 | MA Type For Filtering: EMA | SMA |
| v_input_13 | 200 | MA Period for Filtering |
Source Pine Script
/*backtest
start: 2024-01-08 00:00:00
end: 2024-01-15 00:00:00
period: 10m
basePeriod: 1m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4
// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © millerrh with inspiration from @9e52f12edd034d28bdd5544e7ff92e
//The intent behind this study is to look at ADX when it has an increasing slope and is above a user-defined key level (23 default).
//This is to identify when it is trending.
//It then looks at the DMI levels.  If D+ is above D- and the ADX is sloping upwards and above the key level, it triggers a buy condition.  Opposite for short.
//Can use a user-defined moving average to filter long/short if desried.
// NOTE: THIS IS MEANT TO BE USED IN CONJUNCTION WITH MY "ATX TRIGGER" INDICATOR FOR VISUALIZATION. MAKE SURE SETTINGS ARE THE SAME FOR BOTH.

strategy("ADX | DMI Trend", overlay=true, initial_capital=10000, currency='USD',
   default_qty_type=strategy.percent_of_equity, default_qty_value=100, commission_type=strategy.commission.percent, commission_value=0.04)

// === BACKTEST RANGE ===
From_Year  = input(defval = 2019, title = "From Year")
From_Month = input(defval = 1, title = "From Month", minval = 1, maxval = 12)
From_Day   = input(defval = 1, title = "From Day", minval = 1, maxval = 31)
To_Year    = input(defval = 9999, title = "To Year")
To_Month   = input(defval = 1, title = "To Month", minval = 1, maxval = 12)
To_Day     = input(defval = 1, title = "To Day", minval = 1, maxval = 31)
Start  = timestamp(From_Year, From_Month, From_Day, 00, 00)  // backtest start window
Finish = timestamp(To_Year, To_Month, To_Day, 23, 59)        // backtest finish window

// == INPUTS ==
// ADX Info
adxlen = input(14, title="ADX Smoothing")
dilen = input(14, title="DI Period")
keyLevel = input(23, title="Keylevel for ADX")
adxLookback = input(3, title="Lookback Period for Slope")

// == FILTERING ==
// Inputs
useMaFilter = input(title = "Use MA for Filtering?", type = input.bool, defval = true)
maType = input(defval="EMA", options=["EMA", "SMA"], title = "MA Type For Filtering")
maLength   = input(defval = 200, title = "MA Period for Filtering", minval = 1)

// Declare function to be able to swap out EMA/SMA
ma(maType, src, length) =>
    maType == "EMA" ? ema(src, length) : sma(src, length) //Ternary Operator (if maType equals EMA, then do ema calc, else do sma calc)
maFilter = ma(maType, close, maLength)
plot(maFilter, title = "Trend Filter MA", color = color.green, linewidth = 3, style = plot.style_line, transp = 50)

// Check to see if the useMaFilter check box is checked, this then inputs this conditional "maFilterCheck" variable into the strategy entry
maFilterCheck = if useMaFilter == true
    maFilter
else
    close

// == USE BUILT-IN DMI FUNCTION TO DETERMINE ADX AND BULL/BEAR STRENGTH
[diplus, diminus, adx] = dmi(dilen, adxlen)

buySignal = (adx[0]-adx[adxLookback] > 0) and adx > keyLevel and diplus > diminus  and close >= maFilterCheck
// buySignalValue = valuewhen(buySignal, close, 0)
shortSignal = (adx[0]-adx[adxLookback] > 0) and adx > keyLevel and diplus < diminus  and close <= maFilterCheck
// shortSignalValue = valuewhen(shortSignal, close, 0)
sellCoverSignal = adx[0]-adx[adxLookback] < 0

// == ENTRY & EXIT CRITERIA
// Triggers to be TRUE for it to fire of the BUY Signal : (opposite for the SELL signal).
// (1): Price is over the 200 EMA line. (EMA level configurable by the user)
// (2): "D+" is OVER the "D-" line
// (3): RSI 7 is under 30 (for SELL, RSI 7 is over 70)
// 1* = The ultimate is to have a combination line of 3 EMA values, EMA 14, EMA 50 and EMA 200 - And if price is over this "combo" line, then it's a strong signal

// == STRATEGY ENTRIES/EXITS ==
strategy.entry("Long", strategy.long, when = buySignal)
strategy.close("Long", when = sellCoverSignal)
strategy.entry("Short", strategy.short, when = shortSignal)
strategy.close("Short", when = sellCoverSignal)

// == ALERTS ==
// alertcondition(buySignal, title='ADX Trigger Buy', message='ADX Trigger Buy')
// alertcondition(sellSignal, title='ADX Trigger Sell', message='ADX Trigger Sell')Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-16. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/ADX-Momentum-Trend-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Momentum Trading Strategy Based on Multi factor ModelPine Script · Momentum · 1d
- Multi Indicator Comprehensive Analysis Quantitative Trading Strategy Trend Momentum and Volatility Collaborative Prediction ModelPine Script · Momentum · 3m
- Multi Indicator Dynamic Stop Loss Momentum Trend Trading StrategyPine Script · Momentum · 1h
- Advanced Multi Indicator Trend Following and Momentum Quantitative Trading StrategyPine Script · Momentum · 1h
- Bollinger Bands Momentum Trend Following Quantitative StrategyPine Script · Momentum · 1d
- Four factor Momentum Tracking Trading Strategy Based on ADX BB B AO and EMAPine Script · Momentum · 1d