Strategy vault / Trend following
Alligator Long Term Trend Following Trading Strategy
The Alligator Long-Term Trend Following Trading Strategy is a quantitative trading strategy based on the Williams Alligator indicator. The strategy utilizes a combination of moving averages with different periods to…
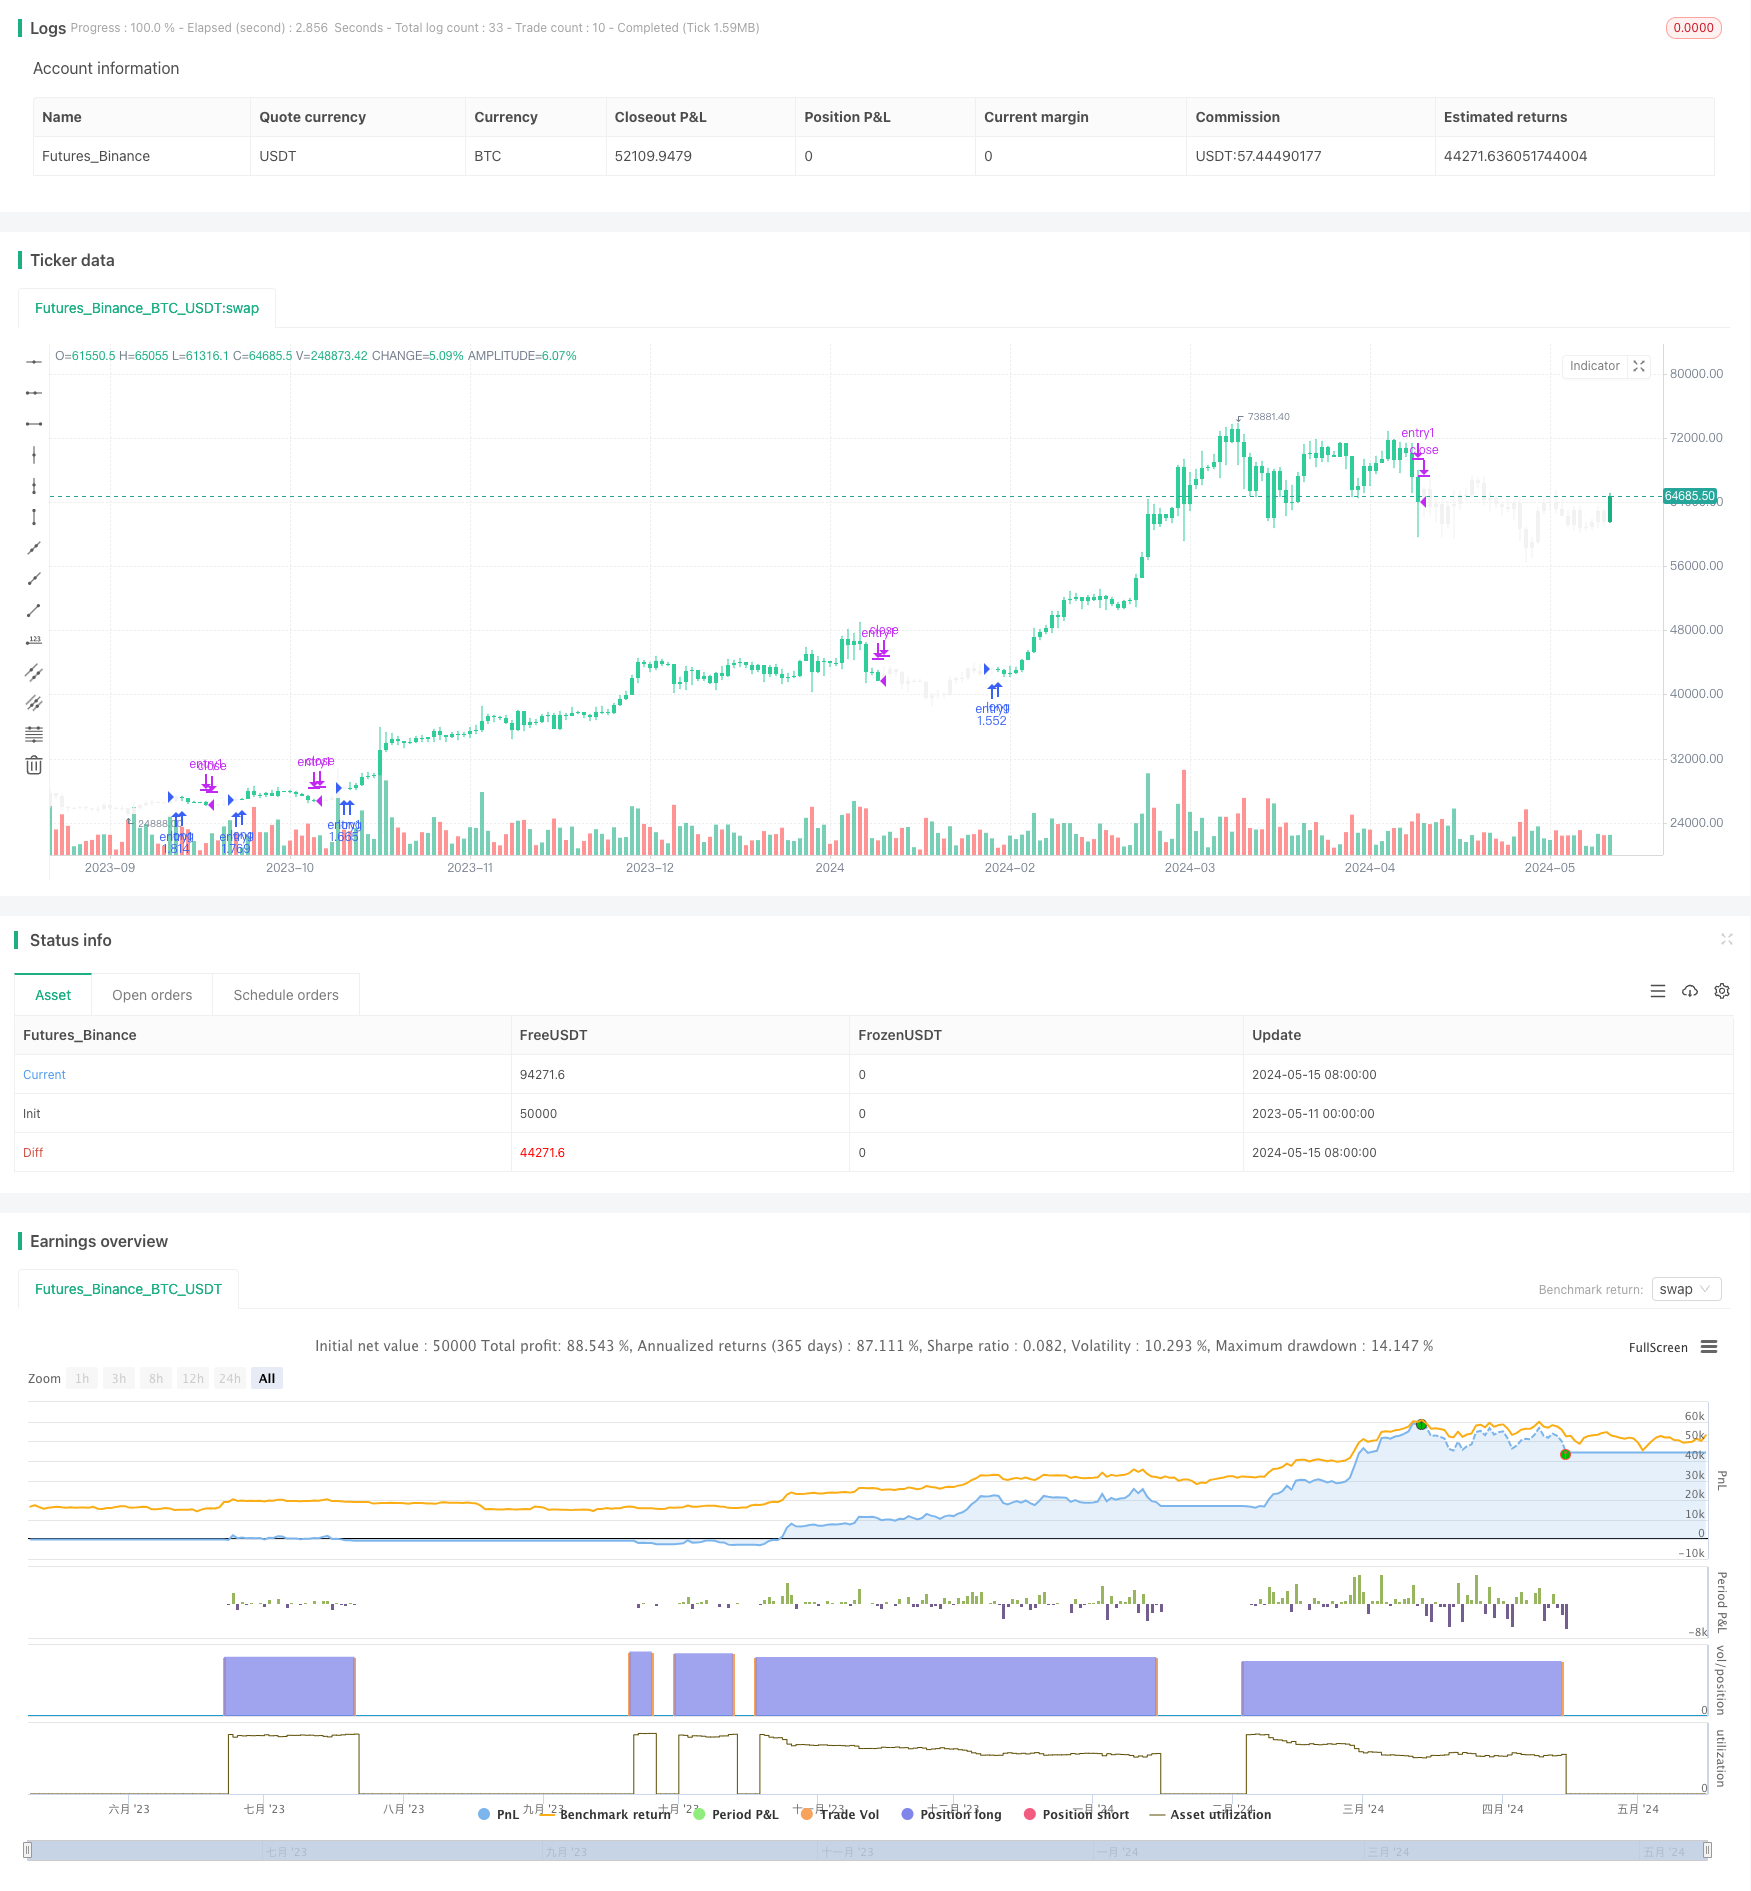
Overview
The Alligator Long-Term Trend Following Trading Strategy is a quantitative trading strategy based on the Williams Alligator indicator. The strategy utilizes a combination of moving averages with different periods to capture the main trends in the market, suitable for medium to long-term trend following trades. The main idea of the strategy is to determine the direction and strength of the trend by the opening direction of the Alligator indicator and the relative position of the price to the Alligator indicator, and make trading decisions accordingly.
Strategy Principles
The Alligator Long-Term Trend Following Trading Strategy uses three moving averages with different periods to construct the Alligator indicator, namely:
- Jaw line: 13-period SMMA, shifted 8 bars into the future
- Teeth line: 8-period SMMA, shifted 5 bars into the future
- Lips line: 5-period SMMA, shifted 3 bars into the future
When the Alligator indicator's mouth opens upward, i.e., the Jaw line is at the bottom, the Teeth line is in the middle, and the Lips line is at the top, and the price is above the Alligator indicator, the strategy will open a long position. This situation indicates that an upward trend wave has been confirmed, and we want to hold the position until the trend ends.
When the price breaks below the Jaw line, the strategy will close the long position. This ensures that we will not continue to hold positions in a bear market.
Strategy Advantages
- Suitable for medium to long-term trading: The strategy is based on the Alligator indicator, which can effectively capture the main trends in the market, making it very suitable for medium to long-term trend following trades.
- Low trading frequency: The strategy only opens positions when a trend is confirmed and closes positions when the trend ends, resulting in a relatively low trading frequency, which can effectively reduce trading costs.
- Wide range of applications: The strategy can be applied to various financial markets, such as forex, cryptocurrencies, etc., with strong adaptability and flexibility.
- No need for parameter optimization: The strategy completely follows market trends and does not require parameter optimization, making it simple and easy to use.
Strategy Risks
- Potential slippage risk: In cases of severe market fluctuations or insufficient liquidity, trading orders may not be executed at the expected price, leading to slippage risk.
- Lack of fixed risk management: The strategy does not have fixed risk management settings, and the position size of each trade needs to be adjusted according to one's risk preference.
- Possible missed short-term opportunities: As the strategy focuses on capturing medium to long-term trends, it may miss some short-term trading opportunities.
Strategy Optimization Directions
- Add risk management module: Consider adding some risk management measures, such as stop-loss, dynamic position adjustment, etc., to better control risks.
- Combine with other technical indicators: Try combining the Alligator indicator with other technical indicators, such as RSI, MACD, etc., to improve the accuracy and reliability of the strategy.
- Optimize parameter settings: Although the strategy does not require parameter optimization, you can try backtesting different time periods and trading targets to find the optimal parameter combination.
Summary
The Alligator Long-Term Trend Following Trading Strategy is a simple, easy-to-use, and widely applicable quantitative trading strategy. By utilizing the Alligator indicator to capture the main trends in the market, the strategy can achieve stable returns over the medium to long term. Although the strategy has some potential risks, by adding risk management modules, combining with other technical indicators, and optimizing parameter settings, the strategy's performance and stability can be further improved. For investors who prefer medium to long-term trend following trades, the Alligator Long-Term Trend Following Trading Strategy is a choice worth considering.
Source Pine Script
/*backtest
start: 2023-05-11 00:00:00
end: 2024-05-16 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//_______ <licence>
// This Pine Script™ code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © Skyrex

//_______ <version>
//@version=5

//_______ <declaration_statement>
strategy(title = "Alligator Long Term Trend Following Strategy [Skyrex.io]",
         shorttitle = "Alligator Strategy [Skyrex.io]",
         overlay = true,
         format = format.inherit,
         pyramiding = 1,
         calc_on_order_fills = false,
         calc_on_every_tick = true,
         default_qty_type = strategy.percent_of_equity,
         default_qty_value = 100,
         initial_capital = 10000,
         currency = currency.NONE,
         commission_type = strategy.commission.percent,
         commission_value = 0.1,
         slippage = 5)


//_______ <constant_declarations>
var color skyrexGreen = color.new(#2ECD99, 0)
var color skyrexGray = color.new(#F2F2F2, 0)
var color skyrexWhite = color.new(#FFFFFF, 0)

var color barcolor = na


//_______ <inputs>
// Trading bot settings
sourceUuid = input.string(title = "sourceUuid:", defval = "yourBotSourceUuid", group = "Trading Bot Settings")
secretToken = input.string(title = "secretToken:", defval = "yourBotSecretToken", group = "Trading Bot Settings")

// Trading Period Settings
lookBackPeriodStart = input(title = "Trade Start Date/Time", defval = timestamp('2023-01-01T00:00:00'), group = "Trading Period Settings")
lookBackPeriodStop = input(title = "Trade Stop Date/Time", defval = timestamp('2025-01-01T00:00:00'), group = "Trading Period Settings")

//_______ <function_declarations>
//@function       Used to calculate Simple moving average for Alligator
//@param src      Sourse for smma Calculations
//@param length   Number of bars to calculate smma
//@returns        The calculated smma value
smma(src, length) =>
    smma =  0.0
    smma := na(smma[1]) ? ta.sma(src, length) : (smma[1] * (length - 1) + src) / length
    smma


//@function       Used to decide if current candle above the Alligator
//@param jaw      Jaw line of an Alligator
//@param teeth    Teeth line of an Alligator
//@param lips     Lips line of an Alligator
//@returns        Bool value
is_LowAboveAlligator(jaw, teeth, lips) =>
    result = low > jaw and low > lips and low > teeth
    result


//@function       Used to decide if current candle below the Alligator
//@param jaw      Jaw line of an Alligator
//@param teeth    Teeth line of an Alligator
//@param lips     Lips line of an Alligator
//@returns        Bool value
is_HighBelowAlligator(jaw, teeth, lips) =>
    result = high < jaw and high < lips and high < teeth
    result


//@function       Used to decide if Alligator's mouth is open
//@param jaw      Jaw line of an Alligator
//@param teeth    Teeth line of an Alligator
//@param lips     Lips line of an Alligator
//@returns        Bool value
is_AlligatorHungry(jaw, teeth, lips) =>
    result = lips > jaw[5] and lips > teeth[2] and teeth > jaw[3]
    result


//_______ <calculations>
jaw = smma(hl2, 13)[8]
teeth = smma(hl2, 8)[5]
lips = smma(hl2, 5)[3]


jaw_o = smma(hl2, 13)
teeth_o = smma(hl2, 8)
lips_o = smma(hl2, 5)


//_______ <strategy_calls>
longCondition = is_LowAboveAlligator(jaw, teeth, lips) and is_AlligatorHungry(jaw_o, teeth_o, lips_o)
if (longCondition)
    strategy.entry(id = "entry1", direction = strategy.long, alert_message = '{\n"base": "' + syminfo.basecurrency + '",\n"quote": "' + syminfo.currency + '",\n"position": "entry1",\n"price": "' + str.tostring(close) + '",\n"sourceUuid": "' + sourceUuid + '",\n"secretToken": "' + secretToken + '",\n"timestamp": "' + str.tostring(timenow) + '"\n}')

if close < jaw
    strategy.close(id = "entry1", alert_message = '{\n"base": "' + syminfo.basecurrency + '",\n"quote": "' + syminfo.currency + '",\n"position": "close",\n"price": "' + str.tostring(close) + '",\n"sourceUuid": "' + sourceUuid + '",\n"secretToken": "' + secretToken + '",\n"timestamp": "' + str.tostring(timenow) + '"\n}')


//_______ <visuals>
if strategy.opentrades > 0
    barcolor := skyrexGreen
else
    barcolor := skyrexGray

barcolor(barcolor)
//_______ <alerts>Published by ChaoZhang on the FMZ strategy square · last modified 2024-05-17. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Alligator-Long-Term-Trend-Following-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ADX MA and EMA Long Only Trend Tracking StrategyPine Script · Trend following · 1d
- ATR and Moving Average Crossover Hybrid StrategyPine Script · Trend following · 1h
- Adaptive FVG Detection and MA Trend Trading Strategy with Dynamic ResistancePine Script · Trend following · 1d
- Adaptive Risk Management Strategy Based on Dynamic ATR and Moving Average CrossoverPine Script · Trend following · 2h
- Adaptive Trading Strategy Based on Stochastic RSI Dual Line CrossoverPine Script · Trend following · 4h
- Adaptive Volatility Based Trend Following Short Strategy with Time Delay and Stop Loss ProtectionPine Script · Trend following · 2m