Strategy vault / Mean reversion
Alternating Timeframe Parabolic SAR Strategy
The core idea of this strategy is to use the Parabolic SAR, one of the Momentum Indicators, alternately across different timeframes to capture trend reversals in the market. The strategy monitors Parabolic SAR…
Overview
The core idea of this strategy is to use the Parabolic SAR, one of the Momentum Indicators, alternately across different timeframes to capture trend reversals in the market. The strategy monitors Parabolic SAR signals simultaneously on multiple timeframes, and enters a corresponding long or short position once a SAR signal is triggered on a higher timeframe.
Strategy Logic
Firstly, the strategy calculates Parabolic SAR values separately on different timeframes (15m, D, W, M).
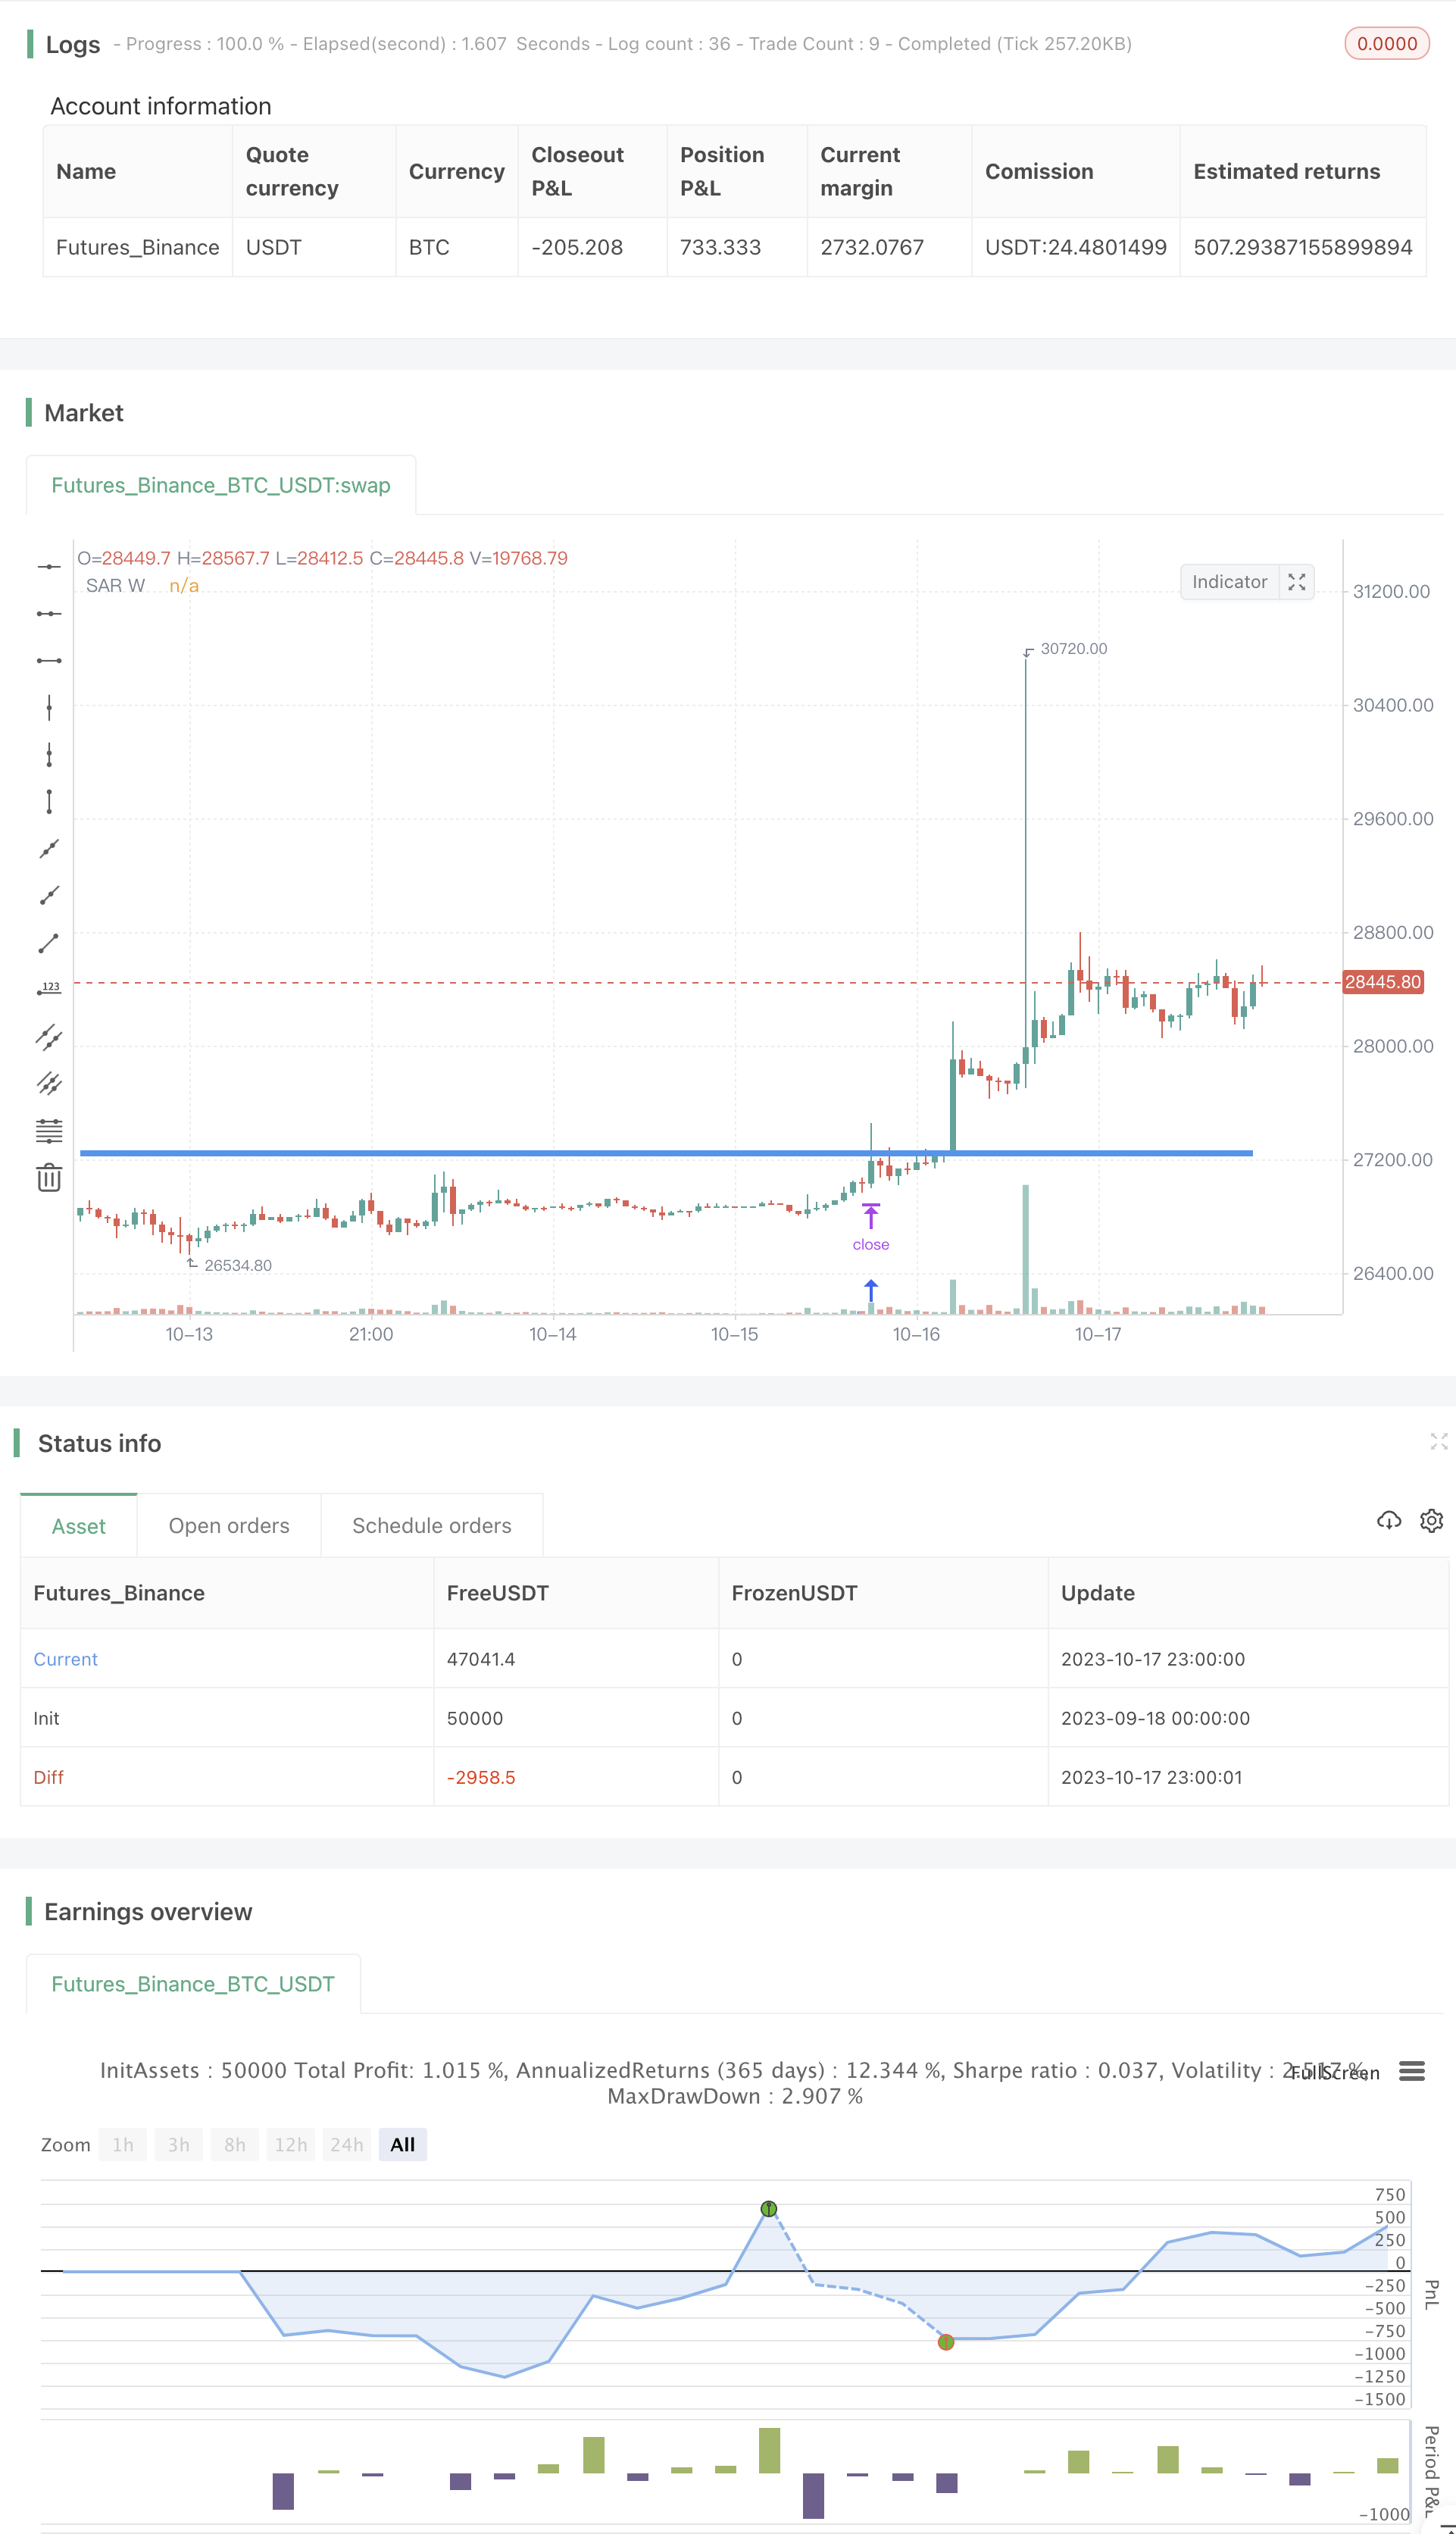
Secondly, the strategy monitors the weekly SAR value. It goes long when the weekly SAR rises above the recent high, and goes short when the weekly SAR falls below the recent low.
Finally, the strategy uses the weekly SAR as the stop loss. Specifically, if already long, the weekly SAR is set as the stop loss for that long position; if already short, the weekly SAR is set as the stop loss for that short position.
This way, the strategy enters based on signals from higher timeframes, and stops out on lower timeframes. Monitoring weekly SAR signals can more accurately identify trend reversals, while stopping out on 15m SAR can realize quick cut losses to avoid excessive drawdowns when reversals come.
Advantage Analysis
This Parabolic SAR alternating timeframe strategy has the following edges:
Utilizes the advantages of SAR on different timeframes. Weekly SAR can accurately identify trend reversals and reduce whipsaw losses; 15m SAR allows quick stop loss management.
High flexibility. SAR parameters can be adjusted for different products and market conditions to optimize strategy performance.
Low trading frequency. Only enters on signals from higher timeframe SAR, avoiding overtrading.
High capital utilization efficiency. Deploys capital only when high probability reversal is identified, avoiding capital sitting idle.
Easy risk control. Adopting fixed stop loss points allows clear calculation of risk exposure for each position.
Risk Analysis
This strategy also has some risks:
Improper SAR parameter setting may lead to stop loss being too wide or too tight, thus impacting strategy performance.
Sharp price spikes may directly penetrate the stop loss level, leading to large losses.
Relying solely on SAR signals may miss other statistically profitable opportunities during trends.
Conflicting signals may arise from SAR on different timeframes. Signal priority needs to be handled.
Improper timeframe selection, too much noise on lower periods or lag in identifying reversals on higher periods, may both impact strategy efficacy.
Optimization Directions
The strategy can be improved in the following aspects:
Optimize SAR parameters to reduce whipsaw occurrences. Multiple backtests can be run to find optimal parameter combinations.
Add stop loss strategies like trailing stop, staggered stop loss etc to further control single trade loss.
Incorporate other indicators like MACD, KDJ to find more evidence for trend reversals, reducing trading errors.
Add capital management strategies like fixed fractional position sizing, fixed risk-reward ratio etc to size each position and control overall strategy risk.
Optimize timeframe combinations by testing strategy performance under different period settings to find best match.
Conclusion
This strategy utilizes Parabolic SAR alternately across timeframes, identifying reversal points on higher periods and stopping out on lower periods, achieving synergistic effect. It effectively reduces whipsaw trades and risk from false breakouts. With further enhancements like parameter optimization, stop loss strategies and capital management, outstanding strategy results can be achieved.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 15 | Resolution |
| v_input_2 | D | Resolution |
| v_input_3 | W | Resolution |
| v_input_4 | M | Resolution |
Source Pine Script
/*backtest
start: 2023-09-18 00:00:00
end: 2023-10-18 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=2
strategy ("SAR alternating timeframe", overlay=true)

//resolution
res1=input("15", title="Resolution")
res2=input("D", title="Resolution")
res3=input("W", title="Resolution")
res4=input("M", title="Resolution")

//output functions
out = sar(0.02,0.02,0.2)

// Security
SAR1 = request.security(syminfo.tickerid, res1, out)
SAR2 = request.security(syminfo.tickerid, res2, out)
SAR3 = request.security(syminfo.tickerid, res3, out)
SAR4 = request.security(syminfo.tickerid, res4, out)

//Plots
//plot(SAR1 , title="SAR 15", color = red, linewidth = 2)
//plot(SAR2 , title="SAR D", color = green, linewidth = 3)
plot(SAR3 , title="SAR W", color =blue, linewidth = 4)
//plot(SAR4 , title="SAR W", color =purple, linewidth = 5))


/////////////////////////////////////////////////////////////////////
//trade
if (SAR3 >= high)
    strategy.entry("ParLE", strategy.long, stop=SAR3, comment="ParLE")
else
    strategy.cancel("ParLE")

if (SAR3 <= low)
    strategy.entry("ParSE", strategy.short, stop=SAR3, comment="ParSE")
else
    strategy.cancel("ParSE")
Published by ChaoZhang on the FMZ strategy square · last modified 2023-10-19. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Alternating-Timeframe-Parabolic-SAR-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Dual Rail Parabolic SAR Bollinger Bands StrategyPine Script · Mean reversion
- Dynamic PSAR Stock Fluctuation Tracking StrategyPine Script · Mean reversion · 10m
- Parabolic SAR Divergence Trading StrategyPine Script · Mean reversion · 1d
- Parabolic SAR Trailing Stop Loss StrategyPine Script · Mean reversion · 3h
- Combining Simple Moving Average and Adaptive Moving Average StrategyPine Script · Mean reversion · 5m
- Multi Dimensional Technical Indicator Cross Confirmation Buy Signal Optimization StrategyPine Script · Mean reversion · 1d