An ATR Channel Breakout Quantitative Trading Strategy
This strategy trades based on channels formed using the Average True Range (ATR). Specifically, it calculates a SMA line over a certain period, then uses the ATR values to determine the upper and lower bands of the…
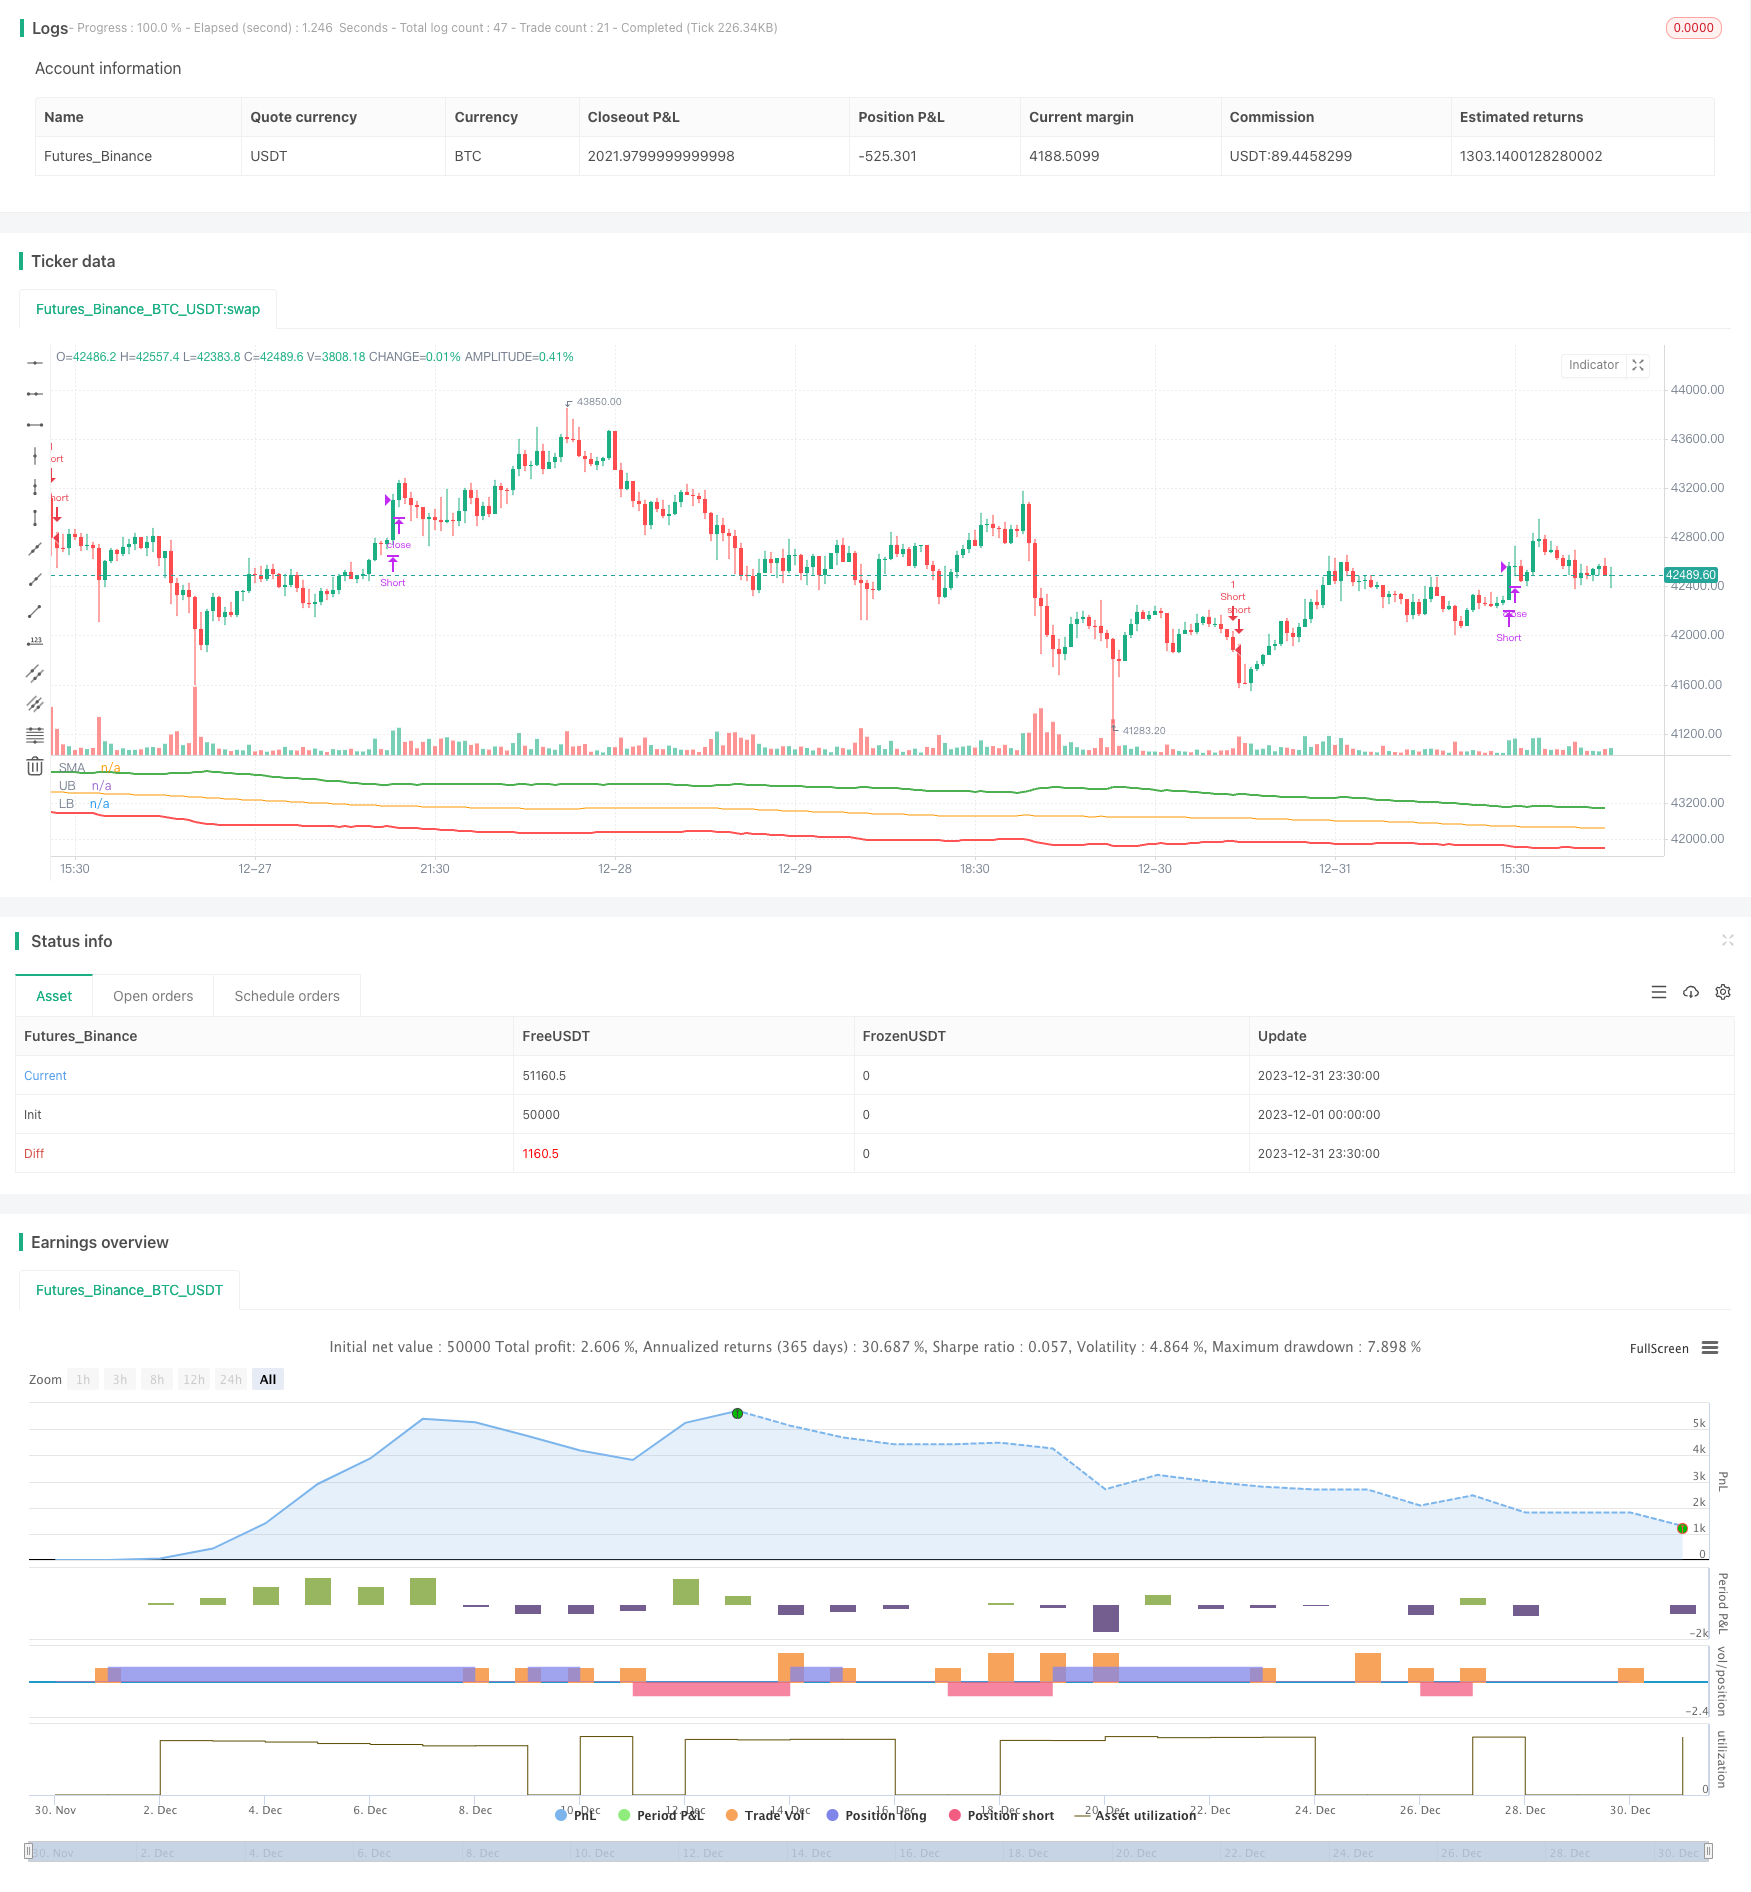
Overview
This strategy trades based on channels formed using the Average True Range (ATR). Specifically, it calculates a SMA line over a certain period, then uses the ATR values to determine the upper and lower bands of the channel. It goes long when the price breaks out above the upper band, and goes short when the price breaks below the lower band. Positions are closed when the price crosses back below the SMA line.
Strategy Logic
The core logic of this strategy is based on ATR channels. The ATR indicator can effectively reflect market volatility and price movements, and is usually used to determine stop loss and take profit levels. The strategy first calculates the SMA line over n periods (default 150), then uses the ATR value and coefficient to determine the upper and lower channel bands. The specific formulas are:
Upper Band = SMA + ATR Value × Upper Band Coefficient (default 4) Lower Band = SMA - ATR Value × Lower Band Coefficient (default 4)
When the price breaks out above the upper band, it indicates the start of a trend channel and upside momentum, so a long position is taken. When the price breaks below the lower band, it signals the start of a reversal, so a short position is taken. Exits occur when the price crosses back below the SMA line, closing out all longs, or crosses back above the SMA line, closing out all shorts.
Advantages
Using ATR as the reference for channel range can more accurately capture market volatility. ATR effectively measures market volatility for better channel sizing.
The dual filters of SMA and ATR channel ensure more reliable trade signals, reducing false signals.
Parameters can be optimized to maximize the capture of upside and downside price movements for trend trading profits. Both channel width and lookback period are tunable.
Simple and clear logic that is easy to understand and implement. Intuitive long/short decisions based on indicators and channel breakouts.
Includes both long and short trades to profit from up and down trends.
Risk Analysis
Channel breakout trades are prone to losses at key reversal points if breakout turns out to be false.
SMA has systemic risk of lagging market turns. Price may already be falling but SMA has yet to turn down.
Poor ATR parameter and coefficient settings can result in irrational channel ranges.
Persistent short losses in bull market uptrends, and persistent long losses in bear market downtrends.
Possible solutions:
Adjust trade frequency or add filters to avoid losses from false breakouts.
Add cross-confirmation with MACD, KDJ to avoid SMA systemic lag risk.
Optimize ATR period and coefficient to ensure reasonable channel range.
Determine overall market regime for trend bias. Go long in bull trending markets and short in bear trends.
Enhancement Opportunities
Some ways this strategy can be enhanced:
Add additional indicator filters to reduce false breakout whipsaws, using MACD, KDJ etc. to confirm signals.
Optimize ATR period and channel coefficient to fit current market volatility conditions through extensive backtesting.
Incorporate automated stop loss to control maximum loss per trade. Trailing stops are a common implementation.
Cut losses quickly when price diverges away from SMA baseline.
Incorporate higher timeframe trend analysis to determine bull/bear bias for breakout direction. For example, use weekly to determine overall trend for daily breakout entries.
Summary
This is a classic channel breakout strategy using SMA and ATR channel bands. Its strength lies in more reliable signals from the dual filters, while weakness is the risk of false breakouts. Further improvements can be made through parameter optimization, stop losses, and trend analysis to make it more robust and aligned with market conditions. With tune-up, it can achieve more consistent profits. The simplicity of this strategy makes it worth exploring and optimizing in practice.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_int_1 | 150 | SMA Length |
| v_input_int_2 | 30 | ATR Length |
| v_input_float_1 | 4 | Upperband Offset |
| v_input_float_2 | 4 | Lowerband Offset |
Source Pine Script
/*backtest
start: 2023-12-01 00:00:00
end: 2023-12-31 23:59:59
period: 30m
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This Pine Script™ code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © omererkan

//@version=5
strategy(title="ATR Channel Breakout")

smaLength = input.int(150, title="SMA Length")
atrLength = input.int(30, title="ATR Length")

ubOffset = input.float(4, title="Upperband Offset", step=0.50)
lbOffset = input.float(4, title="Lowerband Offset", step=0.50)


smaValue = ta.sma(close, smaLength)
atrValue = ta.atr(atrLength)

upperBand = smaValue + (ubOffset * atrValue)
lowerBand = smaValue - (lbOffset * atrValue)


plot(smaValue, title="SMA", color=color.orange)
plot(upperBand, title="UB", color=color.green, linewidth=2)
plot(lowerBand, title="LB", color=color.red, linewidth=2)


enterLong = ta.crossover(close, upperBand)
exitLong  = ta.crossunder(close, smaValue)


enterShort = ta.crossunder(close, lowerBand)
exitShort  = ta.crossover(close, smaValue)


if enterLong
    strategy.entry("Long", strategy.long)

if enterShort
    strategy.entry("Short", strategy.short)


if exitLong
    strategy.close("Long", "Close Long")

if exitShort
    strategy.close("Short", "Close Short")
Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-23. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/An-ATR-Channel-Breakout-Quantitative-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- BB Breakout StrategyPine Script · Breakout · 1d
- Bollinger Band Breakout Trend Following StrategyPine Script · Breakout · 1d
- Bull Flag Breakout StrategyPine Script · Breakout · 1h
- Donchian Channel and Larry Williams Large Trade Index StrategyPine Script · Breakout · 1m
- Dual Breakout Volatility Channel StrategyPine Script · Breakout · 1h
- Dual MA Momentum Breakout StrategyPine Script · Breakout · 1h