Strategy vault / Trend following
Angular VWMA Trend Following Strategy with Dynamic Trailing Stop
This is a trend-following strategy based on Volume Weighted Moving Average (VWMA) and Exponential Moving Average (EMA), incorporating price angle analysis and dynamic trailing stop mechanism. The strategy primarily…
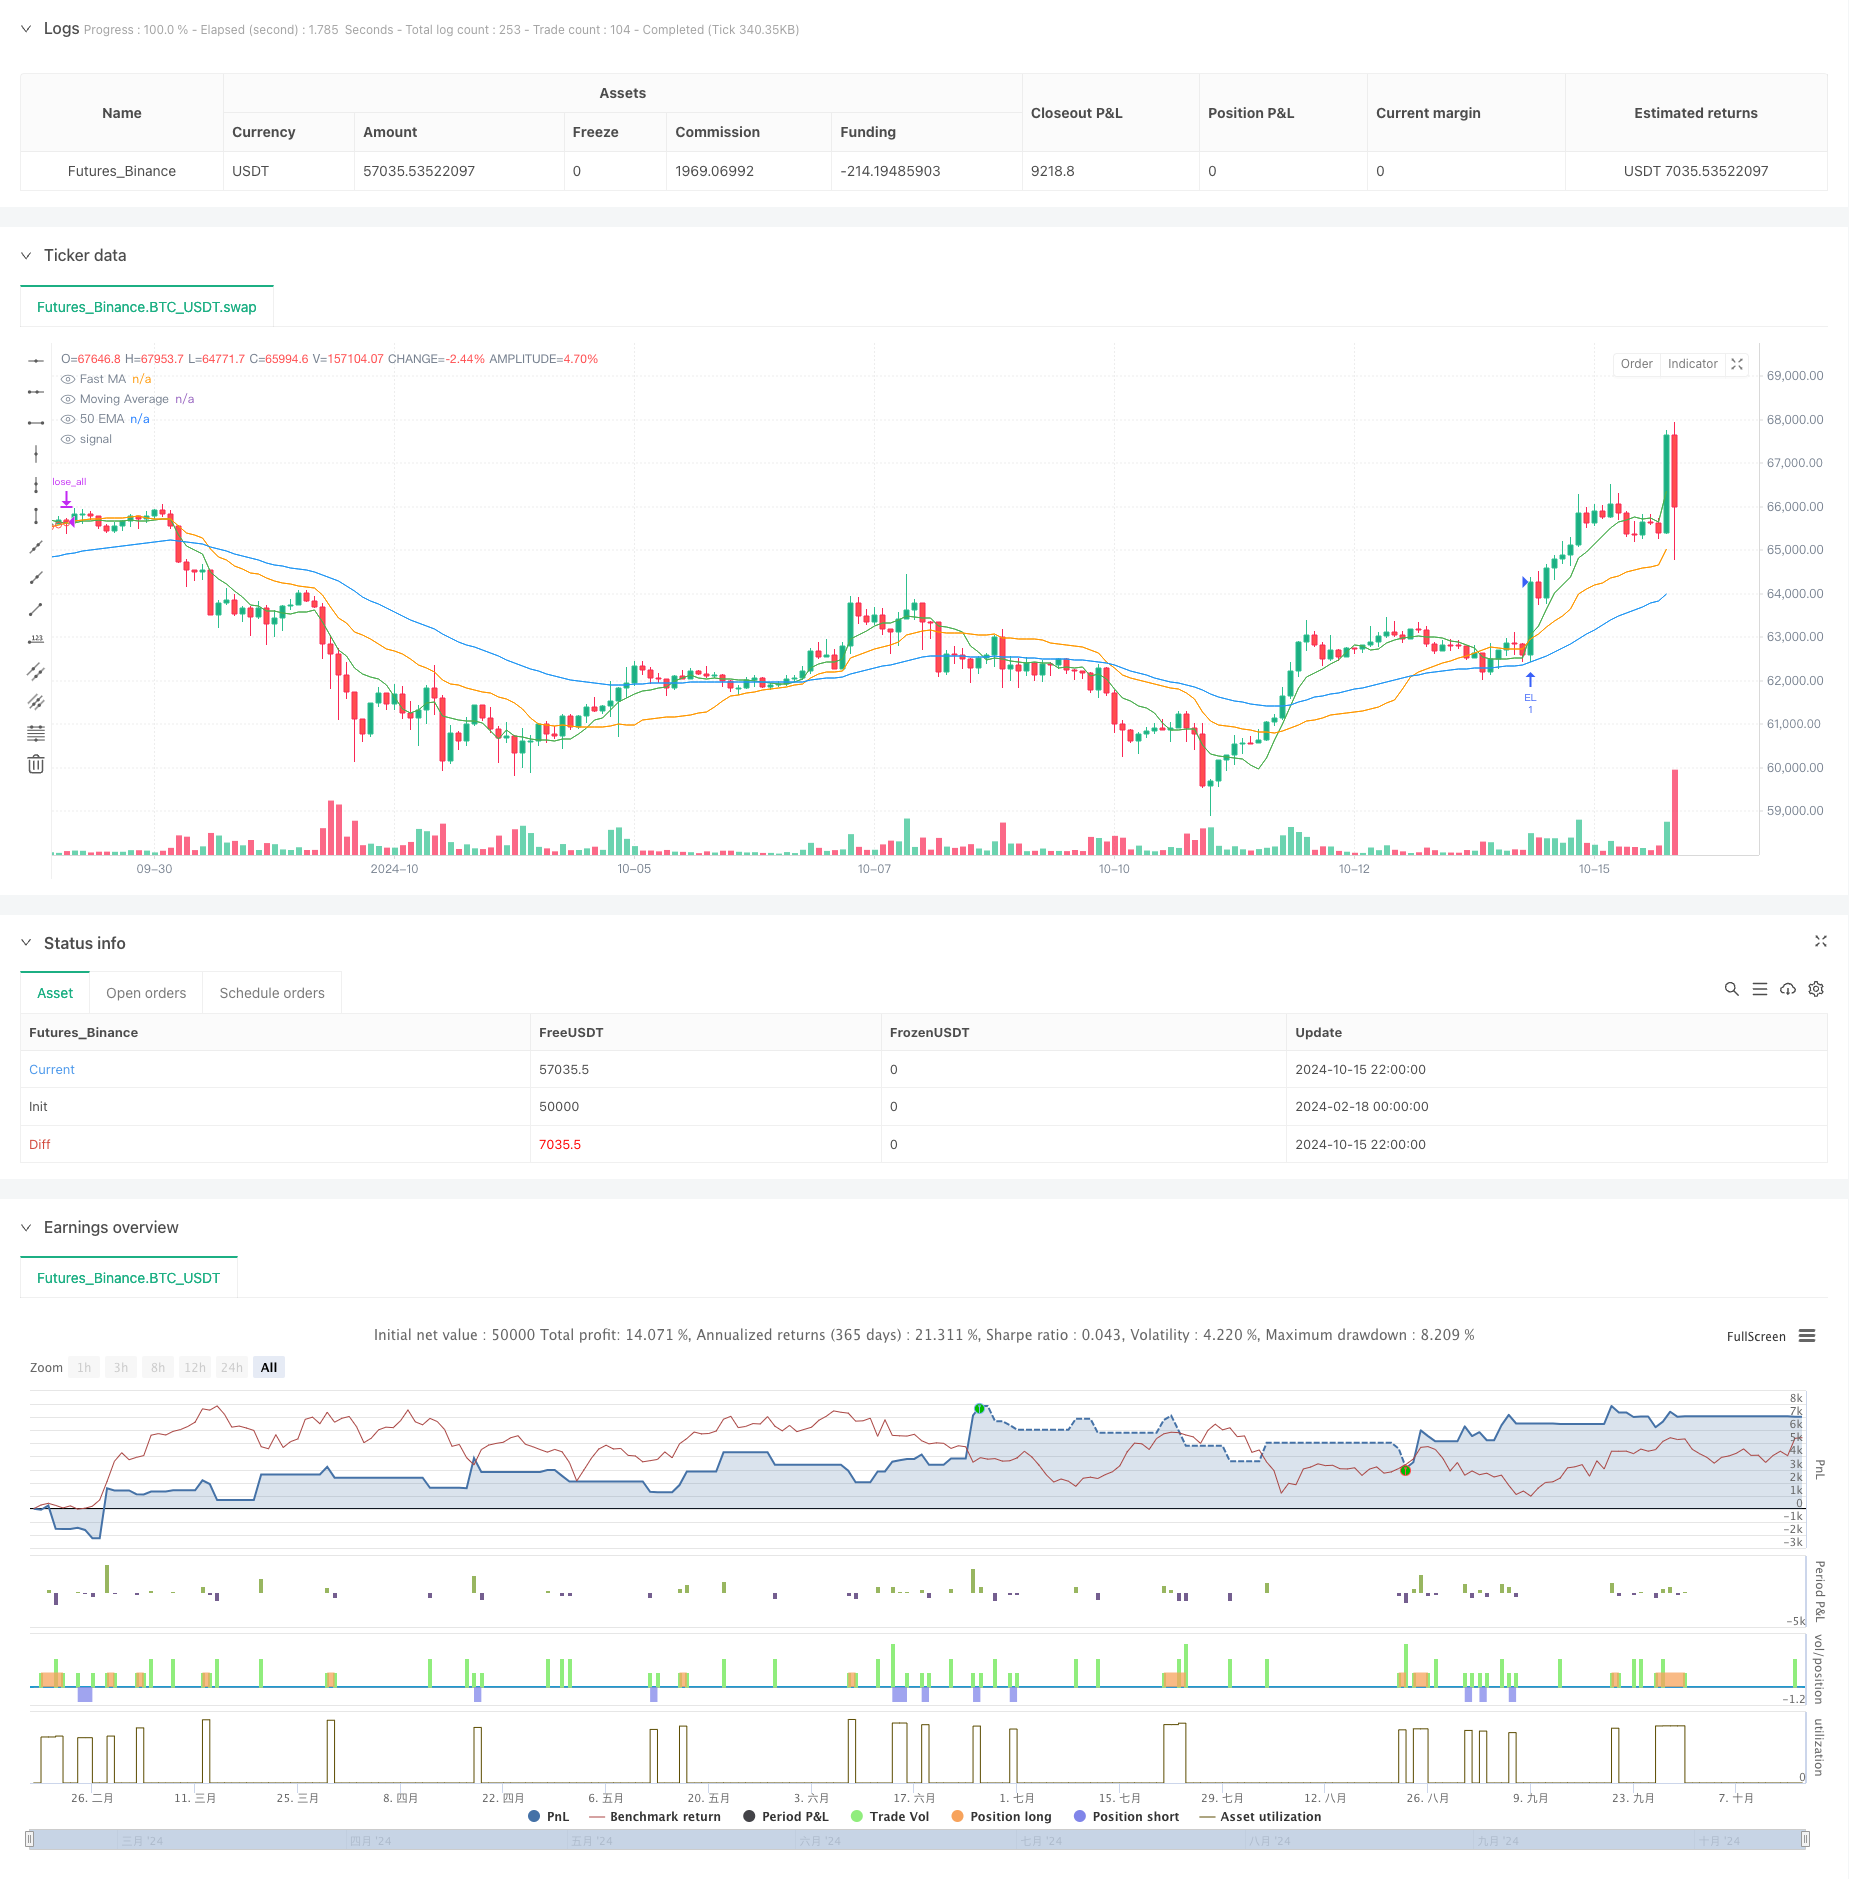
Overview
This is a trend-following strategy based on Volume Weighted Moving Average (VWMA) and Exponential Moving Average (EMA), incorporating price angle analysis and dynamic trailing stop mechanism. The strategy primarily determines entry points through VWMA and fast moving average crossovers, combined with price movement angle conditions, while using percentage-based trailing stops for risk management.
Strategy Principles
The core logic is based on several key components:
- 25-period VWMA as the main trend indicator
- 8-period VWMA as the fast signal line
- 50-period EMA for longer-term trend identification
- 50-period EMA angle calculation (set at 45-degree threshold)
- Optional 200-period EMA as market bias filter Entry signals are triggered when the fast moving average crosses the main VWMA and price angle conditions are met. The strategy protects profits through a 1% dynamic trailing stop.
Strategy Advantages
- Multi-timeframe validation - Strategy performs well on H1 and above, as well as M1 timeframes
- Angle filtration - Reduces false breakouts through price movement angle conditions
- Robust risk management - Employs percentage-based trailing stops for dynamic profit protection
- High adaptability - Can be adjusted through parameters to suit different market conditions
- Comprehensive trend confirmation - Uses multiple moving average crossovers for trend confirmation
Strategy Risks
- Suboptimal performance in ranging markets - May generate frequent false signals in sideways markets
- Delayed entry - Multiple confirmations may cause missing early trend opportunities
- Poor performance on M15 timeframe - Should be avoided on this timeframe
- Parameter sensitivity - Angle threshold and moving average period selection significantly impact strategy performance
- Early exits from trailing stops - May result in premature stopouts in volatile markets
Strategy Optimization Directions
- Implement volatility adaptation - Dynamically adjust trailing stop percentage based on market volatility
- Add volume filters - Enhance signal quality through volume confirmation
- Optimize angle calculation - Consider using adaptive angle thresholds
- Incorporate market state recognition - Develop trend/range market identification mechanisms
- Improve exit mechanisms - Optimize exit timing through price patterns and momentum indicators
Summary
This is a well-structured trend-following strategy that achieves good performance in major trends through the combination of angle analysis and multiple moving averages. While it has certain limitations in terms of lag and parameter sensitivity, there is room for improvement through the suggested optimization directions. It is particularly suitable for trend trading in longer timeframes.
Source Pine Script
/*backtest
start: 2024-02-18 00:00:00
end: 2024-10-16 00:00:00
period: 2h
basePeriod: 2h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=6
strategy("PVSRA Trailing Strategy with Angle Condition (40-50 degrees)", overlay=true)

// === INPUTS ===
priceData = input.source(close, title="Price Data")
maLength  = input.int(25, title="Moving Average Length", minval=2)
useBias   = input.bool(false, title="Long/Short just above/below 200 EMA")
useTrailing = input.bool(true, title="Use Trailing Stop")
trailPerc  = input.float(1.0, title="Trailing Stop Percentage", minval=0.1)
anglePeriod = input.int(14, title="Period for Angle Calculation", minval=1)

// === CÁLCULOS ===
maValue = ta.vwma(priceData, maLength)
maLong  = ta.ema(high, 50)
maShort = ta.ema(low, 50)
maFast  = ta.vwma(close, 8)
bias    = ta.ema(close, 200)
longBias  = useBias ? close > bias : true
shortBias = useBias ? close < bias : true

// === CÁLCULO DO ÂNGULO DA MÉDIA MÓVEL DE 50 ===
ma50 = ta.ema(close, 50)
angle = math.atan((ma50 - ma50[anglePeriod]) / anglePeriod) * (180 / math.pi)  // Converte radianos para graus

// === CONDIÇÃO DE ÂNGULO ===
validAngleL = angle >= 45
validAngleS = angle <= 45

// === PLOTS ===
plot(maValue, color=color.orange, title="Moving Average")
plot(maFast, color=color.green, title="Fast MA")
plot(ma50, color=color.blue, title="50 EMA")

plotshape(series=(strategy.position_size > 0) ? maValue : na,
     color=color.red, style=shape.circle, location=location.absolute,
     title="Long Stop")

plotshape(series=(strategy.position_size < 0) ? maValue : na,
     color=color.red, style=shape.cross, location=location.absolute,
     title="Short Stop")

// === CONDIÇÕES DE ENTRADA ===
enterLong  = close > maValue and ta.crossover(maFast, maValue) and close > maLong and longBias and validAngleL
enterShort = close < maValue and ta.crossunder(maFast, maValue) and close < maShort and shortBias and validAngleS

// === CONDIÇÕES DE SAÍDA ===
exitLong  = ta.crossunder(maFast, maValue) and strategy.position_size > 0
exitShort = ta.crossover(maFast, maValue) and strategy.position_size < 0

// === EXECUÇÃO DA ESTRATÉGIA ===
if (enterLong)
    strategy.entry("EL", strategy.long)

if (enterShort)
    strategy.entry("ES", strategy.short)

if (exitLong or exitShort)
    strategy.close_all()

// === TRAILING STOP ===
if (useTrailing and strategy.position_size > 0)
    trailPrice = close * (1 - trailPerc / 100)
    strategy.exit("Trailing Long", from_entry="EL", stop=trailPrice)

if (useTrailing and strategy.position_size < 0)
    trailPrice = close * (1 + trailPerc / 100)
strategy.exit("Trailing Short", from_entry="ES", stop=trailPrice)Published by ChaoZhang on the FMZ strategy square · last modified 2025-02-18. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Angular-VWMA-Trend-Following-Strategy-with-Dynamic-Trailing-Stop.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- CM Multiple EMA Crossover StrategyPine Script · Trend following · 6h
- Dynamic Dual EMA Trend Following StrategyPine Script · Trend following · 1d
- EMA 200 Crossover with Volume and Trend StrategyPine Script · Trend following · 1d
- EMA SMA Trend Following with Swing Trading Strategy Combined Volume Filter and Percentage Take Profit Stop Loss SystemPine Script · Trend following · 1d
- Fixed Range Volume Profile And Anchored VWAP Trend Identification Strategy With Dynamic Stop LossPine Script · Trend following · 1h
- Multi Exponential Moving Average Crossover Strategy with Volume Based ATR Dynamic Stop Loss OptimizationPine Script · Trend following · 2d