Strategy vault / Trend following
AO Multi Layer Quantitative Trend Enhancement Strategy
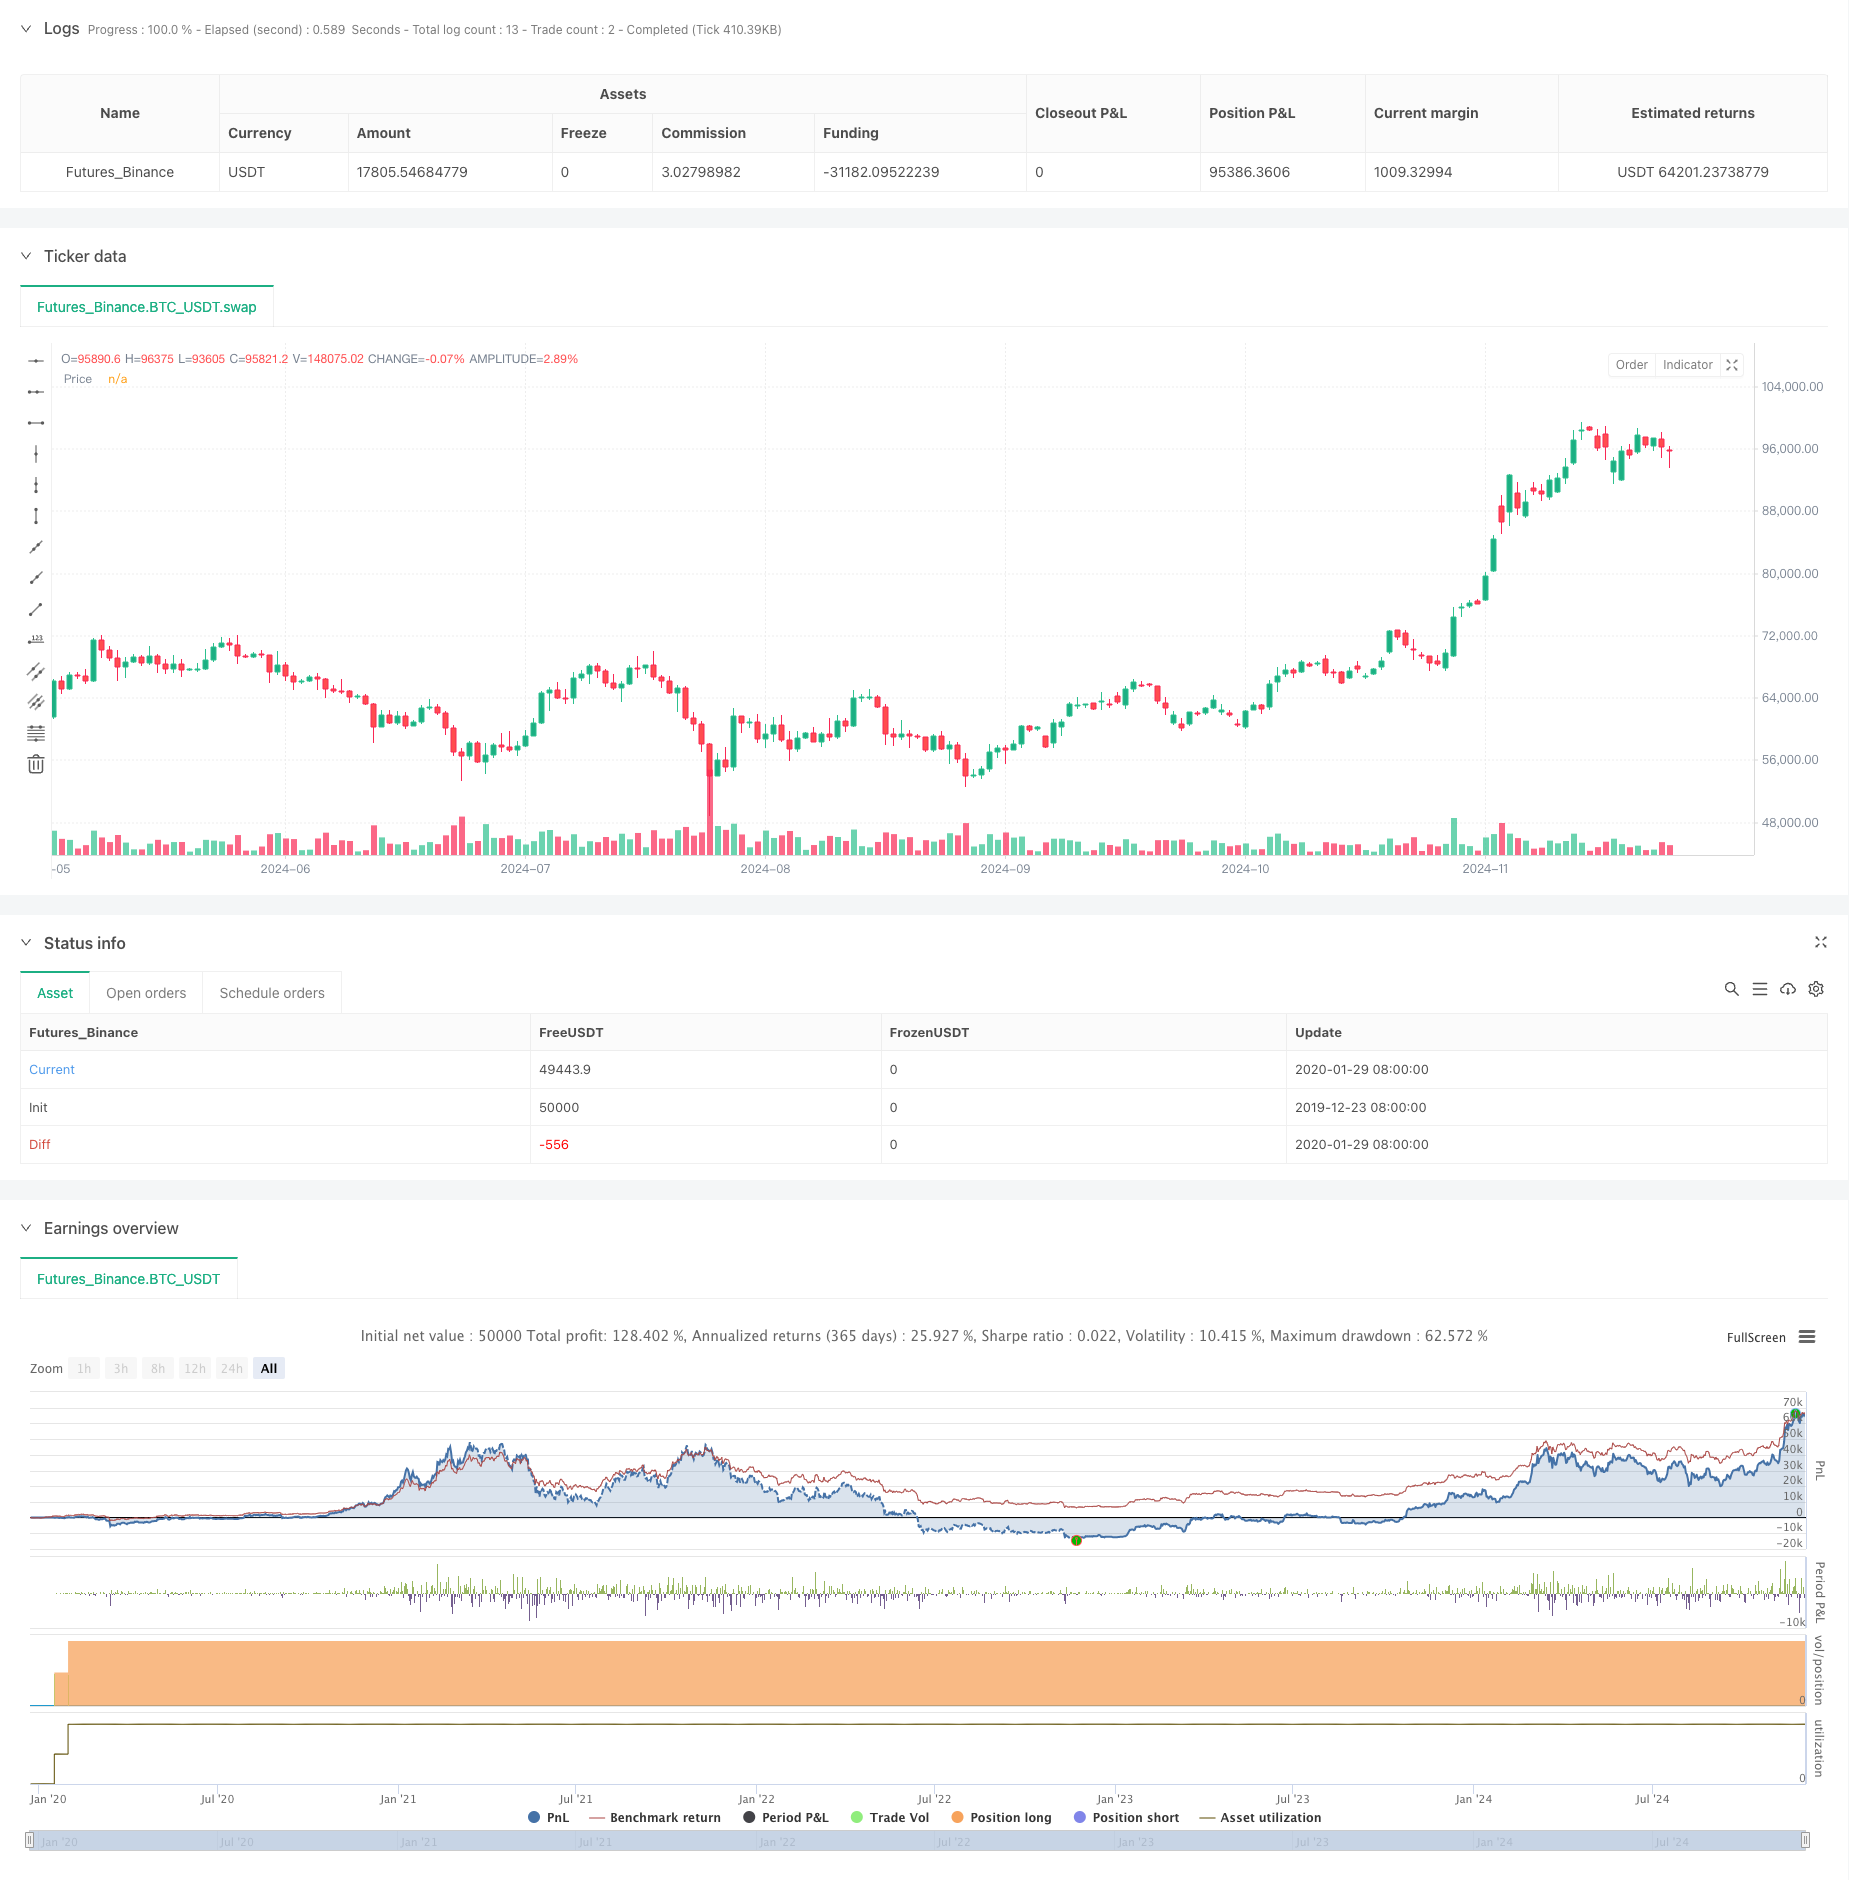
This strategy is a multi-layer trading system based on momentum and trend following. It combines Williams Alligator, Williams Fractals, Awesome Oscillator (AO), and Exponential Moving Average (EMA) to identify…
Overview
This strategy is a multi-layer trading system based on momentum and trend following. It combines Williams Alligator, Williams Fractals, Awesome Oscillator (AO), and Exponential Moving Average (EMA) to identify high-probability long opportunities. The strategy employs a layered capital deployment mechanism, gradually increasing positions as trends strengthen, with the capability to hold up to 5 positions simultaneously, each using 10% of capital.
Strategy Principles
The strategy utilizes multiple filtering mechanisms to ensure trading direction accuracy. First, it uses EMA for long-term trend judgment, seeking long opportunities only when price is above EMA. Second, it judges short-term trends through the combination of Williams Alligator and Fractals, confirming an uptrend when an up fractal breakout occurs above the Alligator's teeth line. Finally, after trend confirmation, the strategy looks for AO indicator's "saucer" long signals for specific entry timing. The system uses only 10% of capital per trade and can open up to 5 long positions as the trend strengthens. When the fractal and Alligator combination indicates trend reversal, all positions are closed.
Strategy Advantages
- Multi-layer filtering mechanism effectively reduces false signals
- Scientific capital management with progressive position building
- Trend-following characteristics enable capturing major trends
- No fixed stop-loss, using technical indicators for dynamic trend end determination
- System has good configurability for different market conditions
- Backtesting shows good profit factor and average returns
Strategy Risks
- May generate consecutive false signals in ranging markets
- Potential significant drawdowns during trend reversals
- Multiple filtering conditions might miss some trading opportunities
- In capital management, consecutive position building may bring risks during volatile periods
- EMA parameter selection significantly impacts strategy performance
To reduce these risks, it's recommended to:
- Optimize parameters for different market environments
- Consider adding volatility filters
- Establish stricter position building conditions
- Set maximum drawdown limits
Strategy Optimization Directions
- Introduce ATR indicator for volatility filtering
- Add volume analysis to improve signal reliability
- Develop dynamic parameter adaptation mechanism
- Perfect profit-taking mechanism for timely exits when trends weaken
- Add market state recognition module for different parameter sets in different market environments
Summary
This is a well-designed trend-following strategy that achieves good returns while maintaining safety through the combination of multiple technical indicators. The strategy's innovation lies in its multi-layer trend confirmation mechanism and progressive capital management method. While there are areas for optimization, it is overall a trading system worth trying.
Source Pine Script
/*backtest
start: 2019-12-23 08:00:00
end: 2024-12-04 00:00:00
period: 1d
basePeriod: 1d
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This Pine Script™ code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © Skyrexio

//@version=6
//_______ <licence>
strategy(title = "MultiLayer Awesome Oscillator Saucer Strategy [Skyrexio]",
         shorttitle = "AO Saucer",
         overlay = true,
         format = format.inherit,
         pyramiding = 5,
         calc_on_order_fills = false,
         calc_on_every_tick = false,
         default_qty_type = strategy.percent_of_equity,
         default_qty_value = 10,
         initial_capital = 10000,
         currency = currency.NONE,
         commission_type = strategy.commission.percent,
         commission_value = 0.1,
         slippage = 5,
         use_bar_magnifier = true)


//_______ <constant_declarations>
var const color skyrexGreen               = color.new(#2ECD99, 0)
var const color skyrexGray                = color.new(#F2F2F2, 0)
var const color skyrexWhite               = color.new(#FFFFFF, 0)


//________<variables declarations>
var int trend                             = 0
var float upFractalLevel                  = na
var float upFractalActivationLevel        = na
var float downFractalLevel                = na
var float downFractalActivationLevel      = na
var float saucerActivationLevel           = na
bool highCrossesUpfractalLevel            = ta.crossover(high, upFractalActivationLevel)
bool lowCrossesDownFractalLevel           = ta.crossunder(low, downFractalActivationLevel)
var int signalsQtyInRow                   = 0


//_______ <inputs>
// Trading bot settings
sourceUuid               = input.string(title = "sourceUuid:", defval = "yourBotSourceUuid", group = "?Trading Bot Settings?")
secretToken              = input.string(title = "secretToken:", defval = "yourBotSecretToken", group = "?Trading Bot Settings?")


// Trading period settings
lookBackPeriodStart      = input(title = "Trade Start Date/Time", defval = timestamp('2023-01-01T00:00:00'), group = "?Trading Period Settings?")
lookBackPeriodStop       = input(title = "Trade Stop Date/Time", defval = timestamp('2025-01-01T00:00:00'), group = "?Trading Period Settings?")


// Strategy settings
EMaLength                = input.int(100, minval = 10, step = 10, title = "EMA Length", group = "?Strategy settings?")


//_______ <function_declarations>
//@function       Used to calculate Simple moving average for Alligator
//@param src      Sourse for smma Calculations
//@param length   Number of bars to calculate smma
//@returns        The calculated smma value
smma(src, length) =>
    var float smma = na
    sma_value = ta.sma(src, length)
    smma := na(smma) ? sma_value : (smma * (length - 1) + src) / length
    smma

//_______ <calculations>


//Upfractal calculation
upFractalPrice = ta.pivothigh(2, 2)
upFractal = not na(upFractalPrice)


//Downfractal calculation
downFractalPrice = ta.pivotlow(2, 2)
downFractal = not na(downFractalPrice)


//Calculating Alligator's teeth
teeth = smma(hl2, 8)[5]


//Calculating upfractal and downfractal levels
if upFractal
    upFractalLevel := upFractalPrice
else
    upFractalLevel := upFractalLevel[1]


if downFractal
    downFractalLevel := downFractalPrice
else
    downFractalLevel := downFractalLevel[1]


//Calculating upfractal activation level, downfractal activation level to approximate the trend and this current trend
if upFractalLevel > teeth
    upFractalActivationLevel := upFractalLevel

if highCrossesUpfractalLevel
    trend := 1
    upFractalActivationLevel := na
    downFractalActivationLevel := downFractalLevel


if downFractalLevel < teeth
    downFractalActivationLevel := downFractalLevel

if lowCrossesDownFractalLevel
    trend := -1
    downFractalActivationLevel := na
    upFractalActivationLevel := upFractalLevel


if trend == 1
    upFractalActivationLevel := na

if trend == -1
    downFractalActivationLevel := na


//Calculating filter EMA
filterEMA = ta.ema(close, EMaLength)


//Сalculating AO saucer signal
ao = ta.sma(hl2,5) - ta.sma(hl2,34)
diff = ao - ao[1]
saucerSignal = ao > ao[1] and ao[1] < ao[2] and ao > 0 and ao[1] > 0 and ao[2] > 0 and trend == 1 and close > filterEMA


//Calculating sauser activation level
if saucerSignal
    saucerActivationLevel := high
else
    saucerActivationLevel := saucerActivationLevel[1]


if not na(saucerActivationLevel[1]) and high < saucerActivationLevel[1] and diff > 0
    saucerActivationLevel := high
    saucerSignal := true


if (high > saucerActivationLevel[1] and not na(saucerActivationLevel)) or diff < 0
    saucerActivationLevel := na


//Calculating number of valid saucer signal in current trading cycle
if saucerSignal and not saucerSignal[1]
    signalsQtyInRow := signalsQtyInRow + 1


if not na(saucerActivationLevel[1]) and diff < 0 and na(saucerActivationLevel) and not (strategy.opentrades[1] <= strategy.opentrades - 1)
    signalsQtyInRow := signalsQtyInRow - 1


if trend == -1 and trend[1] == 1
    signalsQtyInRow := 0


//_______ <strategy_calls>
//Defining trade close condition
closeCondition =  trend[1] == 1 and trend == -1


//Cancel stop buy order if current Awesome oscillator column lower, than prevoius
if diff < 0
    strategy.cancel_all()

//Strategy entry
if (signalsQtyInRow == 1 and not na(saucerActivationLevel))
    strategy.entry(id = "entry1", direction = strategy.long, stop = saucerActivationLevel + syminfo.mintick,  alert_message = '{\n"base": "' + syminfo.basecurrency + '",\n"quote": "' + syminfo.currency + '",\n"position": "entry1",\n"price": "' + str.tostring(close) + '",\n"sourceUuid": "' + sourceUuid + '",\n"secretToken": "' + secretToken + '",\n"timestamp": "' + str.tostring(timenow) + '"\n}')

if (signalsQtyInRow == 2 and not na(saucerActivationLevel))
    strategy.entry(id = "entry2", direction = strategy.long, stop = saucerActivationLevel + syminfo.mintick,  alert_message = '{\n"base": "' + syminfo.basecurrency + '",\n"quote": "' + syminfo.currency + '",\n"position": "entry2",\n"price": "' + str.tostring(close) + '",\n"sourceUuid": "' + sourceUuid + '",\n"secretToken": "' + secretToken + '",\n"timestamp": "' + str.tostring(timenow) + '"\n}')

if (signalsQtyInRow == 3 and not na(saucerActivationLevel))
    strategy.entry(id = "entry3", direction = strategy.long, stop = saucerActivationLevel + syminfo.mintick,  alert_message = '{\n"base": "' + syminfo.basecurrency + '",\n"quote": "' + syminfo.currency + '",\n"position": "entry3",\n"price": "' + str.tostring(close) + '",\n"sourceUuid": "' + sourceUuid + '",\n"secretToken": "' + secretToken + '",\n"timestamp": "' + str.tostring(timenow) + '"\n}')

if (signalsQtyInRow == 4 and not na(saucerActivationLevel))
    strategy.entry(id = "entry4", direction = strategy.long, stop = saucerActivationLevel + syminfo.mintick,  alert_message = '{\n"base": "' + syminfo.basecurrency + '",\n"quote": "' + syminfo.currency + '",\n"position": "entry4",\n"price": "' + str.tostring(close) + '",\n"sourceUuid": "' + sourceUuid + '",\n"secretToken": "' + secretToken + '",\n"timestamp": "' + str.tostring(timenow) + '"\n}')

if (signalsQtyInRow == 5 and not na(saucerActivationLevel))
    strategy.entry(id = "entry5", direction = strategy.long, stop = saucerActivationLevel + syminfo.mintick,  alert_message = '{\n"base": "' + syminfo.basecurrency + '",\n"quote": "' + syminfo.currency + '",\n"position": "entry5",\n"price": "' + str.tostring(close) + '",\n"sourceUuid": "' + sourceUuid + '",\n"secretToken": "' + secretToken + '",\n"timestamp": "' + str.tostring(timenow) + '"\n}')

//Strategy exit
if (closeCondition)
    strategy.close_all(alert_message = '{\n"base": "' + syminfo.basecurrency + '",\n"quote": "' + syminfo.currency + '",\n"position": "close",\n"price": "' + str.tostring(close) + '",\n"sourceUuid": "' + sourceUuid + '",\n"secretToken": "' + secretToken + '",\n"timestamp": "' + str.tostring(timenow) + '"\n}')


//_______ <visuals>
//Plotting shapes for adding to current long trades
gradPercent = if strategy.opentrades == 2
    90
else if strategy.opentrades == 3
    80
else if strategy.opentrades == 4
    70
else if strategy.opentrades == 5
    60

pricePlot = plot(close, title="Price", color=color.new(color.blue, 100))
teethPlot = plot(strategy.opentrades > 1 ? teeth : na, title="Teeth", color= skyrexGreen, style=plot.style_linebr, linewidth = 2)
fill(pricePlot, teethPlot, color = color.new(skyrexGreen, gradPercent))
if strategy.opentrades != 1 and  strategy.opentrades[1] == strategy.opentrades - 1
    label.new(bar_index, teeth, style = label.style_label_up, color = color.lime, size = size.tiny, text="Buy More", textcolor = color.black, text_formatting = text.format_bold)


//_______ <alerts>
Published by ChaoZhang on the FMZ strategy square · last modified 2024-12-05. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/AO-Multi-Layer-Quantitative-Trend-Enhancement-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Fixed Range Volume Profile And Anchored VWAP Trend Identification Strategy With Dynamic Stop LossPine Script · Trend following · 1h
- Multi Factor Trend Price Action Strategy with Dynamic Risk Management SystemPine Script · Trend following · 2h
- Multi Indicator Dynamic Trend Following Strategy Based on EMA and SMAPine Script · Trend following · 1d
- Trend Following Strategy Based on PMax IndicatorPine Script · Trend following · 5m
- Trend Tracking and Short term Trading Strategy Based on ADX IndicatorPine Script · Trend following · 1d
- Triple Supertrend Ichimoku Cloud Quantitative Trading StrategyPine Script · Trend following · 1d