Architecture Breakthrough Backtesting Strategy
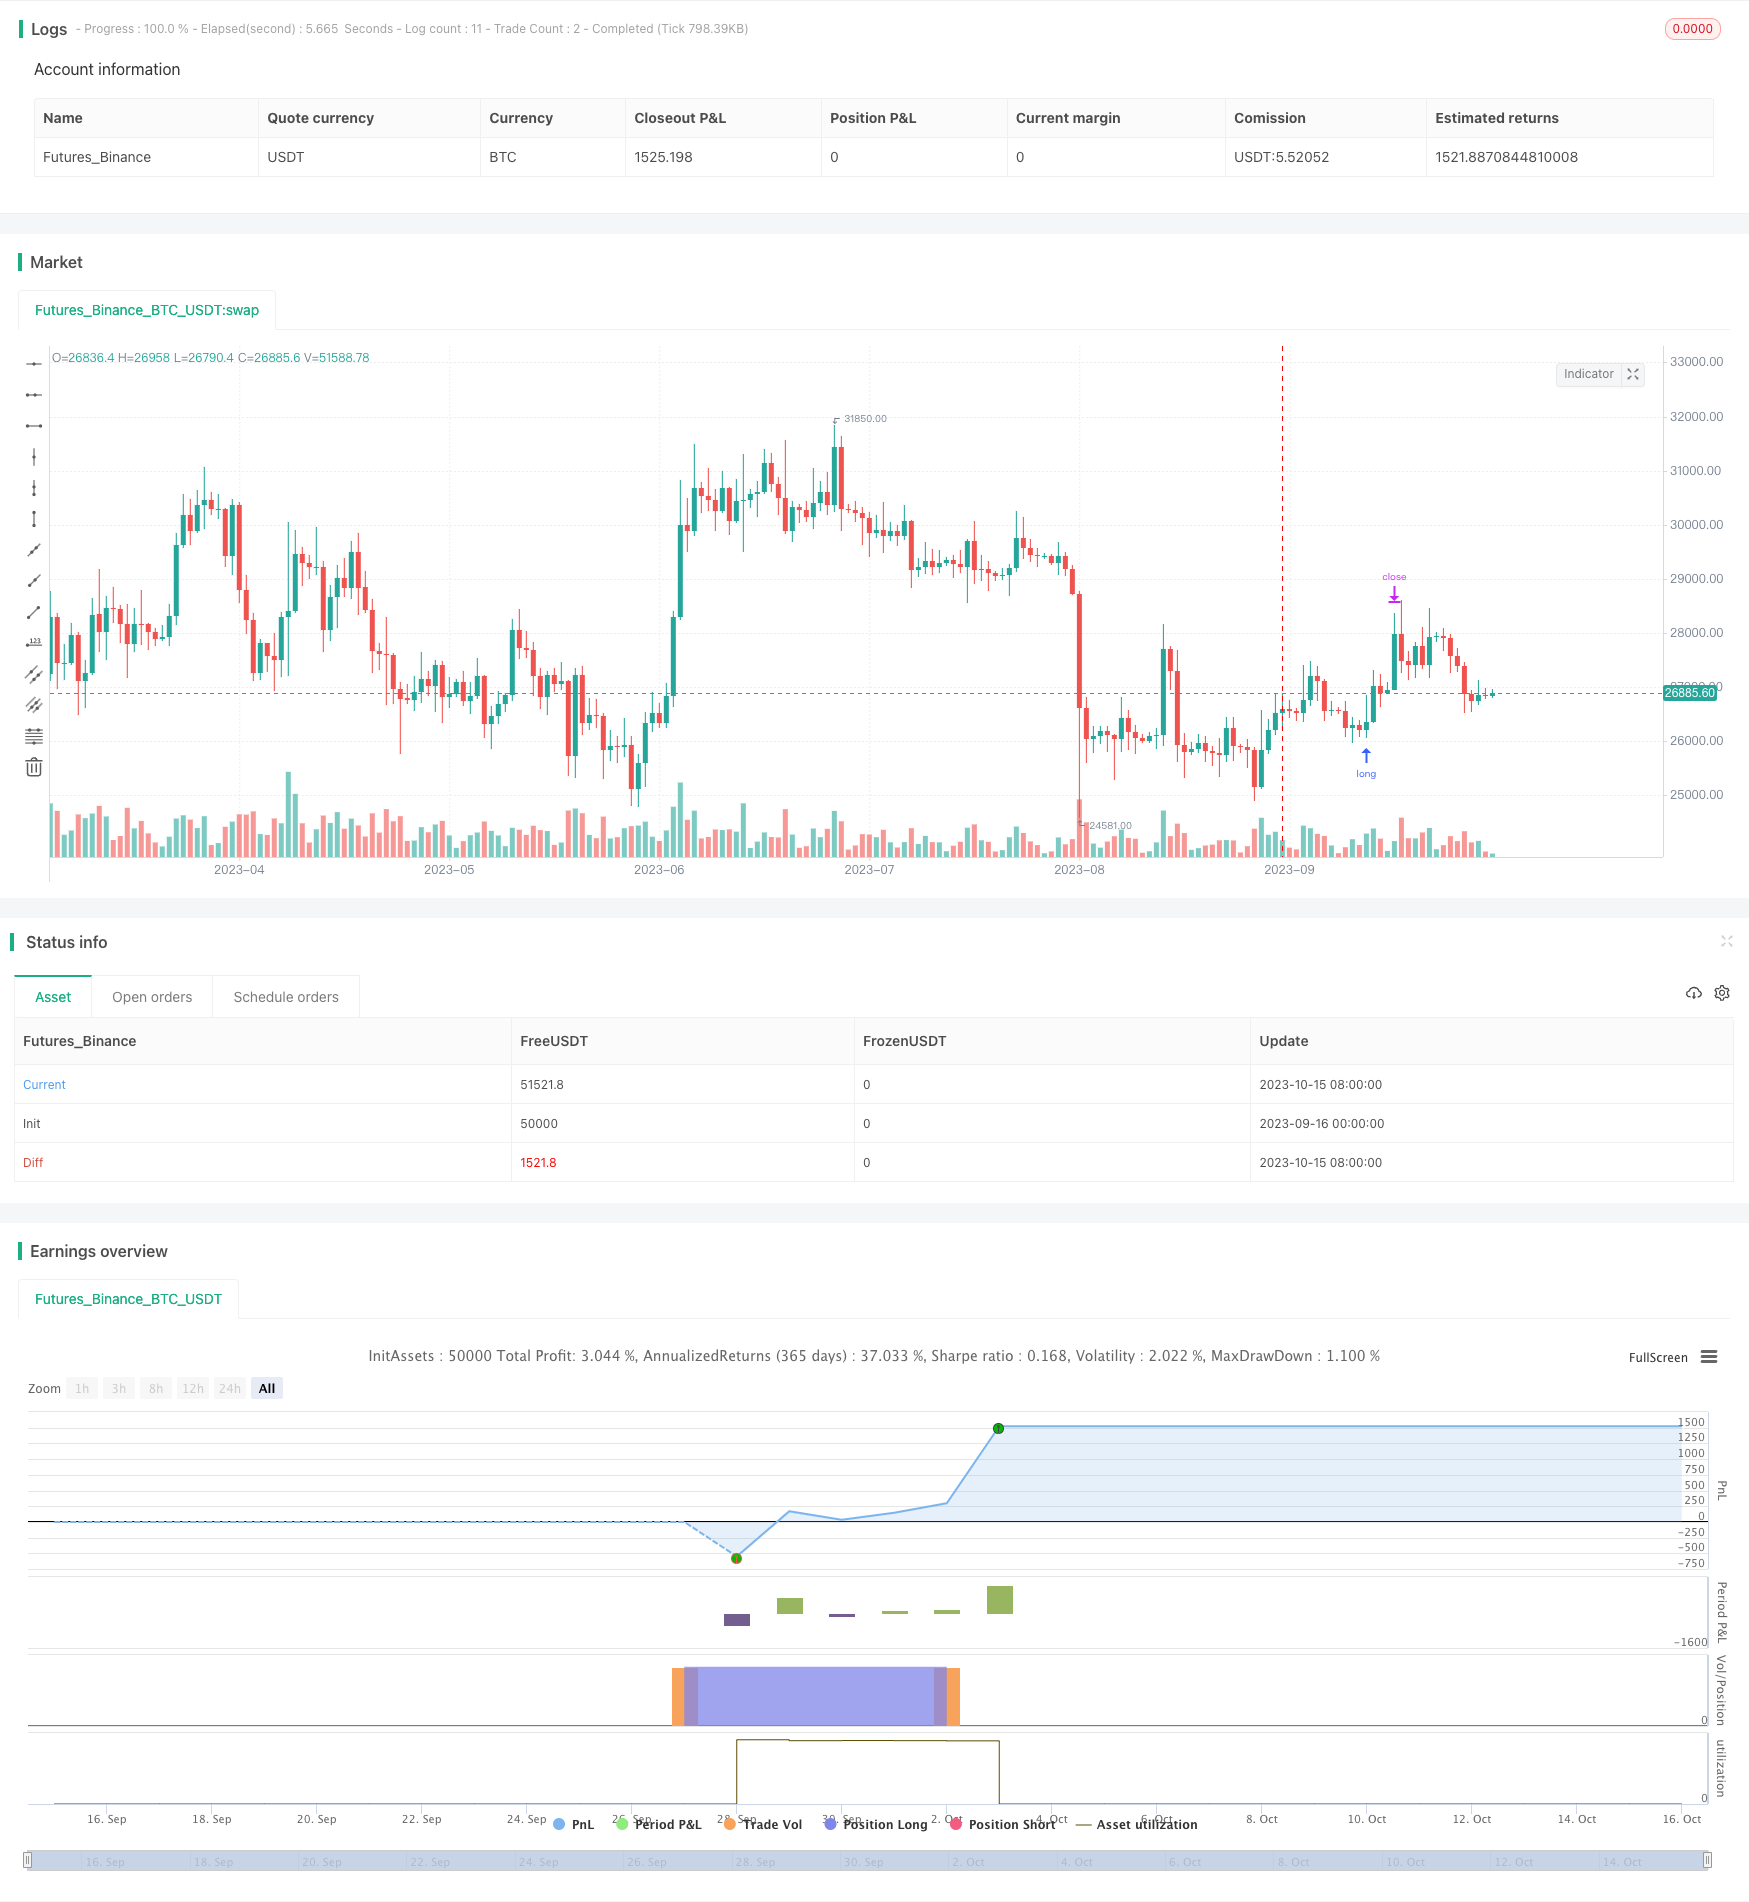
This strategy adopts a level breakthrough approach to go long or short under certain breakthrough conditions, and has auto-backtesting capabilities to find the optimal parameter combination.
Overview
This strategy adopts a level breakthrough approach to go long or short under certain breakthrough conditions, and has auto-backtesting capabilities to find the optimal parameter combination.
Principle
Input parameters include lookback days, take profit percentage, stop loss percentage, and auto-backtesting parameters like lookback range, take profit/stop loss range etc.
During backtesting, traverse various combinations of lookback, take profit and stop loss, and record PnL for each combination.
Breakthrough signal logic: long when close breaks above upper band and not the entry bar, short when close breaks below lower band and not the entry bar.
Stop loss condition: if not take profited and stop loss is triggered, exit the trade.
Take profit condition: if not stopped out and take profit is triggered, exit the trade.
Display detailed backtest results table, sortable by win rate, net profit or number of trades based on user settings.
Advantages
Auto backtest can quickly find optimal parameter sets without manual testing.
Sort backtest results flexibly by win rate, net profit, number of trades etc according to needs.
Visualize PnL for each trade.
Customizable backtest parameters for testing wider parameter space to find global optimum.
Simple and clear trading rules easy to understand and implement.
Risks and Solutions
Short backtest period may lead to unstable results. Solution: use longer backtest period.
Frequent trading prone to slippage affecting profitability. Solution: relax take profit/stop loss levels appropriately.
Single instrument backtest may not be representative. Solution: test on different products to find robust parameter sets.
Over-optimized parameters cause overfitting. Solution: test stability of parameters across products and timeframes.
Ignoring transaction costs lead to bias in results. Solution: use reasonable commission settings.
Enhancement Directions
Increase optimization dimensions like adding trailing stop or trade limits.
Optimize entry conditions with trend filters.
Enhance take profit/stop loss like dynamic take profit or trailing stop loss.
Introduce machine learning for parameter optimization.
Optimize code structure for faster backtesting.
Test parameter robustness across products and timeframes.
Consider integrating auto trading capabilities.
Conclusion
The strategy has clear and simple logic, auto backtesting enables quick parameter tuning, PnL display facilitates further improvements. Risks exist but can be reduced through multi-dimensional optimizations, with strong practical value. In summary, this strategy equipped with auto backtesting tools can help traders quickly develop stable trading systems based on simple breakout concepts.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_int_1 | 2 | Lookback |
| v_input_float_1 | 5 | TP (%) |
| v_input_float_2 | 5 | SL (% from Low) |
| v_input_float_3 | 0.075 | Commission (%) |
| v_input_float_4 | 2 | (?Optimisation)Min Lookback |
| v_input_float_5 | 5 | Max Lookback |
| v_input_float_6 | 5 | Min TP (%) |
| v_input_float_7 | 10 | Max TP (%) |
| v_input_float_8 | true | Min SL (%) |
| v_input_float_9 | 5 | Max SL (%) |
| v_input_bool_1 | true | Percentage profitable |
| v_input_bool_2 | false | Net profit |
| v_input_bool_3 | false | Number of trades |
| v_input_string_1 | 0 | (?Table)Position: Bottom Right | Top Center | Top Right | Middle Left | Middle Center | Middle Right | Bottom Left | Bottom Center | Top Left |
| v_input_string_2 | 0 | Font size: Normal | Tiny | Small | Auto | Large |
Source Pine Script
/*backtest
start: 2023-09-16 00:00:00
end: 2023-10-16 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// © -_-
//@version=5
// strategy("[-_-] LBAB", process_orders_on_close=true, overlay=true, max_labels_count=500, max_lines_count=500, max_boxes_count=500, default_qty_type=strategy.cash, default_qty_value=100, initial_capital=10000, commission_type=strategy.commission.percent, commission_value=0.075)

// Inputs
lookback = input.int(2, title="Lookback", minval=2, maxval=15)
tp = input.float(5, title="TP (%)", minval=1, maxval=10000)
sl = input.float(5, title="SL (% from Low)", minval=1, maxval=100)
com = input.float(0.075, title="Commission (%)", minval=0, maxval=50)

min_lookback_tr = input.float(2, title="Min Lookback", minval=1, maxval=500, inline="tr_lookback", group="Optimisation")
max_lookback_tr = input.float(5, title="Max Lookback", minval=1, maxval=500, inline="tr_lookback", group="Optimisation")
min_tp_tr = input.float(5, title="Min TP (%)", minval=1, maxval=10000, inline="tr_tp", group="Optimisation")
max_tp_tr = input.float(10, title="Max TP (%)", minval=1, maxval=10000, inline="tr_tp", group="Optimisation")
min_sl_tr = input.float(1, title="Min SL (%)", minval=1, maxval=100, inline="tr_sl", group="Optimisation")
max_sl_tr = input.float(5, title="Max SL (%)", minval=1, maxval=100, inline="tr_sl", group="Optimisation")
imp_perc_profit = input.bool(true, title="Percentage profitable", group="Optimisation")
imp_netprofit = input.bool(false, title="Net profit", group="Optimisation")
imp_numtrades = input.bool(false, title="Number of trades", group="Optimisation")
table_pos = input.string("Bottom Right", title="Position", options=["Top Left", "Top Center", "Top Right", "Middle Left", "Middle Center", "Middle Right", "Bottom Left", "Bottom Center", "Bottom Right"], group="Table")
table_font_size = input.string("Normal", title="Font size", options=["Auto", "Tiny", "Small", "Normal", "Large"], group="Table")

// Table parameters
table_pos_ = switch table_pos
    "Top Left" => position.top_left
    "Top Center" => position.top_center
    "Top Right" => position.top_right
    "Middle Left" => position.middle_left
    "Middle Center" => position.middle_center
    "Middle Right" => position.middle_right
    "Bottom Left" => position.bottom_left
    "Bottom Center" => position.bottom_center
    "Bottom Right" => position.bottom_right

table_font_size_ = switch table_font_size
    "Auto" => size.auto
    "Tiny" => size.tiny
    "Small" => size.small
    "Normal" => size.normal
    "Large" => size.large

// Sorting function (first element will be largest)
sortArr(arr, arr_index) =>
    n = array.size(arr) - 1
    for i = 0 to n - 1
        for j = 0 to n - i - 1
            if array.get(arr, j) < array.get(arr, j + 1)
                temp = array.get(arr, j)
                temp_index = array.get(arr_index, j)
                array.set(arr, j, array.get(arr, j + 1))
                array.set(arr, j + 1, temp)
                array.set(arr_index, j, array.get(arr_index, j + 1))
                array.set(arr_index, j + 1, temp_index)

// Safe checks
if min_lookback_tr > max_lookback_tr
    runtime.error("Min Lookback must be less than Max Lookback")
if min_tp_tr > max_tp_tr
    runtime.error("Min Take Profit must be less than Max Take Profit")
if min_sl_tr > max_sl_tr
    runtime.error("Min Stop Loss must be less than Max Stop Loss")

//
tp_min_ = int(min_tp_tr / 1)
tp_max_ = int(max_tp_tr / 1)

sl_min_ = int(min_sl_tr / 1)
sl_max_ = int(max_sl_tr / 1)

// Size for arrays
arr_size = int((max_lookback_tr - min_lookback_tr + 1) * (tp_max_ - tp_min_ + 1) * (sl_max_ - sl_min_ + 1))

// Arrays
var arr_bi = array.new_int(arr_size, na)           // bar_index of Smash Day
var arr_in_pos = array.new_bool(arr_size, false)   // are we in a position?

var arr_params = array.new_string(arr_size, "")
var arr_wonlost = array.new_string(arr_size, "")
var arr_profit = array.new_float(arr_size, 0)

// Testing what parameters are best
index = 0

// Lookback
for lookback_i = min_lookback_tr to max_lookback_tr
    // Take profit
    for tp_i = tp_min_ to tp_max_
        // Stop loss
        for sl_i = sl_min_ to sl_max_
            // Parameters of current iteration
            lookback_ = lookback_i
            tp_ = tp_i
            sl_ = sl_i

            //
            if array.get(arr_params, index) == ""
                array.set(arr_params, index, str.tostring(lookback_) + " " + str.tostring(tp_) + " " + str.tostring(sl_))

            // Was there an entry?
            was_edone = false

            // If entry price reached
            if not array.get(arr_in_pos, index) and not na(array.get(arr_bi, index))
                if high >= high[bar_index - array.get(arr_bi, index)] and bar_index != array.get(arr_bi, index)
                    array.set(arr_in_pos, index, true)
                    was_edone := true

            // If we're in a position
            if array.get(arr_in_pos, index) and bar_index != array.get(arr_bi, index) and not was_edone
                low_sl = low[bar_index - array.get(arr_bi, index)] * (1 - sl_ / 100)
                high_ep = high[bar_index - array.get(arr_bi, index)]
                high_tp = high_ep * (1 + tp_ / 100)

                amount = 100

                // Stop loss
                if low <= low_sl
                    array.set(arr_in_pos, index, false)
                    array.set(arr_wonlost, index, array.get(arr_wonlost, index) + "0")
                    array.set(arr_profit, index, array.get(arr_profit, index) - math.abs(amount / high_ep * low_sl - amount) - com / 100 * amount * 2)
                    array.set(arr_bi, index, na)
                // Take profit
                if high >= high_tp
                    array.set(arr_in_pos, index, false)
                    array.set(arr_wonlost, index, array.get(arr_wonlost, index) + "1")
                    array.set(arr_profit, index, array.get(arr_profit, index) + math.abs(amount / high_ep * high_tp - amount) - com / 100 * amount * 2)
                    array.set(arr_bi, index, na)

            // Entry condition
            cond = barstate.isconfirmed and close < low[1] and high[1] < high[lookback_ + 1] //and not array.get(arr_in_pos, index)

            // New entry price
            if cond and not array.get(arr_in_pos, index)
                array.set(arr_bi, index, bar_index)

            // Update index
            index := index + 1

// Checking the results
var table t = na
var result_index = array.new_int(0, na)
var result_arr_winrate = array.new_float(0, na)
var result_arr_tradenum = array.new_int(0, na)
var sort_array = array.new_float(0, na)

if (barstate.islast or barstate.islastconfirmedhistory) and na(t)
    for i = 0 to array.size(arr_params) - 1
        wins = 0
        losses = 0
        arr = array.get(arr_wonlost, i)
        for j = 0 to str.length(arr) - 1
            str_ = str.substring(arr, j, j + 1)
            if str_ == "0"
                losses := losses + 1
            if str_ == "1"
                wins := wins + 1
        // Push percentage profitable trades
        perc_profit = math.round(wins / (wins + losses) * 100, 2)
        array.push(result_arr_winrate, perc_profit)
        // Push number of trades
        trade_num = str.length(array.get(arr_wonlost, i))
        array.push(result_arr_tradenum, trade_num)
        // Push index
        array.push(result_index, i)
        // For combined sorting
        array.push(sort_array, (imp_netprofit ? array.get(arr_profit, i) : 1) * (imp_perc_profit ? perc_profit : 1) * (imp_numtrades ? trade_num : 1))

    // Sort
    sortArr(array.copy(sort_array), result_index)

    t := table.new(columns=6, rows=13, bgcolor=color.white, border_color=color.new(color.blue, 0), border_width=1, frame_color=color.new(color.blue, 0), frame_width=1, position=table_pos_)

    table.cell(t, 0, 0, "% Profitable" + (imp_perc_profit ? " ↓" : ""), bgcolor=imp_perc_profit ? color.rgb(23, 18, 25) : color.white, text_color=imp_perc_profit ? color.white : color.black, text_size=table_font_size_)
    table.cell(t, 1, 0, "Net Profit" + (imp_netprofit ? " ↓" : ""), bgcolor=imp_netprofit ? color.rgb(23, 18, 25) : color.white, text_color=imp_netprofit ? color.white : color.black, text_size=table_font_size_)
    table.cell(t, 2, 0, "# of trades" + (imp_numtrades ? " ↓" : ""), bgcolor=imp_numtrades ? color.rgb(23, 18, 25) : color.white, text_color=imp_numtrades ? color.white : color.black, text_size=table_font_size_)
    table.cell(t, 3, 0, "Lookback", text_size=table_font_size_)
    table.cell(t, 4, 0, "Take Profit %", text_size=table_font_size_)
    table.cell(t, 5, 0, "Stop Loss %", text_size=table_font_size_)

    counter = 0
    forloop_counter = math.min(array.size(result_index) - 1, 10)
    for i = 0 to forloop_counter
        i_ = array.get(result_index, i)
        params_ = str.split(array.get(arr_params, i_), " ")
        col_ = color.new(color.blue, 75)
        table.cell(t, 0, i + 1, str.tostring(array.get(result_arr_winrate, i_)) + "%", bgcolor=col_, text_size=table_font_size_)
        table.cell(t, 1, i + 1, str.tostring(math.round(array.get(arr_profit, i_), 2)) + "$", bgcolor=col_, text_size=table_font_size_)
        table.cell(t, 2, i + 1, str.tostring(array.get(result_arr_tradenum, i_)), bgcolor=col_, text_size=table_font_size_)
        table.cell(t, 3, i + 1, array.get(params_, 0), bgcolor=col_, text_size=table_font_size_)
        table.cell(t, 4, i + 1, array.get(params_, 1), bgcolor=col_, text_size=table_font_size_)
        table.cell(t, 5, i + 1, array.get(params_, 2), bgcolor=col_, text_size=table_font_size_)
        counter := counter + 1

    // Warn if timeframe is <= 10 minutes
    if timeframe.in_seconds(timeframe.period) <= 600
        table.cell(t, 0, forloop_counter + 2, "Timeframe might be too low", bgcolor=color.orange, text_size=table_font_size_, tooltip="Selected timeframe might be too low and cause an error")
        table.merge_cells(t, 0, forloop_counter + 2, 5, forloop_counter + 2)

// Strategy
var int bi = na
var int pos_bi = na

// Buy condition
cond = barstate.isconfirmed and close < low[1] and high[1] < high[lookback + 1] and strategy.position_size == 0

// Stop loss, Take profit
if strategy.position_size[1] == 0 and strategy.position_size > 0 and bar_index != bi
    strategy.exit("TP/SL", "Long", stop=low[bar_index - bi] * (1 - sl / 100), limit=high[bar_index - bi] * (1 + tp / 100))
    pos_bi := bar_index

// Buy
if cond
    strategy.order("Long", strategy.long, stop=high)
    bi := bar_index

// Box
if strategy.position_size[1] != 0 and strategy.position_size == 0
    tn = strategy.closedtrades - 1
    penp = strategy.closedtrades.entry_price(tn)
    pexp = strategy.closedtrades.exit_price(tn)
Published by ChaoZhang on the FMZ strategy square · last modified 2023-10-17. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Architecture-Breakthrough-Backtesting-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- 5 Day Moving Average Channel Breakout Strategy Combined With Mileage ConceptPine Script · Breakout · 1d
- ATR Trailing Stops StrategyPine Script · Breakout · 1h
- ATR Trend Breakout StrategyPine Script · Breakout · 1d
- Adaptive Bollinger Breakout with Moving Average Quantitative Strategy SystemPine Script · Breakout · 1h
- Adaptive Channel Breakout StrategyPine Script · Breakout · 1d
- Adaptive Multi Period Trading Strategy Based on Wave Trend Momentum BreakoutPine Script · Breakout · 2h