Strategy vault / Trend following
ATR Fusion Trend Optimization Model Strategy
This strategy is an advanced trend following system based on ATR and Fibonacci weighted averages. It combines volatility analysis across multiple timeframes with Fibonacci weighted averaging to create a responsive…
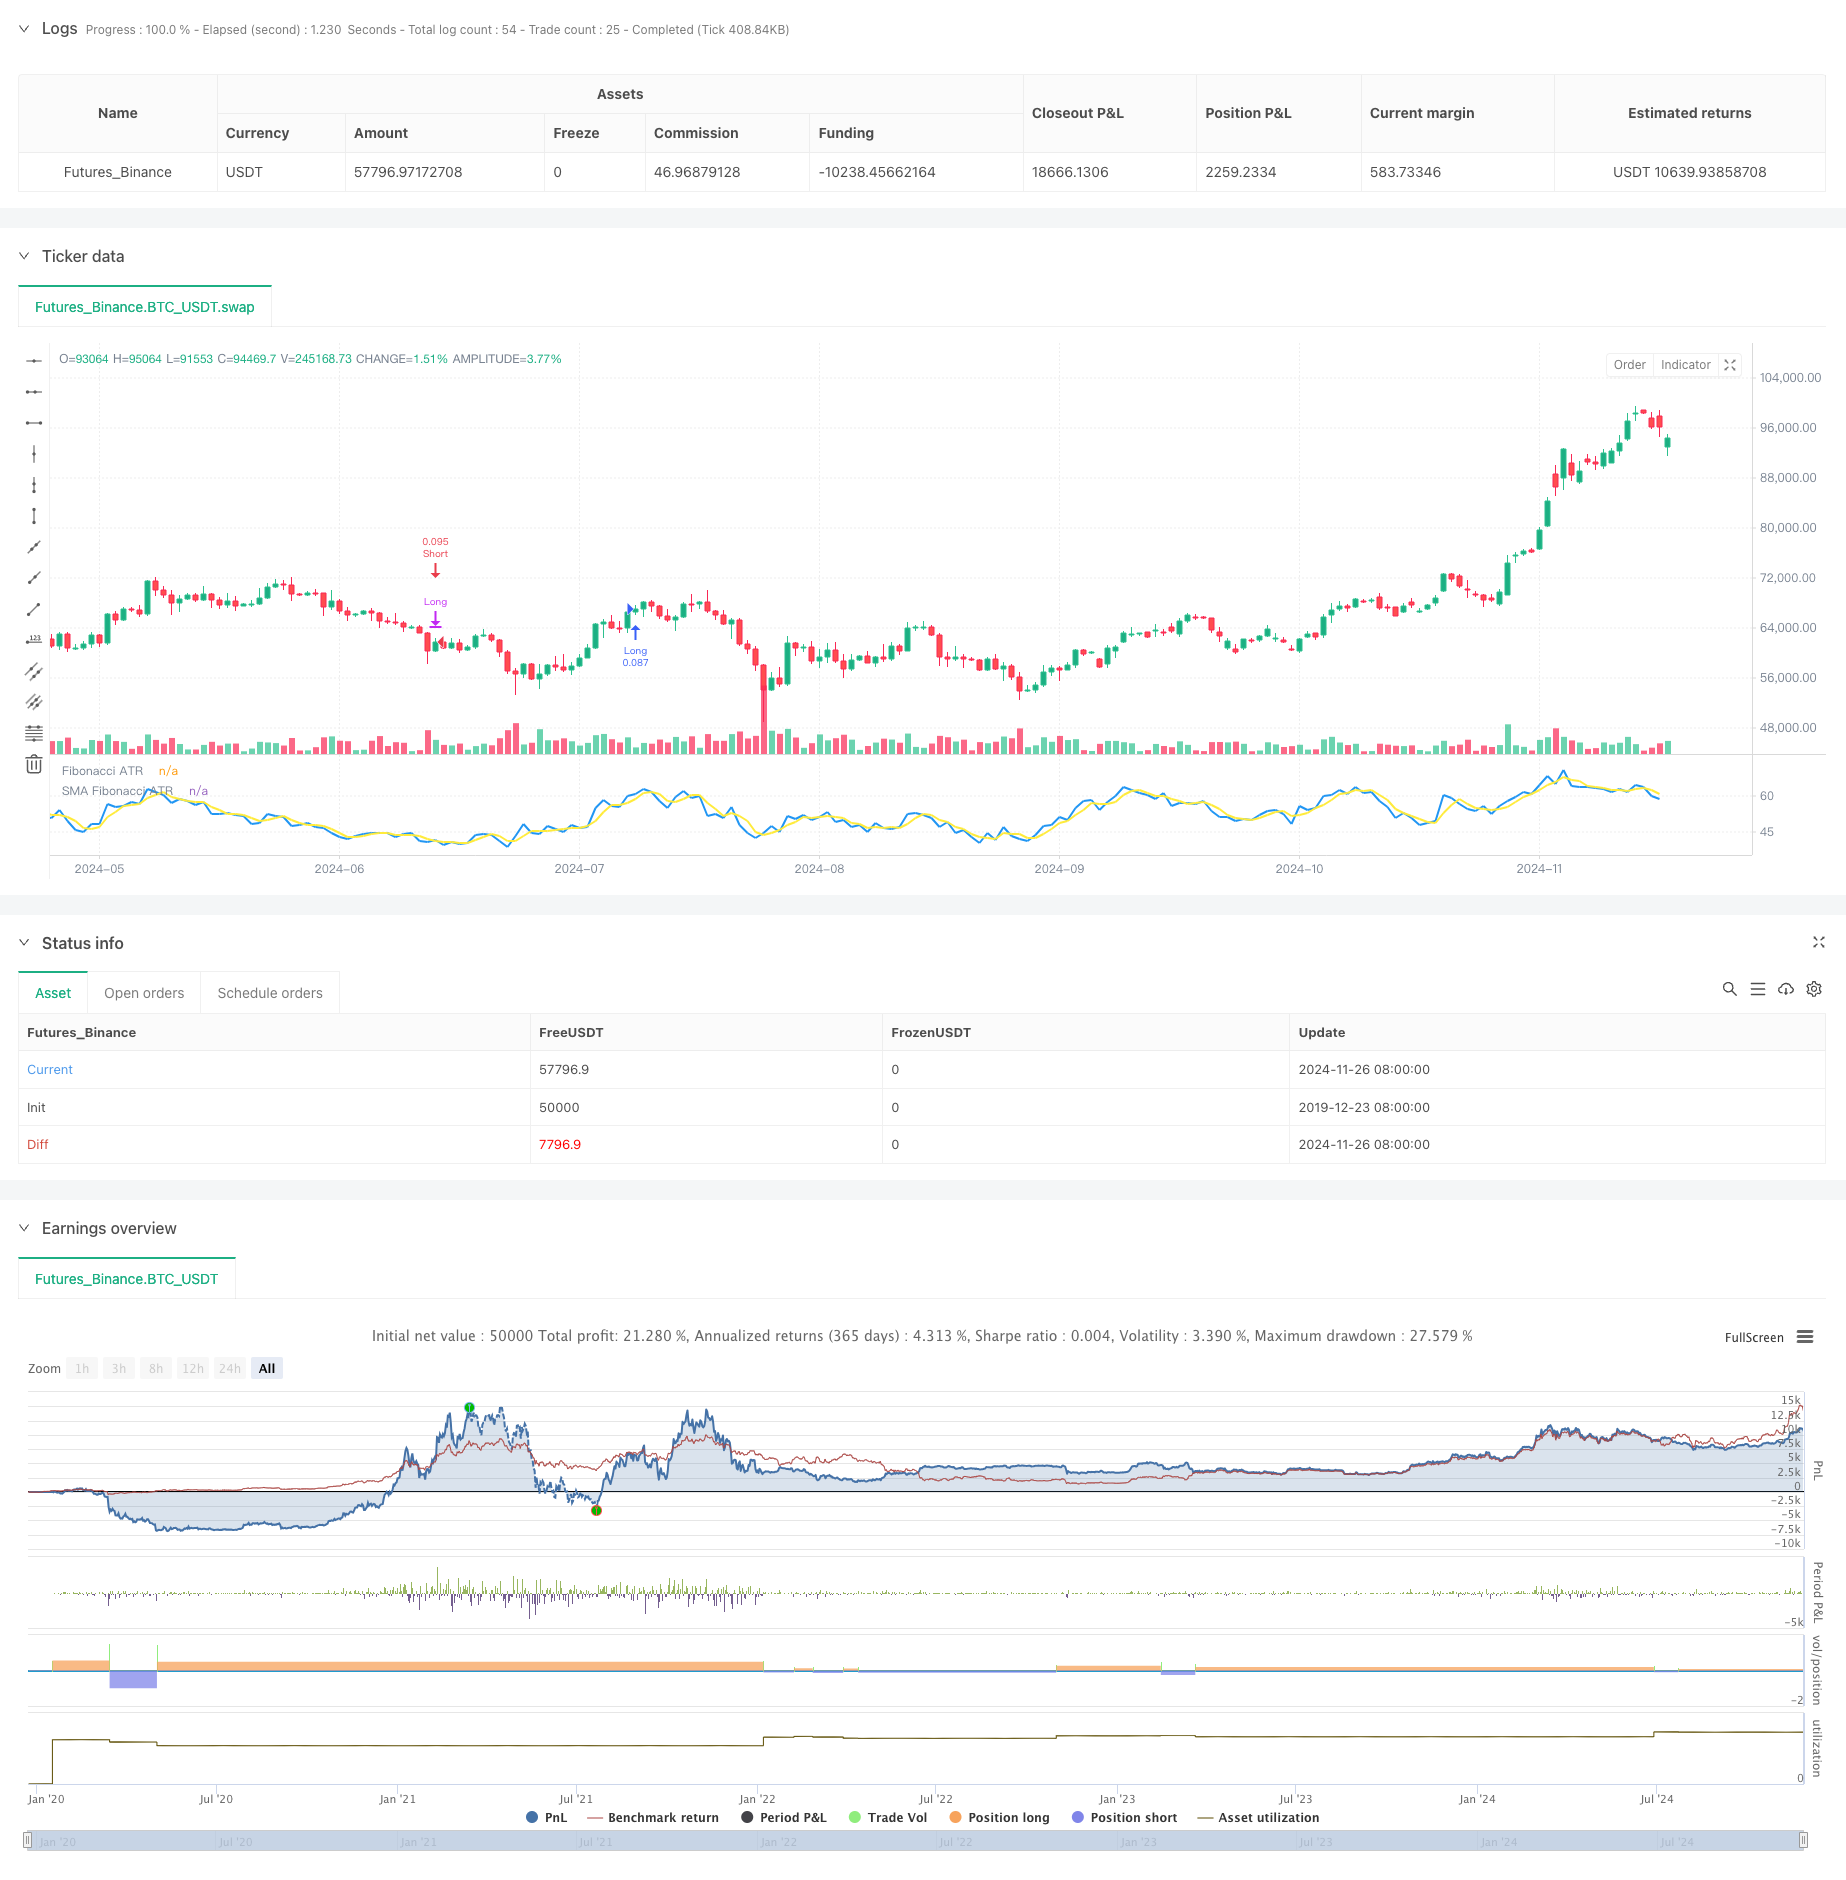
Overview
This strategy is an advanced trend following system based on ATR and Fibonacci weighted averages. It combines volatility analysis across multiple timeframes with Fibonacci weighted averaging to create a responsive and adaptive trading model. The core strength lies in its dynamic weight allocation for better trend capture and precise profit-taking using ATR.
Strategy Principle
The strategy employs a multi-layered technical indicator approach: It first calculates True Range (TR) and Buying Pressure (BP), then computes pressure ratios based on Fibonacci sequence periods (8,13,21,34,55). Different weights (5,4,3,2,1) are applied to different periods to construct a weighted average, further smoothed by a 3-period SMA. Trading signals are triggered by SMA crossovers with preset thresholds (58.0 and 42.0), and a four-step profit-taking mechanism is designed using ATR.
Strategy Advantages
- Multi-dimensional analysis: Combines data from multiple timeframes for a comprehensive market perspective
- Dynamic adaptation: Adapts to market volatility through ATR, enhancing strategy stability
- Intelligent profit-taking: Four-step profit mechanism flexibly adjusts to different market conditions
- Controlled risk: Clear entry and exit conditions reduce subjective judgment risks
- Systematic operation: Clear strategy logic, easy to quantify and backtest
Strategy Risks
- Parameter sensitivity: Multiple thresholds and weight parameters require careful adjustment
- Lag risk: SMA smoothing may cause signal delays
- Market environment dependence: May generate false signals in ranging markets
- Parameter fitting: Parameters need optimization for different market conditions Solution: Recommend thorough parameter optimization and backtesting, with dynamic parameter adjustment for different market phases.
Strategy Optimization Directions
- Parameter adaptation: Develop adaptive parameter adjustment mechanisms
- Market filtering: Add market environment recognition module
- Signal optimization: Introduce auxiliary confirmation indicators
- Risk control enhancement: Add dynamic stop-loss and position management
- Drawdown control: Implement maximum drawdown limits
Summary
This strategy integrates ATR and Fibonacci weighted averages to build a comprehensive trend following system. Its strengths lie in multi-dimensional analysis and dynamic adaptation capabilities, while attention must be paid to parameter optimization and market environment filtering. Through continuous optimization and risk control enhancement, the strategy can maintain stable performance across different market conditions.
Source Pine Script
/*backtest
start: 2019-12-23 08:00:00
end: 2024-11-27 00:00:00
period: 1d
basePeriod: 1d
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This Pine Script™ code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © PresentTrading

// The Fibonacci ATR Fusion Strategy is an advanced trading methodology that uniquely integrates Fibonacci-based weighted averages with the Average True Range (ATR) to
// identify and exploit significant market trends. Unlike traditional strategies that rely on single indicators or fixed parameters, this approach leverages multiple timeframes and
// dynamic volatility measurements to enhance accuracy and adaptability.

//@version=5
strategy("Fibonacci ATR Fusion - Strategy [presentTrading]", overlay=false, precision=3, commission_value= 0.1, commission_type=strategy.commission.percent, slippage= 1, currency=currency.USD, default_qty_type = strategy.percent_of_equity, default_qty_value = 10, initial_capital=10000)

// Calculate True High and True Low
tradingDirection = input.string(title="Trading Direction", defval="Both", options=["Long", "Short", "Both"])

// Trading Condition Thresholds
long_entry_threshold = input.float(58.0, title="Long Entry Threshold")
short_entry_threshold = input.float(42.0, title="Short Entry Threshold")
long_exit_threshold = input.float(42.0, title="Long Exit Threshold")
short_exit_threshold = input.float(58.0, title="Short Exit Threshold")

// Enable or Disable 4-Step Take Profit
useTakeProfit = input.bool(false, title="Enable 4-Step Take Profit")

// Take Profit Levels (as multiples of ATR)
tp1ATR = input.float(3.0, title="Take Profit Level 1 ATR Multiplier")
tp2ATR = input.float(8.0, title="Take Profit Level 2 ATR Multiplier")
tp3ATR = input.float(14.0, title="Take Profit Level 3 ATR Multiplier")

// Take Profit Percentages
tp1_percent = input.float(12.0, title="TP Level 1 Percentage", minval=0.0, maxval=100.0)
tp2_percent = input.float(12.0, title="TP Level 2 Percentage", minval=0.0, maxval=100.0)
tp3_percent = input.float(12.0, title="TP Level 3 Percentage", minval=0.0, maxval=100.0)

true_low = math.min(low, close[1])
true_high = math.max(high, close[1])

// Calculate True Range
true_range = true_high - true_low

// Calculate BP (Buying Pressure)
bp = close - true_low

// Calculate ratios for different periods
calc_ratio(len) =>
    sum_bp = math.sum(bp, len)
    sum_tr = math.sum(true_range, len)
    100 * sum_bp / sum_tr

// Calculate weighted average of different timeframes
weighted_avg = (5 * calc_ratio(8) + 4 * calc_ratio(13) + 3 * calc_ratio(21) + 2 * calc_ratio(34) + calc_ratio(55)) / (5 + 4 + 3 + 2 + 1)
weighted_avg_sma = ta.sma(weighted_avg,3)

// Plot the indicator
plot(weighted_avg, "Fibonacci ATR", color=color.blue, linewidth=2)
plot(weighted_avg_sma, "SMA Fibonacci ATR", color=color.yellow, linewidth=2)

// Define trading conditions
longCondition = ta.crossover(weighted_avg_sma, long_entry_threshold)  // Enter long when weighted average crosses above threshold
shortCondition = ta.crossunder(weighted_avg_sma, short_entry_threshold) // Enter short when weighted average crosses below threshold
longExit = ta.crossunder(weighted_avg_sma, long_exit_threshold)
shortExit = ta.crossover(weighted_avg_sma, short_exit_threshold)


atrPeriod = 14
atrValue = ta.atr(atrPeriod)

if (tradingDirection == "Long" or tradingDirection == "Both")
    if (longCondition)
        strategy.entry("Long", strategy.long)
        // Set Take Profit levels for Long positions
        if useTakeProfit
            tpPrice1 = strategy.position_avg_price + tp1ATR * atrValue
            tpPrice2 = strategy.position_avg_price + tp2ATR * atrValue
            tpPrice3 = strategy.position_avg_price + tp3ATR * atrValue
            // Close partial positions at each Take Profit level
            strategy.exit("TP1 Long", from_entry="Long", qty_percent=tp1_percent, limit=tpPrice1)
            strategy.exit("TP2 Long", from_entry="Long", qty_percent=tp2_percent, limit=tpPrice2)
            strategy.exit("TP3 Long", from_entry="Long", qty_percent=tp3_percent, limit=tpPrice3)
    if (longExit)
        strategy.close("Long")

if (tradingDirection == "Short" or tradingDirection == "Both")
    if (shortCondition)
        strategy.entry("Short", strategy.short)
        // Set Take Profit levels for Short positions
        if useTakeProfit
            tpPrice1 = strategy.position_avg_price - tp1ATR * atrValue
            tpPrice2 = strategy.position_avg_price - tp2ATR * atrValue
            tpPrice3 = strategy.position_avg_price - tp3ATR * atrValue
            // Close partial positions at each Take Profit level
            strategy.exit("TP1 Short", from_entry="Short", qty_percent=tp1_percent, limit=tpPrice1)
            strategy.exit("TP2 Short", from_entry="Short", qty_percent=tp2_percent, limit=tpPrice2)
            strategy.exit("TP3 Short", from_entry="Short", qty_percent=tp3_percent, limit=tpPrice3)
    if (shortExit)
strategy.close("Short")Published by ChaoZhang on the FMZ strategy square · last modified 2024-11-28. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/ATR-Fusion-Trend-Optimization-Model-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Multi Period Trend Confirmation Dynamic Risk Control Quantitative Trading StrategyPine Script · Trend following · 1h
- Dynamic WaveTrend and Fibonacci Integrated Quantitative Trading StrategyPine Script · Trend following · 1h
- Multi Level Fibonacci EMA Trend Following StrategyPine Script · Trend following · 1d
- Multi Period Trend Following and Volume Analysis Adaptive Risk StrategyPine Script · Trend following · 1d
- Enhanced Fibonacci Trend Following and Risk Management StrategyPine Script · Trend following · 3h
- ATR and Moving Average Crossover Hybrid StrategyPine Script · Trend following · 1h