Strategy vault / Mean reversion
Automated Trading Strategy Based on RSI Overbought and Oversold Levels
This strategy automatically executes trades based on the overbought and oversold levels of the Relative Strength Index (RSI). It goes long when RSI is below the user-defined oversold level and goes short when RSI is…
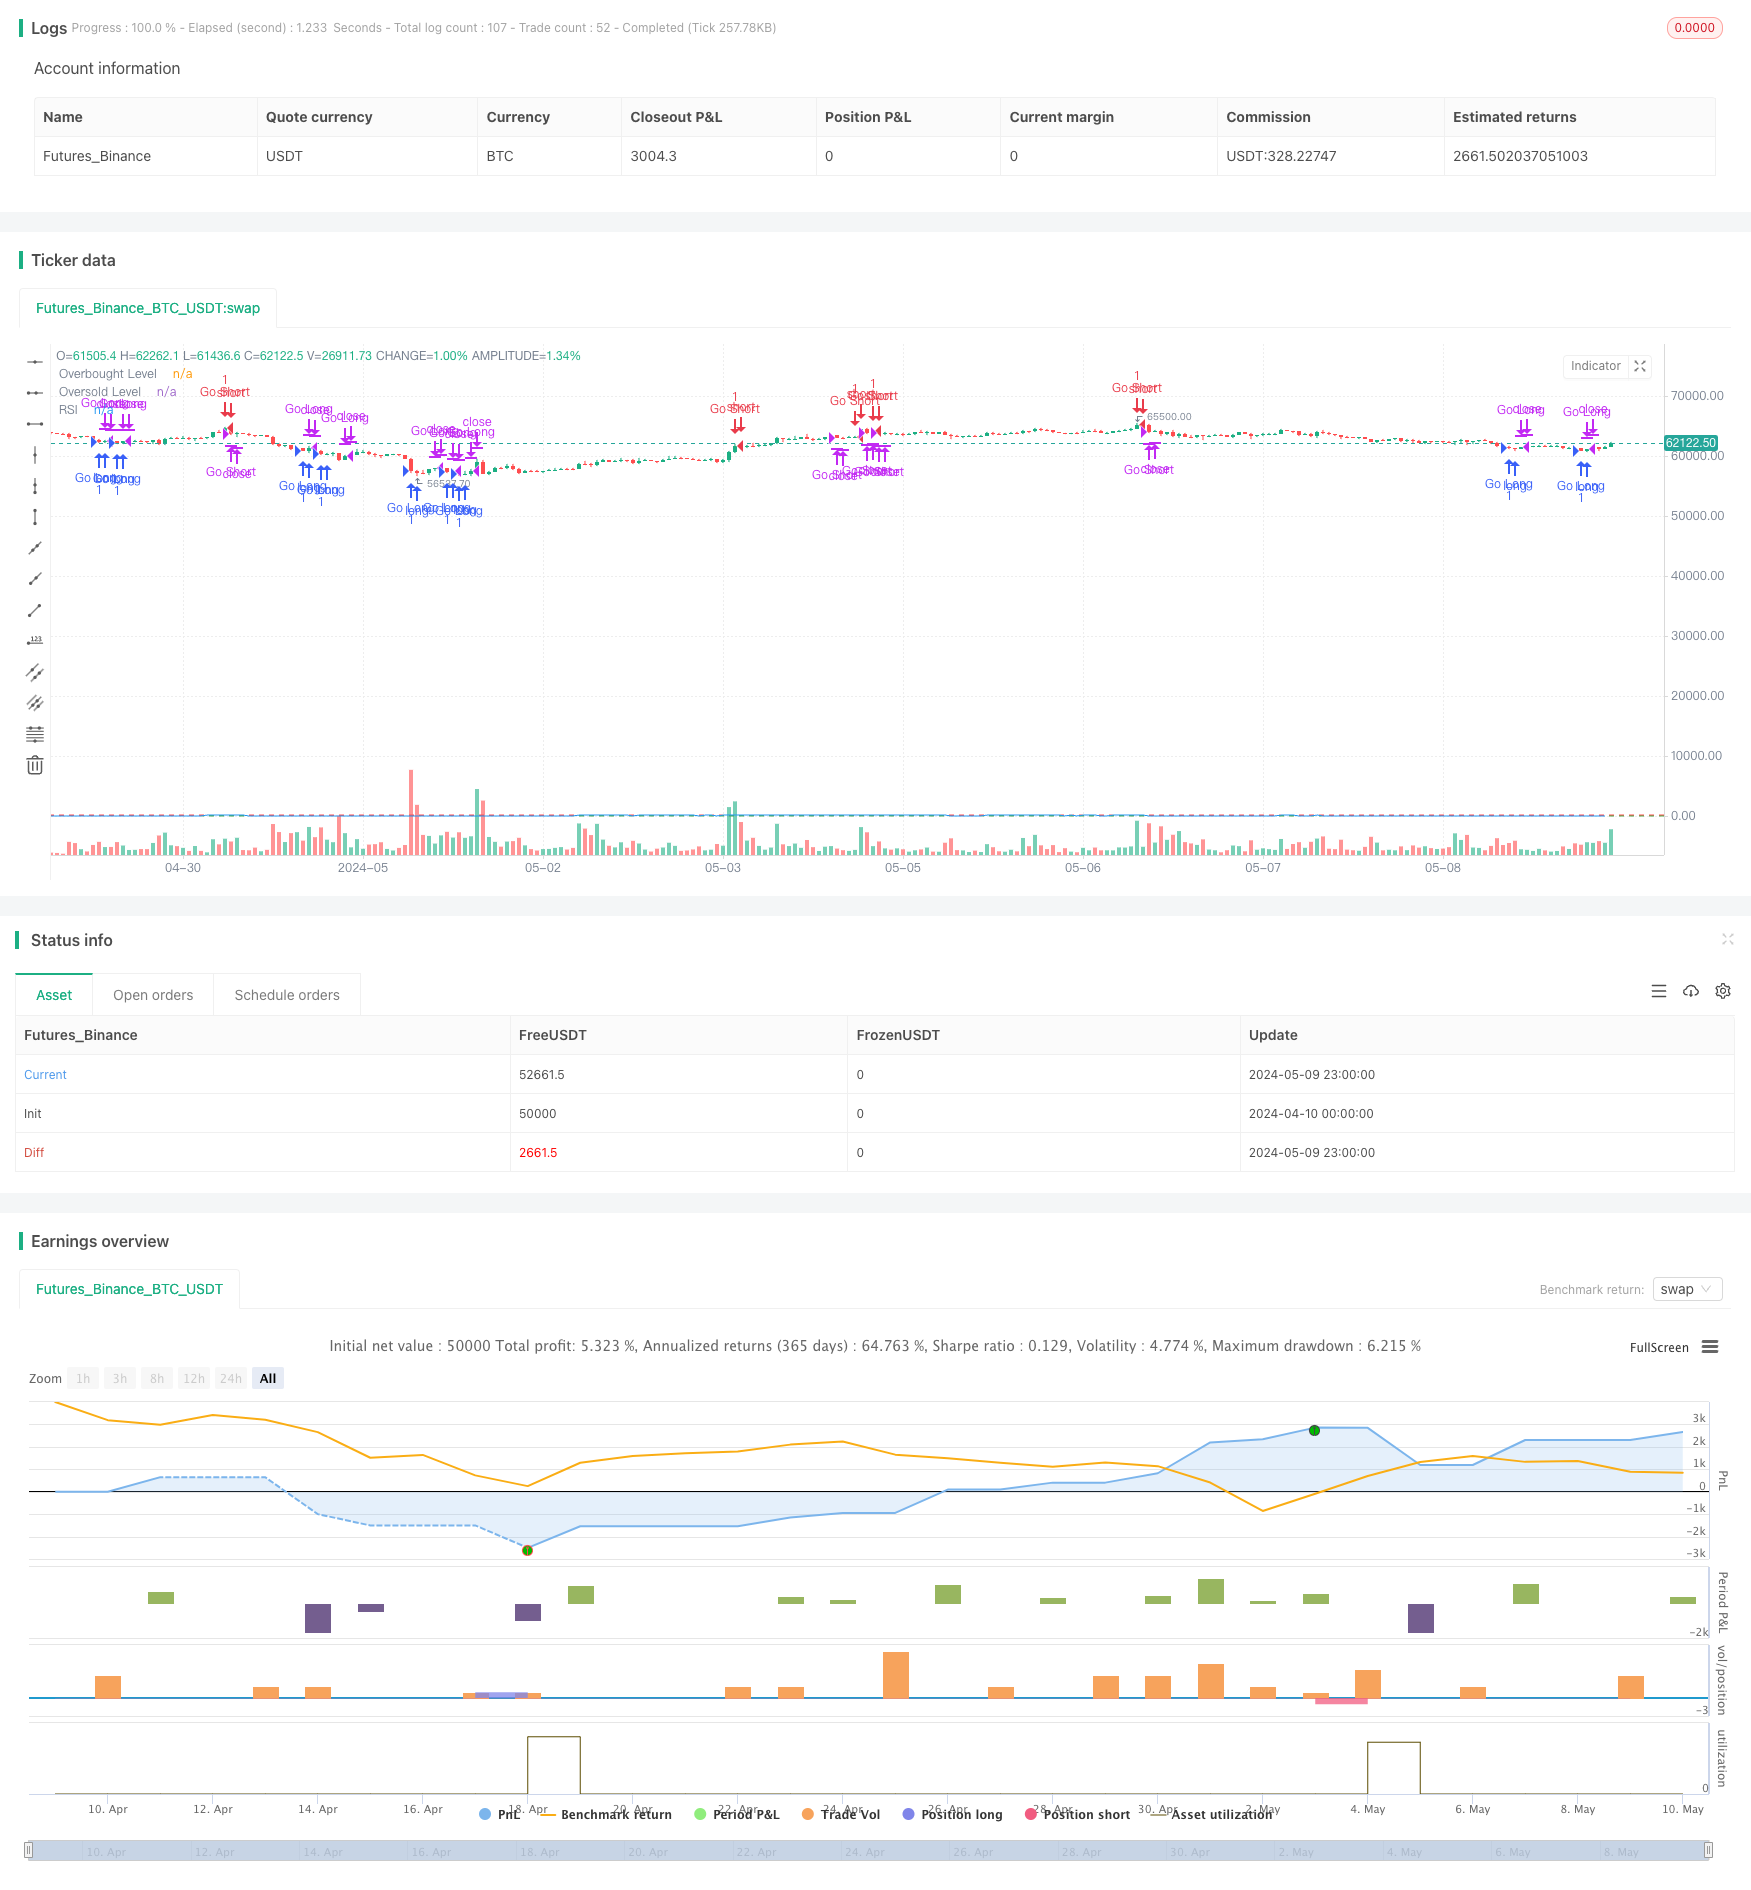
Overview
This strategy automatically executes trades based on the overbought and oversold levels of the Relative Strength Index (RSI). It goes long when RSI is below the user-defined oversold level and goes short when RSI is above the user-defined overbought level. Positions are automatically closed after a certain holding period. All parameters can be set by the user, including the RSI period, overbought and oversold levels, and holding time.
Strategy Principles
The Relative Strength Index (RSI) is a momentum indicator that measures the magnitude of recent price changes. It ranges from 0 to 100. Traditionally, an RSI above 70 is considered overbought, and below 30 is considered oversold. This strategy utilizes these principles, buying when RSI is oversold and selling when it is overbought, attempting to capture short-term price reversals. To control risk, the strategy automatically closes positions after a certain holding period.
Strategy Advantages
Simplicity: The strategy is based on the classic RSI technical indicator, with a clear and easy-to-understand logic, making it simple to implement.
Parameter flexibility: Users can flexibly set parameters such as the RSI period, overbought and oversold thresholds, and holding time according to their preferences and market characteristics.
High degree of automation: The strategy can automatically monitor RSI levels and execute opening and closing trades, reducing human intervention and emotional influence.
Adaptability: By adjusting parameters, the strategy can be applied to different market environments and trading instruments.
Strategy Risks
Parameter optimization difficulty: The optimal parameter combination may vary greatly under different market conditions, requiring extensive backtesting and analysis to find suitable parameters.
Market trend risk: When the market exhibits a strong unilateral trend, the strategy may frequently trade and lead to losses.
False signal risk: RSI may generate false signals, causing the strategy to make incorrect trades.
Black swan events: The strategy has limited adaptability to extreme market conditions and may suffer significant losses in the face of black swan events.
Strategy Optimization Directions
Combining with other indicators: Relying solely on RSI may not be robust enough. Consider combining with other technical indicators such as moving averages or MACD to improve signal reliability.
Introducing stop-loss and take-profit: Incorporate stop-loss and take-profit mechanisms into the strategy to better control the risk and return of individual trades.
Dynamic parameter adjustment: Dynamically adjust parameters such as the RSI period and overbought/oversold thresholds based on changes in market conditions to make the strategy more adaptive.
Market state filtering: Filter out unfavorable market states for trading based on indicators such as market volatility and trend strength to improve the strategy's robustness.
Summary
This strategy utilizes the overbought and oversold principles of the RSI indicator to construct a simple and easy-to-understand automated trading system. Users can flexibly set various parameters, and the strategy automatically executes trades. However, the strategy also faces issues such as difficulty in parameter optimization, trend risk, and false signal risk. In the future, optimization measures such as introducing other indicators, stop-loss and take-profit mechanisms, dynamic parameter adjustment, and market state filtering can be considered to enhance the strategy's robustness and profitability.
Source Pine Script
/*backtest
start: 2024-04-10 00:00:00
end: 2024-05-10 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("Dougie Trades RSI Strategy V1", overlay=true)

// Inputs for strategy
rsiPeriod = input.int(14, title="RSI Period")
overbought = input.int(70, title="Overbought Level", minval=0, maxval=100)
oversold = input.int(30, title="Oversold Level", minval=0, maxval=100)
exitAfterMinutes = input.int(60, title="Exit After X Minutes", minval=1)

// Calculate RSI
rsi = ta.rsi(close, rsiPeriod)

// Define long and short conditions based on RSI
longCondition = rsi < oversold
shortCondition = rsi > overbought

var float entryTime = na

// Execute trades and track entry time
if (longCondition)
    strategy.entry("Go Long", strategy.long)
    entryTime := time
if (shortCondition)
    strategy.entry("Go Short", strategy.short)
    entryTime := time

// Exit logic after 'x' minutes
if (not na(entryTime) and (time - entryTime) / 60000 >= exitAfterMinutes)
    strategy.close("Go Long")
    strategy.close("Go Short")
    entryTime := na  // Reset entry time after exit

// Plotting RSI and thresholds
plot(rsi, title="RSI", color=color.blue)
hline(overbought, "Overbought Level", color=color.red)
hline(oversold, "Oversold Level", color=color.green)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-05-11. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Automated-Trading-Strategy-Based-on-RSI-Overbought-and-Oversold-Levels.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ATR and EMA based Dynamic Take Profit and Stop Loss Adaptive StrategyPine Script · Mean reversion · 1h
- Advanced 15 Minute Chart Trading Signal StrategyPine Script · Mean reversion · 3h
- BONK Multi Factor Trading StrategyPine Script · Mean reversion · 1d
- Bitcoin Futures Position Trading StrategyPine Script · Mean reversion · 1h
- Chaikin Oscillator StrategyPine Script · Mean reversion · 3h
- Customizable Non Repainting HTF MACD MFI Scalable Bot StrategyPine Script · Mean reversion · 1d