Average Stochastic Trading Strategy
This strategy is based on the Average Stochastic Oscillator for trading signal judgment and belongs to a trend following strategy. It calculates the moving average values of %K and %D of the Average Stochastic…
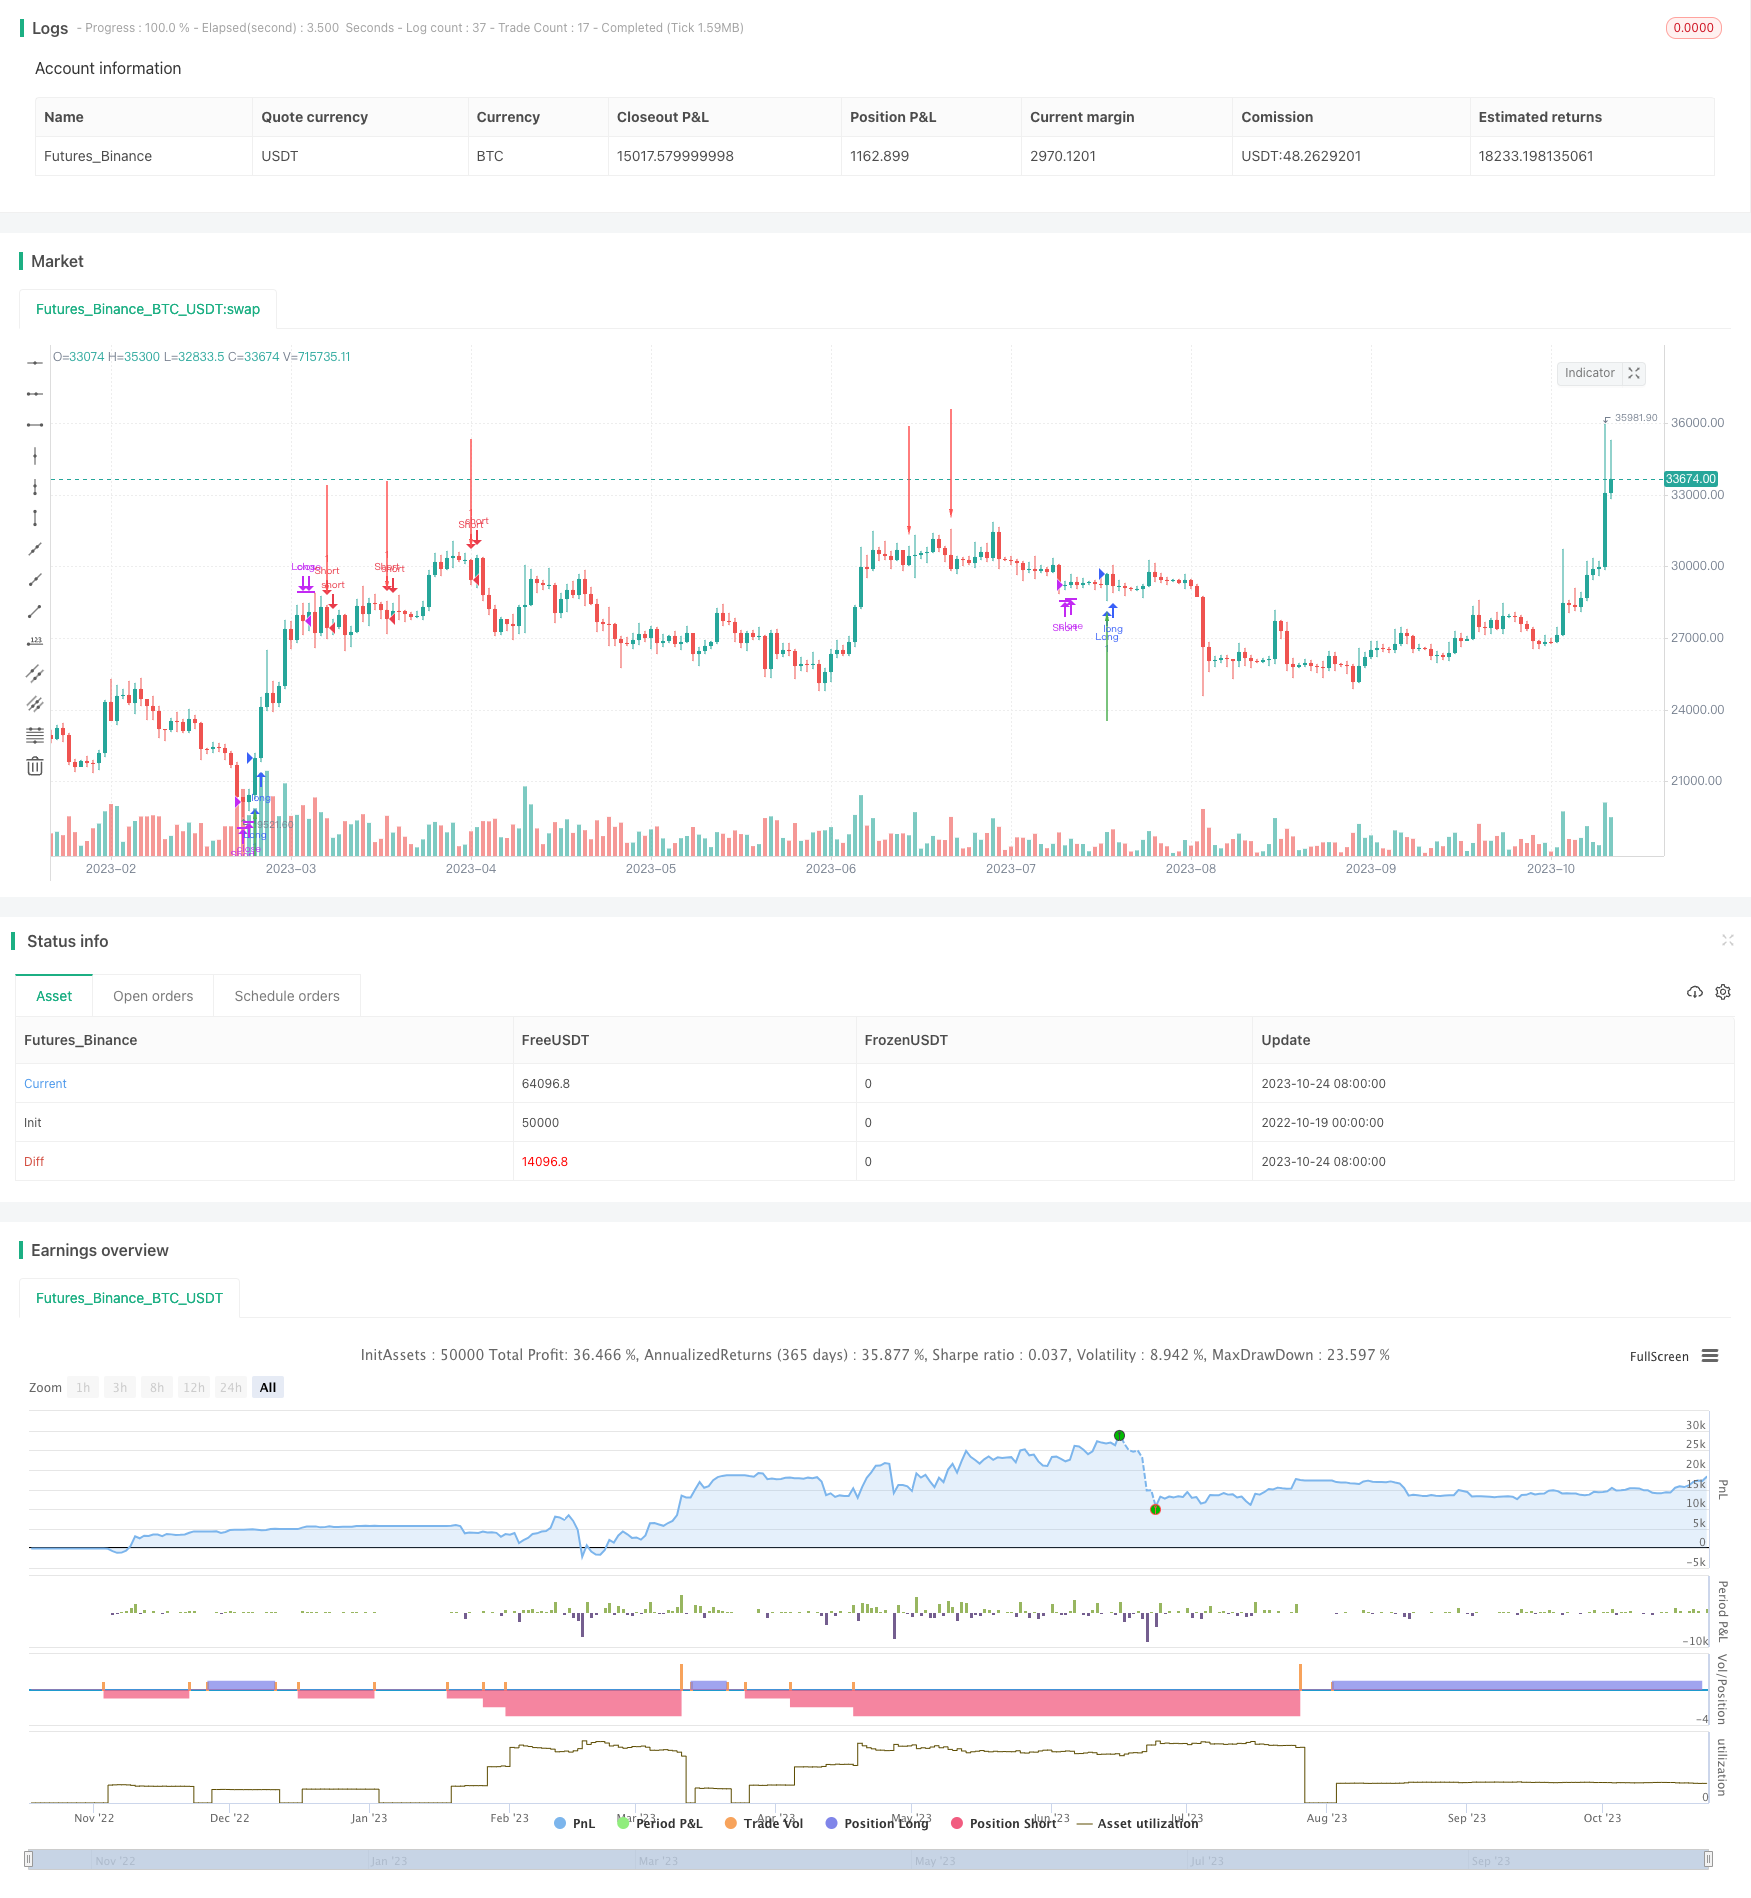
Overview
This strategy is based on the Average Stochastic Oscillator for trading signal judgment and belongs to a trend following strategy. It calculates the moving average values of %K and %D of the Average Stochastic Oscillator. When the golden cross occurs, go long. When the death cross occurs, go short. It is a typical trend following strategy.
Strategy Logic
Calculate the values of %K and %D of the Average Stochastic Oscillator. %K is the moving average of random values calculated based on closing prices over a certain period, reflecting the relative position of the current price to the highest and lowest prices over a certain period. %D is the moving average of %K used to confirm the trend.
Exponentially smooth moving average (EMA) is applied to %K and %D respectively to obtain the average values _avg_k and _avg_d of the Average Stochastic Oscillator.
Determine trading signals:
Buy signal: when _avg_k crosses over _avg_d and _avg_d < 20, go long.
Sell signal: when _avg_k crosses below _avg_d and _avg_d > 80, go short.
Position management:
Long stop loss: close long when _avg_d > 80
Short stop loss: close short when _avg_d < 20
Allow maximum 3 orders in the same direction, which is a pyramiding strategy.
Advantages
Using double moving averages to determine golden cross and death cross can effectively filter false breakouts and improve signal quality.
Applying Average Stochastic Oscillator can effectively track price trends.
Combining overbought and oversold zones helps avoid frequent trading in range-bound market.
Allowing pyramiding can gain more profit in trending market.
Stop loss strategy controls single loss.
Risks
Dual moving average trading strategies tend to generate frequent trading, which will affect profitability if transaction costs are too high.
Using fixed stop loss points may stop loss too early exiting the trend.
Too many pyramiding may enlarge the loss.
It cannot effectively determine trend reversal points and may lead to large losses when trend reverses.
Parameter periods need to be optimized because different periods can lead to very different results.
Optimization
Consider introducing trend judgment indicators to avoid counter trend trading.
Dynamically adjust stop loss points to fit the trend better.
Optimize pyramiding strategy, for example, increase position size progressively.
Incorporate other indicators to judge trend reversal and exit profit early.
Test parameter optimization separately for different products to improve adaptability.
Summary
In summary, this is a typical trend following strategy. It uses Average Stochastic Oscillator to determine trend direction and pyramids when trend occurs. The advantage is strong tracking ability suitable for trending market. But it is important to avoid counter trend trading. Further optimization can be done by introducing trend judgment, optimizing stop loss strategy, controlling pyramiding times, etc. With proper parameter selection, good tracking results can be achieved.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_int_1 | 21 | %K Length |
| v_input_int_2 | 3 | %K Smoothing |
| v_input_int_3 | 3 | %D Smoothing |
Source Pine Script
/*backtest
start: 2022-10-19 00:00:00
end: 2023-10-25 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
//1. AVG Stochastic Calculate
//1.1 AVG %K is calculated by apply EMA with smooth K period on Average of Original Stochastic %k & %d
//+ avg_k=ema((%k+%d)/2,smoothK)
//1.2 AVG %D is calculated by apply EMA with %d period on AVG %K
//+ avg_d=ema(avg_k,periodD)
//2. Parameter
//+ %K Length: 21
//+ %K Smoothing: 3
//+ %D Smoothing: 3
//+ Symbol: BTC/USDT
//+ Timeframe: M30
//+ Pyramiding: Maximum 3 orders at the same direction.
//3. Signal
//3.1 Buy Signal
//+ Entry: AVG %K crossover AVG %D and AVG %D < 20
//+ Exit: AVG %D > 80
//3.2 Sell Signal
//+ Entry: AVG %K crossunder AVG %D and AVG %D > 80
//+ Exit: AVG %D < 20
strategy(title="AVG Stochastic Strategy [M30 Backtesting]", overlay=true, pyramiding=3)
periodK = input.int(21, title="%K Length", minval=1)
smoothK = input.int(3, title="%K Smoothing", minval=1)
periodD = input.int(3, title="%D Smoothing", minval=1)
k = ta.sma(ta.stoch(close, high, low, periodK), smoothK)
d = ta.sma(k, periodD)
_avg_k=ta.ema(math.avg(k,d),smoothK)
_avg_d=ta.ema(_avg_k,periodD)
up=
   _avg_k[1]<_avg_d[1]
   and _avg_k>_avg_d
   and _avg_d<20
dn=
   _avg_k[1]>_avg_d[1]
   and _avg_k<_avg_d
   and _avg_d>80
var arr_val=0
if up
    arr_val:=1
    strategy.entry("Long", strategy.long)
if dn
    arr_val:=-1
    strategy.entry("Short", strategy.short)
if up[1] or dn[1]
    arr_val:=0
plotarrow(arr_val,title="Signal",colorup=color.green,colordown=color.red)
if _avg_d>80
    strategy.close("Long")
if _avg_d<20
    strategy.close("Short")
//EOF
Published by ChaoZhang on the FMZ strategy square · last modified 2023-10-26. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Average-Stochastic-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Bull Market Tracking SystemPine Script · Breakout · 1h
- Quantitative Strategy PSARZigZagMACDART Based on Multi Indicator CombinationPine Script · Breakout · 1m
- Quantitative Trading Price Breakthrough StrategyPine Script · Breakout · 1d
- Dual Moving Average and MACD Combination Short term Trading StrategyPine Script · Breakout · 1h
- MACD Stochastics Range Breakout StrategyPine Script · Breakout · 1d
- Momentum Breakout Strategy 428972Pine Script · Breakout · 1h