Strategy vault / Trend following
BankNifty Supertrend Trading Strategy
This is a trading strategy based on the 5-minute K-line of BankNifty using the Supertrend indicator. The strategy mainly utilizes the Supertrend indicator to identify trends and combines trading sessions and risk…
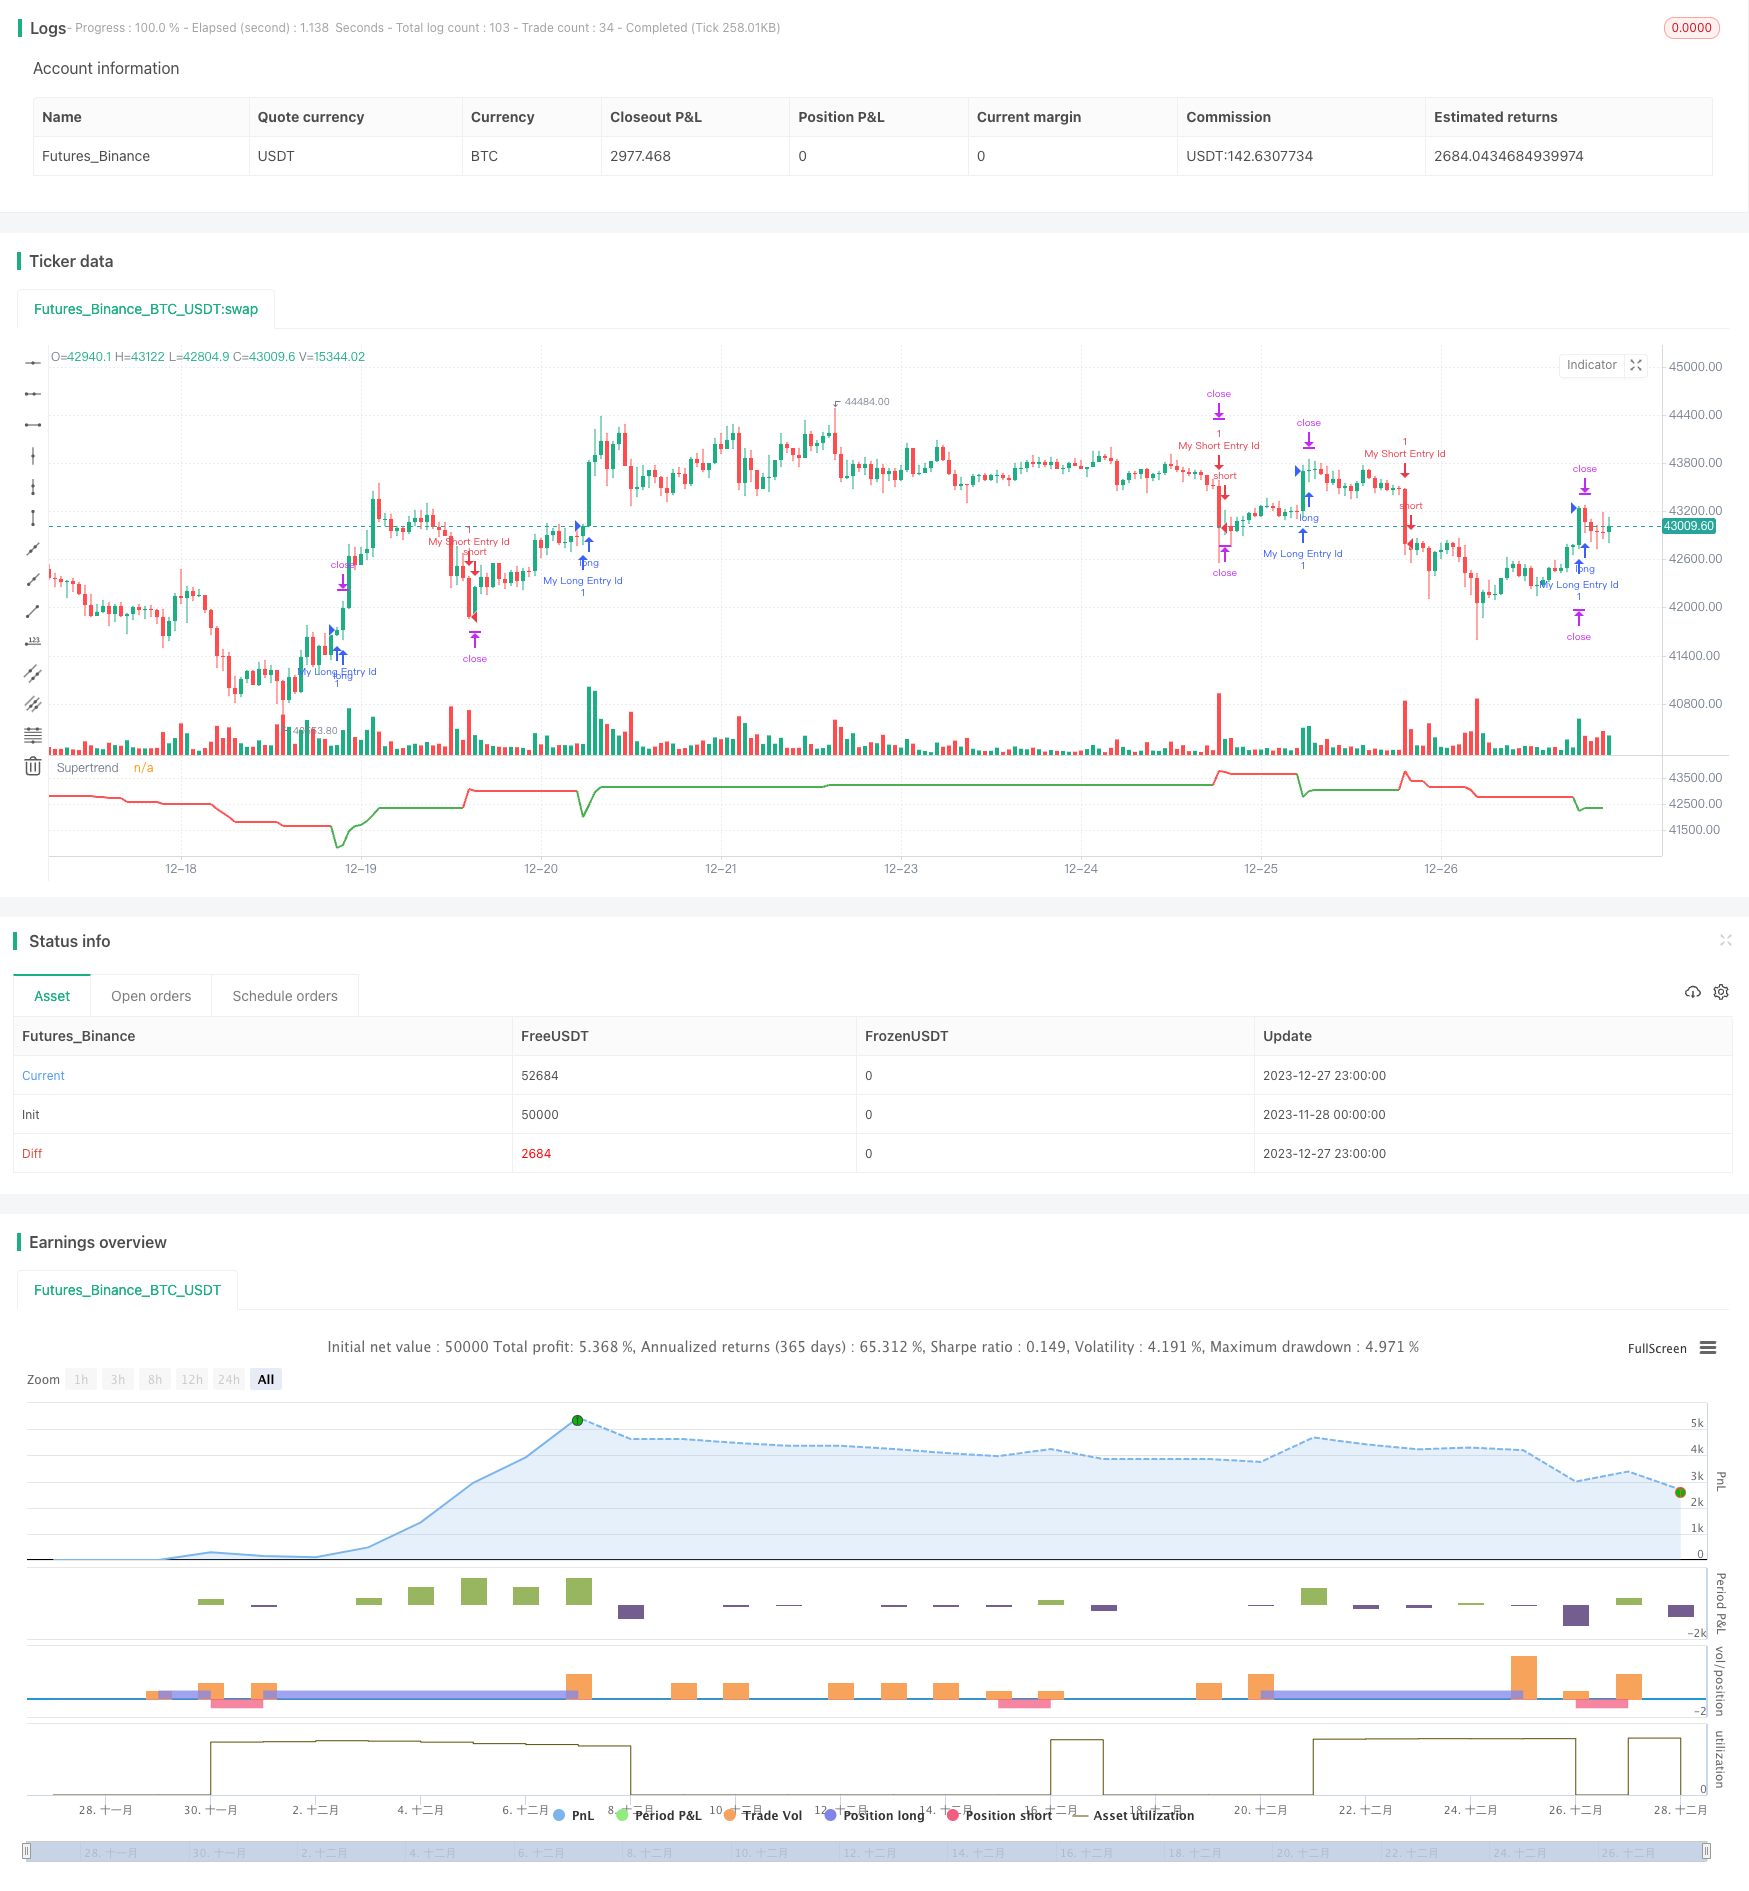
Overview
This is a trading strategy based on the 5-minute K-line of BankNifty using the Supertrend indicator. The strategy mainly utilizes the Supertrend indicator to identify trends and combines trading sessions and risk management rules to trade.
Strategy Principle
The strategy first defines input variables such as trading sessions and date ranges. The trading session is set to the Indian trading session from 9:15 am to 3:10 pm.
It then calculates the Supertrend indicator and its direction. The Supertrend indicator can identify the direction of the trend.
At the beginning of each trading session, the strategy waits for 3 candles to form before considering entering a trade. This is to filter false breakouts.
The long signal is when the Supertrend indicator direction changes from down to up; the short signal is when the Supertrend direction changes from up to down.
After entering, stop loss will be set. Both fixed stop loss points and trailing stop loss percentage can be adjusted through input variables.
At the end of the trading session, the strategy will close all open positions.
Advantages of the Strategy
This is a simple trading strategy that uses indicators to identify trends. It has the following advantages:
- Use Supertrend indicator to judge trend direction, which can effectively identify trends
- Combining trading sessions can avoid the most volatile opening and closing session
- Set trailing stop loss to lock in profits
- Many parameters can be adjusted freely through input variables, high adaptability
Risks of the Strategy
The strategy also has some risks:
- Supertrend indicator has lagging, may miss the best entry point
- Single indicator judgment is prone to be affected by false breakouts, win rate may be low
- Does not consider market trend, may diverge from the overall market
- Improper stop loss setting may lead to larger than expected losses
These risks can be reduced by optimizing parameters of the Supertrend indicator or adding other indicator judgments.
Optimization Directions
The strategy can also be optimized in the following aspects:
- Add other indicator judgments to form a combined strategy, improve stability
- Add overall market trend judgment to avoid divergence from the market
- Optimize parameters of Supertrend indicator, find the best length and factor
- Adjust stop loss strategy, like trailing stop loss along with the trend
- Test on different products, find the best match
Conclusion
In summary, this is a Supertrend indicator trading strategy based on the BankNifty 5-minute chart. It utilizes the Supertrend indicator to determine the trend direction and combines trading sessions and risk management rules to trade. Compared to complex quantitative strategies, this strategy has simple and clear rules that are easy to understand and implement. As a sample strategy, it provides a foundation and direction for future optimization and improvement. Through continuous refinement and enhancement, it is hoped that the strategy can become a reliable and profitable quantitative trading strategy.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_3 | timestamp(01 Dec 2023 23:59:59) | End Date |
| v_input_float_1 | 3 | Factor |
| v_input_1 | 0915-1510 | (?Indian Session Time)Session |
| v_input_2 | timestamp(01 Jan 2022 00:00:00) | (?Backtest Specific Range)Start Date |
| v_input_4 | 50 | (?SuperTrend Setting)ATR Length |
| v_input_5 | true | (?Delay at Session Start)Use Delay? |
| v_input_6 | 10 | Delay N numbers of candle |
| v_input_7 | true | (?Risk Management)Use Stoploss Points? |
| v_input_8 | 100 | Stop Loss Points |
| v_input_9 | true | Use Stoploss Trail? |
| v_input_float_2 | 0.1 | Stop Loss Trail% |
Source Pine Script
/*backtest
start: 2023-11-28 00:00:00
end: 2023-12-28 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("BankNifty 5min Supertrend Based Strategy, 09:15 Entry with Date Range and Risk Management")

// Session and date range input variables
session = input("0915-1510", "Session", group="Indian Session Time")
start_date = input(title="Start Date", defval=timestamp("01 Jan 2022 00:00:00"), group="Backtest Specific Range")
end_date = input(title="End Date", defval=timestamp("01 Dec 2023 23:59:59"))
atrPeriod = input(50, "ATR Length", group="SuperTrend Setting")
factor = input.float(3.0, "Factor", step=0.1)

useDelay = input(true, "Use Delay?", group="Delay at Session Start")
Delay = useDelay ? input(10, title="Delay N numbers of candle", group="Delay at Session Start") : na

useDelay_stopLoss = input(true, "Use Stoploss Points?", group="Risk Management")
stopLoss = useDelay_stopLoss ? input(100, "Stop Loss Points", group="Risk Management"): na

useDelay_stopLossPerc1 = input(true, "Use Stoploss Trail?", group="Risk Management")
stopLossPerc1 =useDelay_stopLossPerc1 ? input.float(0.1, "Stop Loss Trail%", step=0.1,maxval = 1, group="Risk Management"): na
// Check if current time is within the specified session and date range
inSession = true

[supertrend, direction] = ta.supertrend(factor, atrPeriod)

// Wait for 3 candles to form at the start of every session
var candlesFormed = 0
if inSession and not inSession[1]
    candlesFormed := 1
else if inSession and candlesFormed > 0
    candlesFormed := candlesFormed + 1
else
    candlesFormed := 0


//

// Only enter trades if 3 candles have formed at the start of the session
entryce = (ta.change(direction) < 0) or (candlesFormed >= Delay and direction < 0)
exitce = ta.change(direction) > 0
entrype = (ta.change(direction) > 0) or (candlesFormed >= Delay and direction > 0)
exitpe = ta.change(direction) < 0
var entryPrice = 0.0
if entryce and inSession
    // Enter long trade
    onePercent = strategy.position_avg_price *stopLossPerc1
    entryPrice := close
    strategy.entry("My Long Entry Id", strategy.long, comment="long" )
    // Set stop loss at x% below entry price
    strategy.exit("My Long Exit Id", "My Long Entry Id", stop=(entryPrice - stopLoss),trail_points=onePercent )

if entrype and inSession
    onePercent1 = strategy.position_avg_price *stopLossPerc1
    entryPrice := close
    // Enter short trade
    strategy.entry("My Short Entry Id", strategy.short, comment="short")
    // Set stop loss at x% above entry price
    strategy.exit("My Short Exit Id", "My Short Entry Id", stop=(entryPrice + stopLoss),trail_points=onePercent1)

// Close all trades at end of session
if not inSession and strategy.opentrades > 0
    strategy.close_all()

// Plot Supertrend with changing colors
plot(supertrend, title="Supertrend", color=direction == 1 ? color.red : color.green, linewidth=2)
Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-29. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/BankNifty-Supertrend-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Advanced Supertrend Indicator Trading Mechanism Optimization StrategyPine Script · Trend following · 1d
- Dynamic Trend Following SuperTrend Triple Enhancement StrategyPine Script · Trend following · 1d
- Heiken Ashi and Super Trend Combination StrategyPine Script · Trend following · 1d
- Multi Indicator Dynamic Trend Following Strategy Based on EMA and SMAPine Script · Trend following · 1d
- Multi Period SuperTrend Dynamic Trading StrategyPine Script · Trend following · 1d
- Precision Trading Strategy and Risk Management System Based on SuperTrend IndicatorPine Script · Trend following · 1d