Strategy vault / Trend following
BB Percentage Index Trend Fading Strategy
This strategy is based on the BB percentage index combined with RSI and MFI indicators. It makes long and short decisions by detecting price breakouts of Bollinger Bands upper and lower rail, together with RSI…
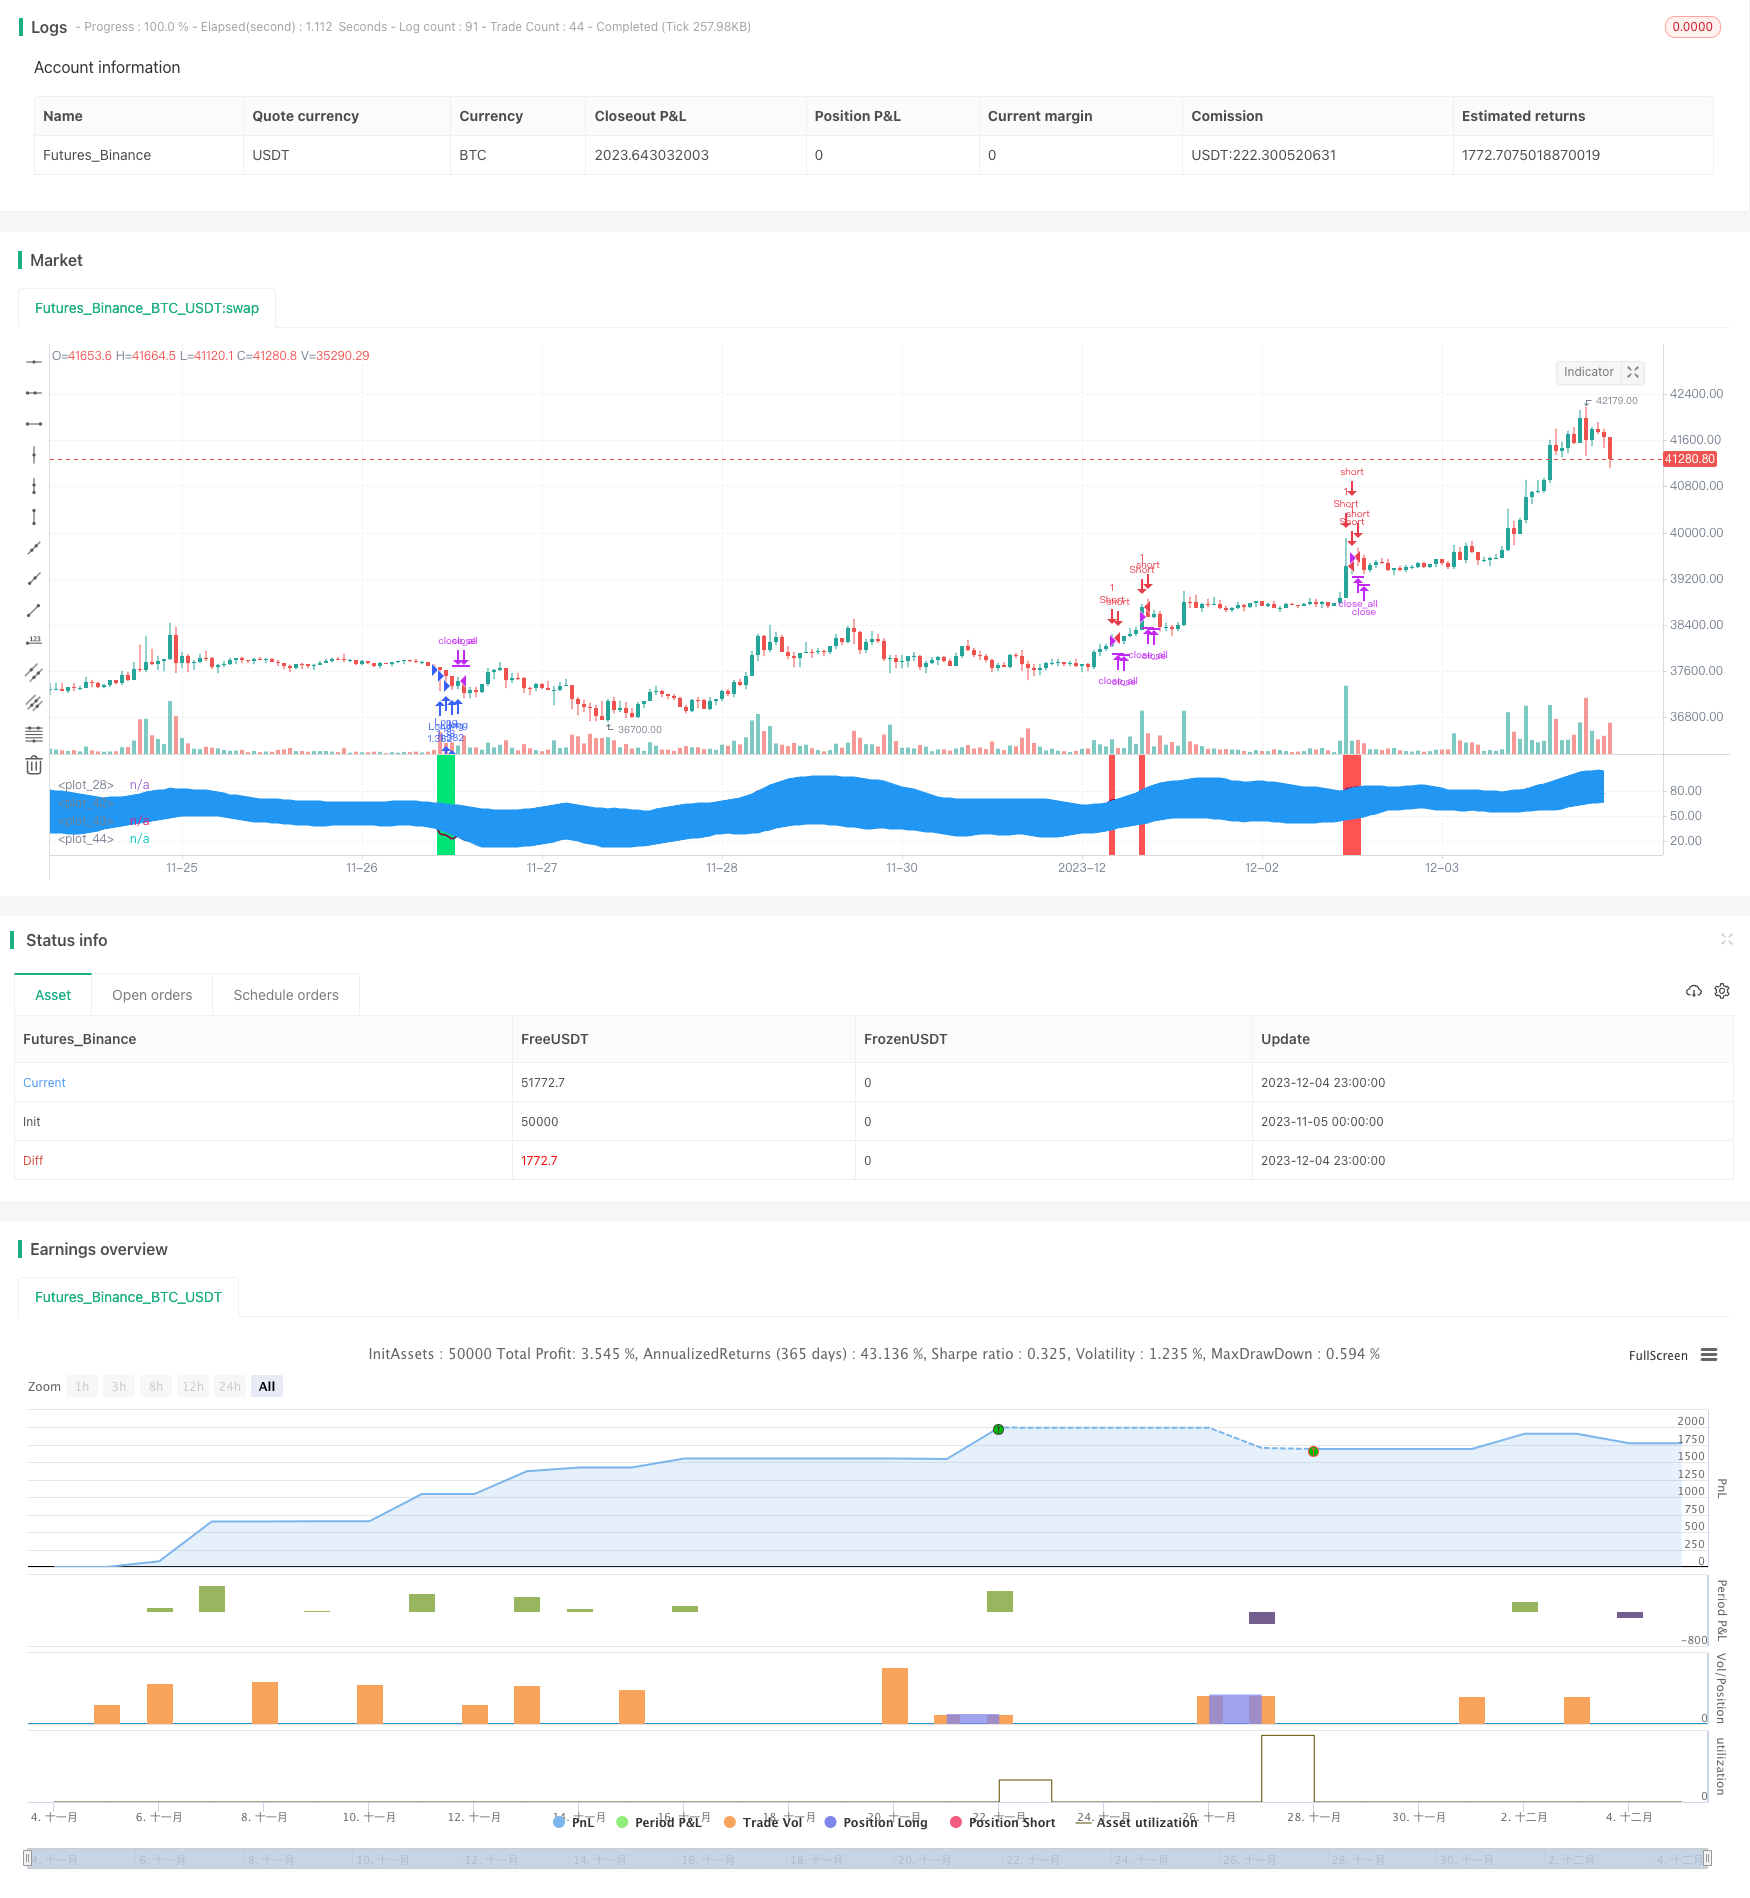
Overview
This strategy is based on the BB percentage index combined with RSI and MFI indicators. It makes long and short decisions by detecting price breakouts of Bollinger Bands upper and lower rail, together with RSI oversold/overbought signals and MFI oversold/overbought signals. It is a typical trend fading trading strategy.
Strategy Logic
- Calculate Bollinger Band Percentage (BB%). BB% represents the standard deviation of the price relative to the Bollinger middle band, which judges market direction through the Bollinger channel.
- Incorporate RSI and MFI indicators to determine overbought and oversold conditions. RSI compares the average gain and average loss over a period of time to determine overbought and oversold levels. MFI compares up volume and down volume to determine overbought and oversold levels.
- When the price breaks through the Bollinger lower rail upward, go long; when the price breaks through the Bollinger upper rail downward, go short. At the same time, use the oversold/overbought signals from RSI and MFI indicators for filtration.
Advantages
- Trend fading trading avoids market trends and reduces return fluctuations.
- The combination of multiple indicators filters signals and improves decision accuracy.
- Parameterized settings are flexible for adjusting risk-return characteristics of the strategy.
- Applicable to highly volatile instruments like commodities, forex, cryptocurrencies, etc.
Risks and Solutions
- There is a high probability of false signals from Bollinger breakouts, requiring a combination of multiple indicators for filtration.
- Breakout signal judgment requires appropriately relaxed criteria to avoid missing good opportunities.
- Adjust parameter settings to control risks, such as position sizing, raising stop loss lines, etc.
Optimization Directions
- Incorporate volatility-based stop loss mechanisms such as the ATR indicator.
- Introduce machine learning models to assist in judging breakout signal quality.
- Optimize instrument selection mechanisms to dynamically adjust participating instruments.
- Incorporate more factors like sentiment indicators, news, etc. to improve the decision framework.
Conclusion
This strategy is mainly applied to high volatility non-trending instruments. It implements trend fading trading through Bollinger channel and indicator combinations. Risk-return characteristics can be controlled by adjusting parameters. Further improvements can be made by introducing more auxiliary indicators and models to optimize decision quality, thereby achieving better strategy performance.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | true | Long |
| v_input_2 | false | Short |
| v_input_3 | 100 | Lot, % |
| v_input_4 | 1900 | From Year |
| v_input_5 | 2100 | To Year |
| v_input_6 | true | From Month |
| v_input_7 | 12 | To Month |
| v_input_8 | true | From Day |
| v_input_9 | 31 | To Day |
| v_input_10 | 14 | length |
| v_input_11 | 2 | mult |
| v_input_12 | 50 | BB Period |
| v_input_13 | true | Draw RSI? |
| v_input_14 | false | Draw MFI? |
| v_input_15 | true | Highlight Oversold/Overbought? |
Source Pine Script
/*backtest
start: 2023-11-05 00:00:00
end: 2023-12-05 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//Noro
//2018

//@version=2
strategy(title = "BB%/MFI/RSI", shorttitle = "BB%/MFI/RSI", default_qty_type = strategy.percent_of_equity, default_qty_value = 100, pyramiding = 100)

//Settings
needlong = input(true, defval = true, title = "Long")
needshort = input(false, defval = false, title = "Short")
capital = input(100, defval = 100, minval = 1, maxval = 10000, title = "Lot, %")
fromyear = input(1900, defval = 1900, minval = 1900, maxval = 2100, title = "From Year")
toyear = input(2100, defval = 2100, minval = 1900, maxval = 2100, title = "To Year")
frommonth = input(01, defval = 01, minval = 01, maxval = 12, title = "From Month")
tomonth = input(12, defval = 12, minval = 01, maxval = 12, title = "To Month")
fromday = input(01, defval = 01, minval = 01, maxval = 31, title = "From Day")
today = input(31, defval = 31, minval = 01, maxval = 31, title = "To Day")

source = hlc3
length = input(14, minval=1), mult = input(2.0, minval=0.001, maxval=50), bblength = input(50, minval=1, title="BB Period")
DrawRSI_f=input(true, title="Draw RSI?", type=bool)
DrawMFI_f=input(false, title="Draw MFI?", type=bool)
HighlightBreaches=input(true, title="Highlight Oversold/Overbought?", type=bool)

DrawMFI = (not DrawMFI_f) and (not DrawRSI_f) ? true : DrawMFI_f
DrawRSI = (DrawMFI_f and DrawRSI_f) ? false : DrawRSI_f
// RSI
rsi_s = DrawRSI ? rsi(source, length) : na
plot(DrawRSI ? rsi_s : na, color=maroon, linewidth=2)

// MFI
upper_s = DrawMFI ? sum(volume * (change(source) <= 0 ? 0 : source), length) : na
lower_s = DrawMFI ? sum(volume * (change(source) >= 0 ? 0 : source), length) : na
mf = DrawMFI ? rsi(upper_s, lower_s) : na
plot(DrawMFI ? mf : na, color=green, linewidth=2)

// Draw BB on indices
bb_s = DrawRSI ? rsi_s : DrawMFI ? mf : na
basis = sma(bb_s, length)
dev = mult * stdev(bb_s, bblength)
upper = basis + dev
lower = basis - dev
plot(basis, color=red)
p1 = plot(upper, color=blue)
p2 = plot(lower, color=blue)
fill(p1,p2, blue)

b_color = (bb_s > upper) ? red : (bb_s < lower) ? lime : na
bgcolor(HighlightBreaches ? b_color : na, transp = 0)

//Signals
up = bb_s < lower and close < open
dn = bb_s > upper and close > open
size = strategy.position_size
lp = size > 0 and close > open
sp = size < 0 and close < open
exit = (up == false and dn == false) and (lp or sp)

//Trading
lot = strategy.position_size == 0 ? strategy.equity / close * capital / 100 : lot[1]
if up
    if strategy.position_size < 0
        strategy.close_all()

    strategy.entry("Long", strategy.long, needlong == false ? 0 : lot, when=(time > timestamp(fromyear, frommonth, fromday, 00, 00) and time < timestamp(toyear, tomonth, today, 23, 59)))

if dn
    if strategy.position_size > 0
        strategy.close_all()

    strategy.entry("Short", strategy.short, needshort == false ? 0 : lot, when=(time > timestamp(fromyear, frommonth, fromday, 00, 00) and time < timestamp(toyear, tomonth, today, 23, 59)))

if time > timestamp(toyear, tomonth, today, 23, 59) or exit
strategy.close_all()Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-06. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/BB-Percentage-Index-Trend-Fading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- EMA Cross Trend Following Strategy with SMA Stop Loss and Re Entry MechanismPine Script · Trend following · 1h
- EMA and RSI Trend Trading StrategyPine Script · Trend following · 1d
- AlphaTrend Dual Tracking StrategyPine Script · Trend following · 1h
- Going with the Trend Moving Average Crossover StrategyPine Script · Trend following · 1d
- Moving Average Crossover Strategy 430371Pine Script · Trend following · 1h