Strategy vault / Trend following
Bidirectional Trading Strategy Based on Moon Phases
This strategy trades both long and short based on moon phases, going long on new moons and going short on full moons.
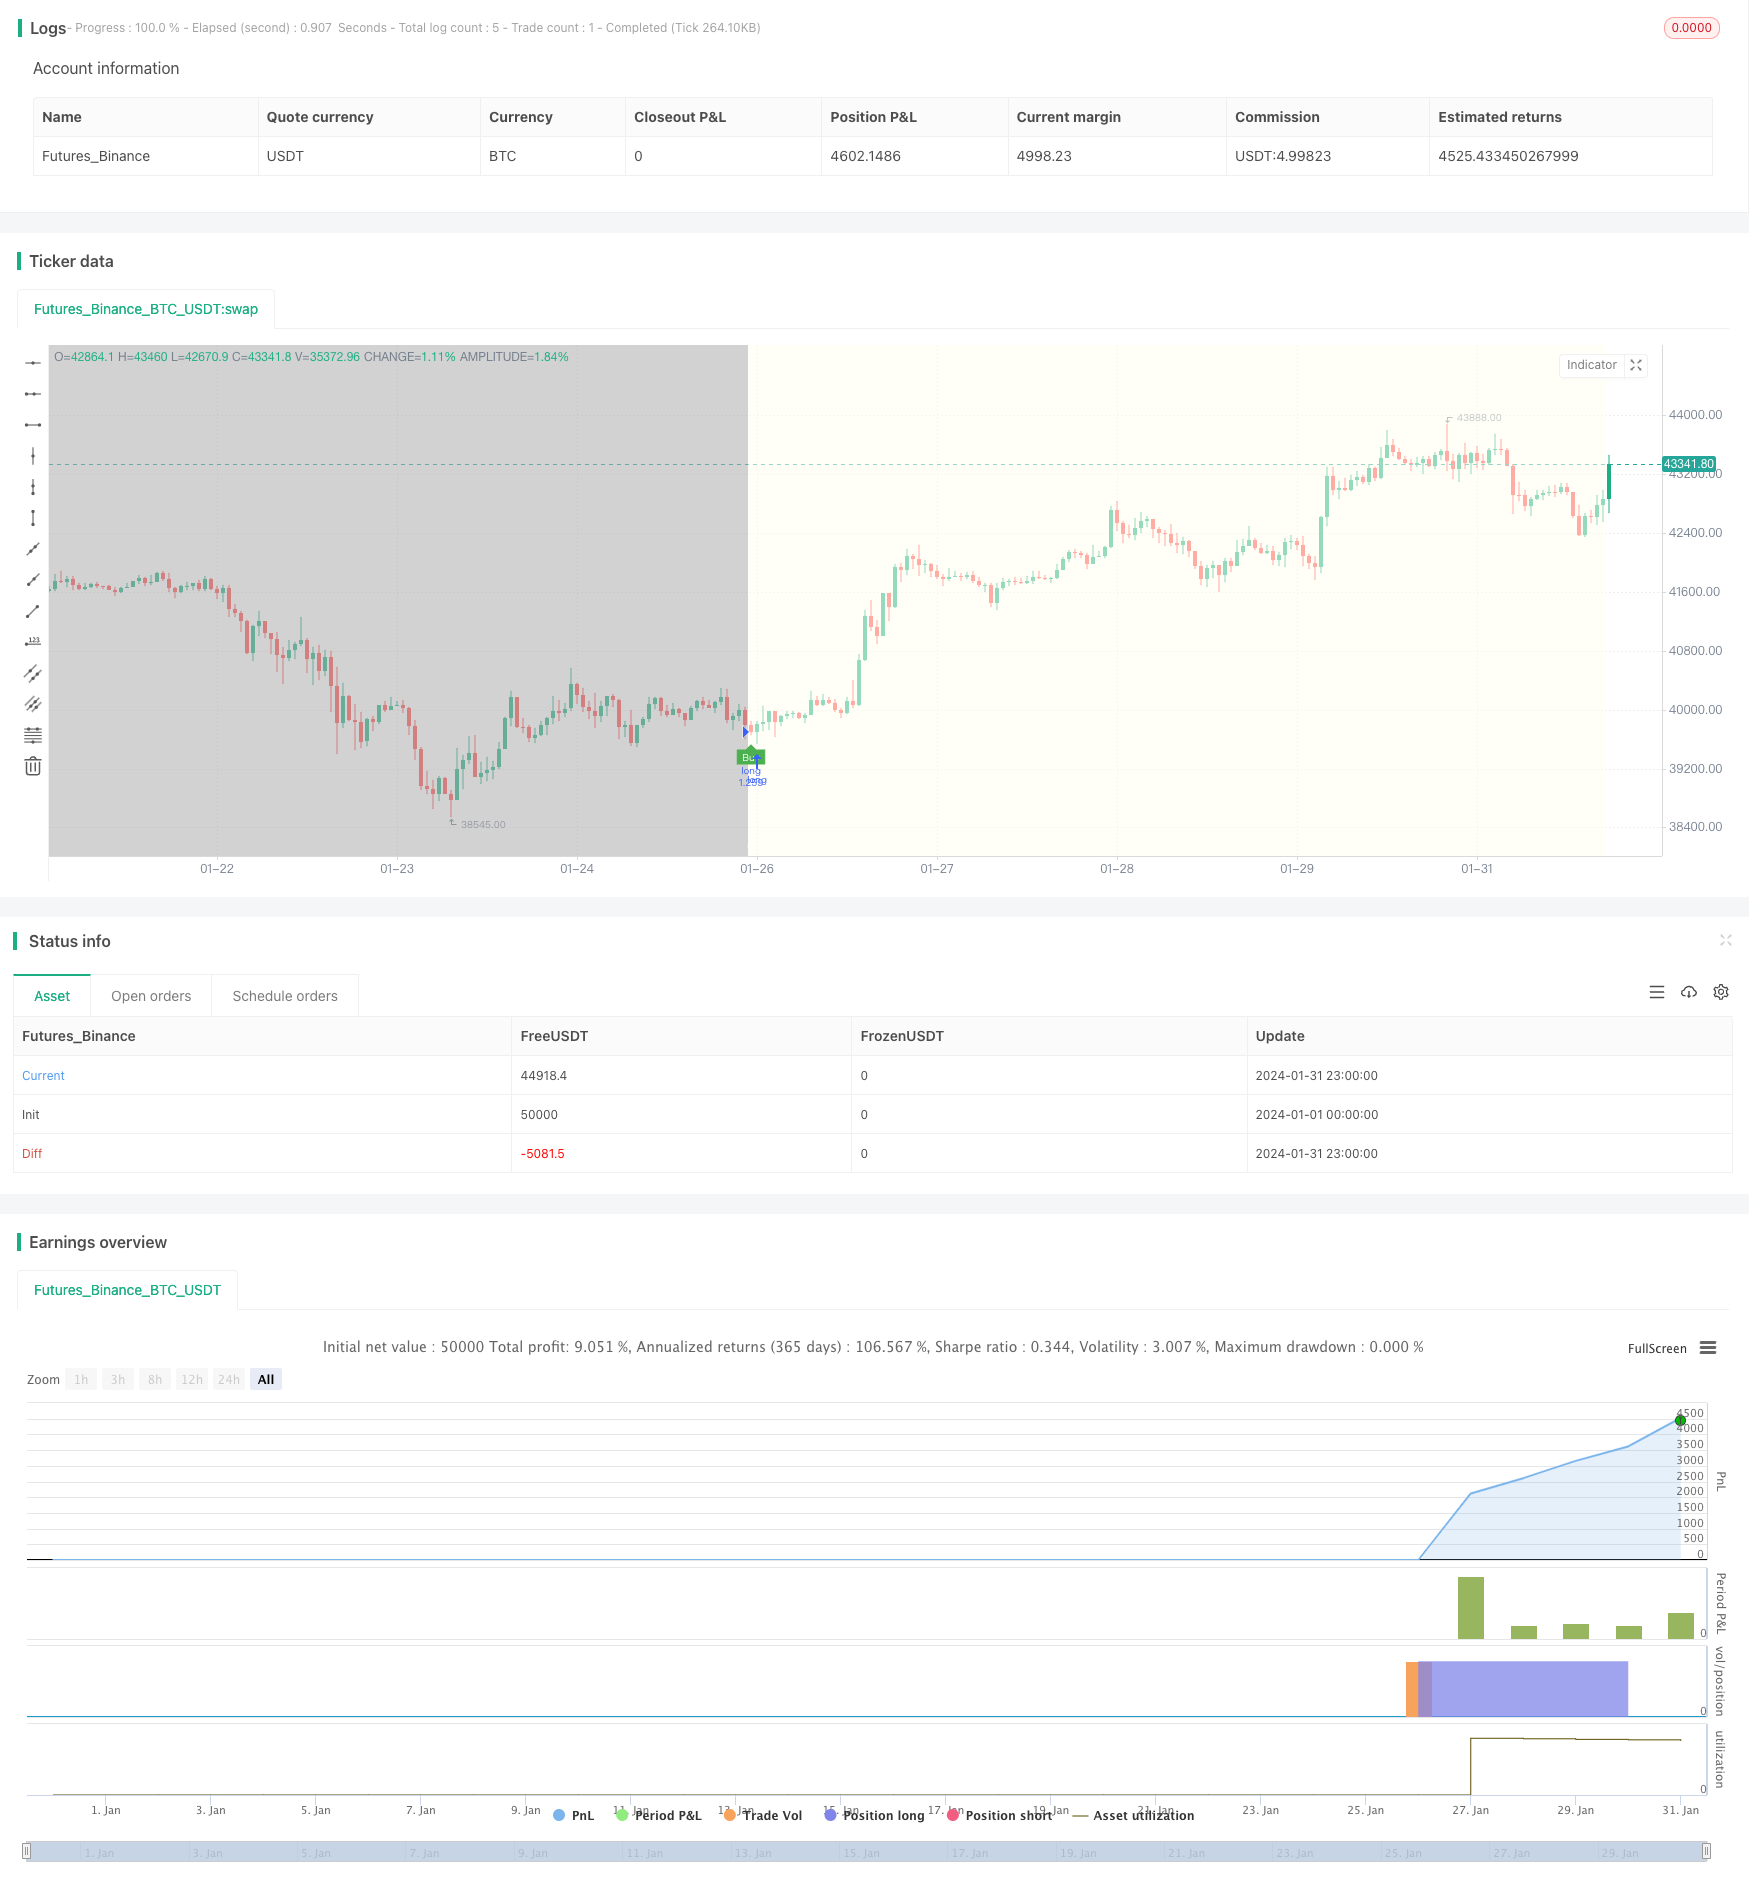
Overview
This strategy trades both long and short based on moon phases, going long on new moons and going short on full moons.
Strategy Logic
The strategy calculates moon phases accurately based on dates using a custom function. Moon age less than 15 is a new moon, and between 15 and 30 a full moon. It generates long and short signals based on moon phases, opening long positions on new moons and short positions on full moons. It closes positions on reverse signals - closing longs on full moons and shorts on new moons.
Users can choose between "long on new moon, short on full moon" or vice versa. Boolean variables track if trades are currently open. It opens new trades when signals appear while no position is open, and closes current positions on reverse signals. Buy and sell markers are displayed visually.
Advantages
- Captures long-term trends using moon cycle periodicity
- Customizable display colors, fill, etc
- Choice of bidirectional strategies
- Clear open/close markers
- Customizable backtest start time for optimization
Risks
- Long moon cycle fails to capture short-term moves
- No stop loss can lead to heavy losses
- Fixed cycles prone to pattern formation
Risk Mitigation:
- Add other short-cycle indicators for multi-timeframe trading
- Implement stop loss
- Optimize position sizing to limit loss impact
Optimization Directions
The strategy can be improved by:
- Adding more indicators to filter signals and improve robustness
- Adding position sizing to optimize and lower loss impact
- Adding stop loss module to limit losses
- Optimizing open/close conditions to reduce slippage and improve win rate
Conclusion
The strategy exploits the periodicity of moon cycles to implement a bidirectional trading strategy based on new and full moons. It has clear signals, high customizability, and catches long-term trends well. But the inability to limit losses poses significant risks. It is recommended to combine short-cycle indicators and add position sizing and stop losses to further optimize the strategy.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | black | New Moon Color |
| v_input_2 | white | Full Moon Color |
| v_input_3 | true | Fill Background? |
| v_input_4 | #fffff0aa | New Moon Background Color |
| v_input_5 | #aaaaaaaa | Full Moon Background Color |
| v_input_6 | 0 | strategy: buy on new moon, sell on full moon | sell on new moon, buy on full moon |
| v_input_7 | true | Show Buy/Sell Signals |
| v_input_8 | true | Long enabled |
| v_input_9 | true | Short enabled |
| v_input_10 | 2017 | Backtesting From Year |
| v_input_11 | true | And Month |
| v_input_12 | true | And Day |
| v_input_13 | false | And Hour |
| v_input_14 | false | And Minute |
Source Pine Script
/*backtest
start: 2024-01-01 00:00:00
end: 2024-01-31 23:59:59
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/

// ---------------------------© paaax----------------------------
// ---------------- Author1: Pascal Simon (paaax) ----------------
// -------------------- www.pascal-simon.de ---------------------
// ---------------- www.tradingview.com/u/paaax/-----------------
// Source: https://gist.github.com/L-A/3497902#file-moonobject-js

// -------------------------© astropark--------------------------
// --------------- Author2: Astropark (astropark) ---------------
// -------------- https://bit.ly/astroparktrading ---------------
// -------------- www.tradingview.com/u/astropark/---------------


// @version=4
strategy(title="[astropark] Moon Phases [strategy]", overlay=true, pyramiding = 10, default_qty_type = strategy.percent_of_equity, default_qty_value = 100, initial_capital = 100000, currency = currency.USD, commission_value = 0.1)

// INPUT    --- {

newMoonColor = input(color.black, "New Moon Color")
fullMoonColor = input(color.white, "Full Moon Color")

fillBackground = input(true, "Fill Background?")
newMoonBackgroundColor = input(#fffff0aa, "New Moon Background Color")
fullMoonBackgroundColor = input(#aaaaaaaa, "Full Moon Background Color")

//} --- INPUT

// FUNCTION --- {

normalize(_v) =>
    x = _v
    x := x - floor(x)
    if x < 0
        x := x + 1
    x

calcPhase(_year, _month, _day) =>

    int y = na
    int m = na
    float k1 = na
    float k2 = na
    float k3 = na
    float jd = na
    float ip = na

    y := _year - floor((12 - _month) / 10)
    m := _month + 9
    if m >= 12
        m := m - 12

    k1 := floor(365.25 * (y + 4712))
    k2 := floor(30.6 * m + 0.5)
    k3 := floor(floor((y / 100) + 49) * 0.75) - 38

    jd := k1 + k2 + _day + 59
    if jd > 2299160
        jd := jd - k3

    ip := normalize((jd - 2451550.1) / 29.530588853)
    age = ip * 29.53

//} --- FUNCTION

// INIT     --- {

age = calcPhase(year, month, dayofmonth)
moon =
     floor(age)[1] > floor(age) ? 1 :
     floor(age)[1] < 15 and floor(age) >= 15 ? -1 : na

//} --- INIT

// PLOT     --- {

plotshape(
     moon==1,
     "Full Moon",
     shape.circle,
     location.top,
     color.new(newMoonColor, 20),
     size=size.normal
     )

plotshape(
     moon==-1,
     "New Moon",
     shape.circle,
     location.bottom,
     color.new(fullMoonColor, 20),
     size=size.normal
     )

var color col = na
if moon == 1 and fillBackground
    col := fullMoonBackgroundColor
if moon == -1 and fillBackground
    col := newMoonBackgroundColor
bgcolor(col, title="Moon Phase", transp=10)

//} --- PLOT


// STRATEGY     --- {

strategy = input("buy on new moon, sell on full moon", options=["buy on new moon, sell on full moon","sell on new moon, buy on full moon"])
longCond = strategy == "buy on new moon, sell on full moon" ? moon == -1 : moon == 1
shortCond = strategy == "buy on new moon, sell on full moon" ? moon == 1 : moon == -1

weAreInLongTrade = false
weAreInShortTrade = false
weAreInLongTrade := (longCond or weAreInLongTrade[1]) and shortCond == false
weAreInShortTrade := (shortCond or weAreInShortTrade[1]) and longCond == false
buySignal = longCond and weAreInLongTrade[1] == false
sellSignal = shortCond and weAreInShortTrade[1] == false

showBuySellSignals = input(defval=true, title = "Show Buy/Sell Signals")
longEnabled = input(true, title="Long enabled")
shortEnabled = input(true, title="Short enabled")

analysisStartYear = input(2017, "Backtesting From Year", minval=1980)
analysisStartMonth = input(1, "And Month", minval=1, maxval=12)
analysisStartDay = input(1, "And Day", minval=1, maxval=31)
analysisStartHour = input(0, "And Hour", minval=0, maxval=23)
analysisStartMinute = input(0, "And Minute", minval=0, maxval=59)
analyzeFromTimestamp = timestamp(analysisStartYear, analysisStartMonth, analysisStartDay, analysisStartHour, analysisStartMinute)

plotshape(showBuySellSignals and buySignal, title="Buy Label", text="Buy", location=location.belowbar, style=shape.labelup, size=size.tiny, color=color.green, textcolor=color.white, transp=0)
plotshape(showBuySellSignals and sellSignal, title="Sell Label", text="Sell", location=location.abovebar, style=shape.labeldown, size=size.tiny, color=color.red, textcolor=color.white, transp=0)

strategy.entry("long", strategy.long, when = time > analyzeFromTimestamp and buySignal and longEnabled)
strategy.entry("short", strategy.short, when = time > analyzeFromTimestamp and sellSignal and shortEnabled)
strategy.close("long", when = sellSignal)
strategy.close("short", when = buySignal)

//} --- STRATEGY
Published by ChaoZhang on the FMZ strategy square · last modified 2024-02-21. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Bidirectional-Trading-Strategy-Based-on-Moon-Phases.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- 200 EMA VWAP MFI Trend Following StrategyPine Script · Trend following · 1d
- 4 EMA Trend StrategyPine Script · Trend following · 1d
- ADX MA and EMA Long Only Trend Tracking StrategyPine Script · Trend following · 1d
- ATR Dynamic Profit Target and Stop Loss StrategyPine Script · Trend following · 1d
- ATR Dynamic Trend Following and EMA Crossover Trading StrategyPine Script · Trend following · 1d
- ATR and Moving Average Crossover Hybrid StrategyPine Script · Trend following · 1h