Black Swan Volatility and Moving Average Crossover Momentum Tracking Strategy
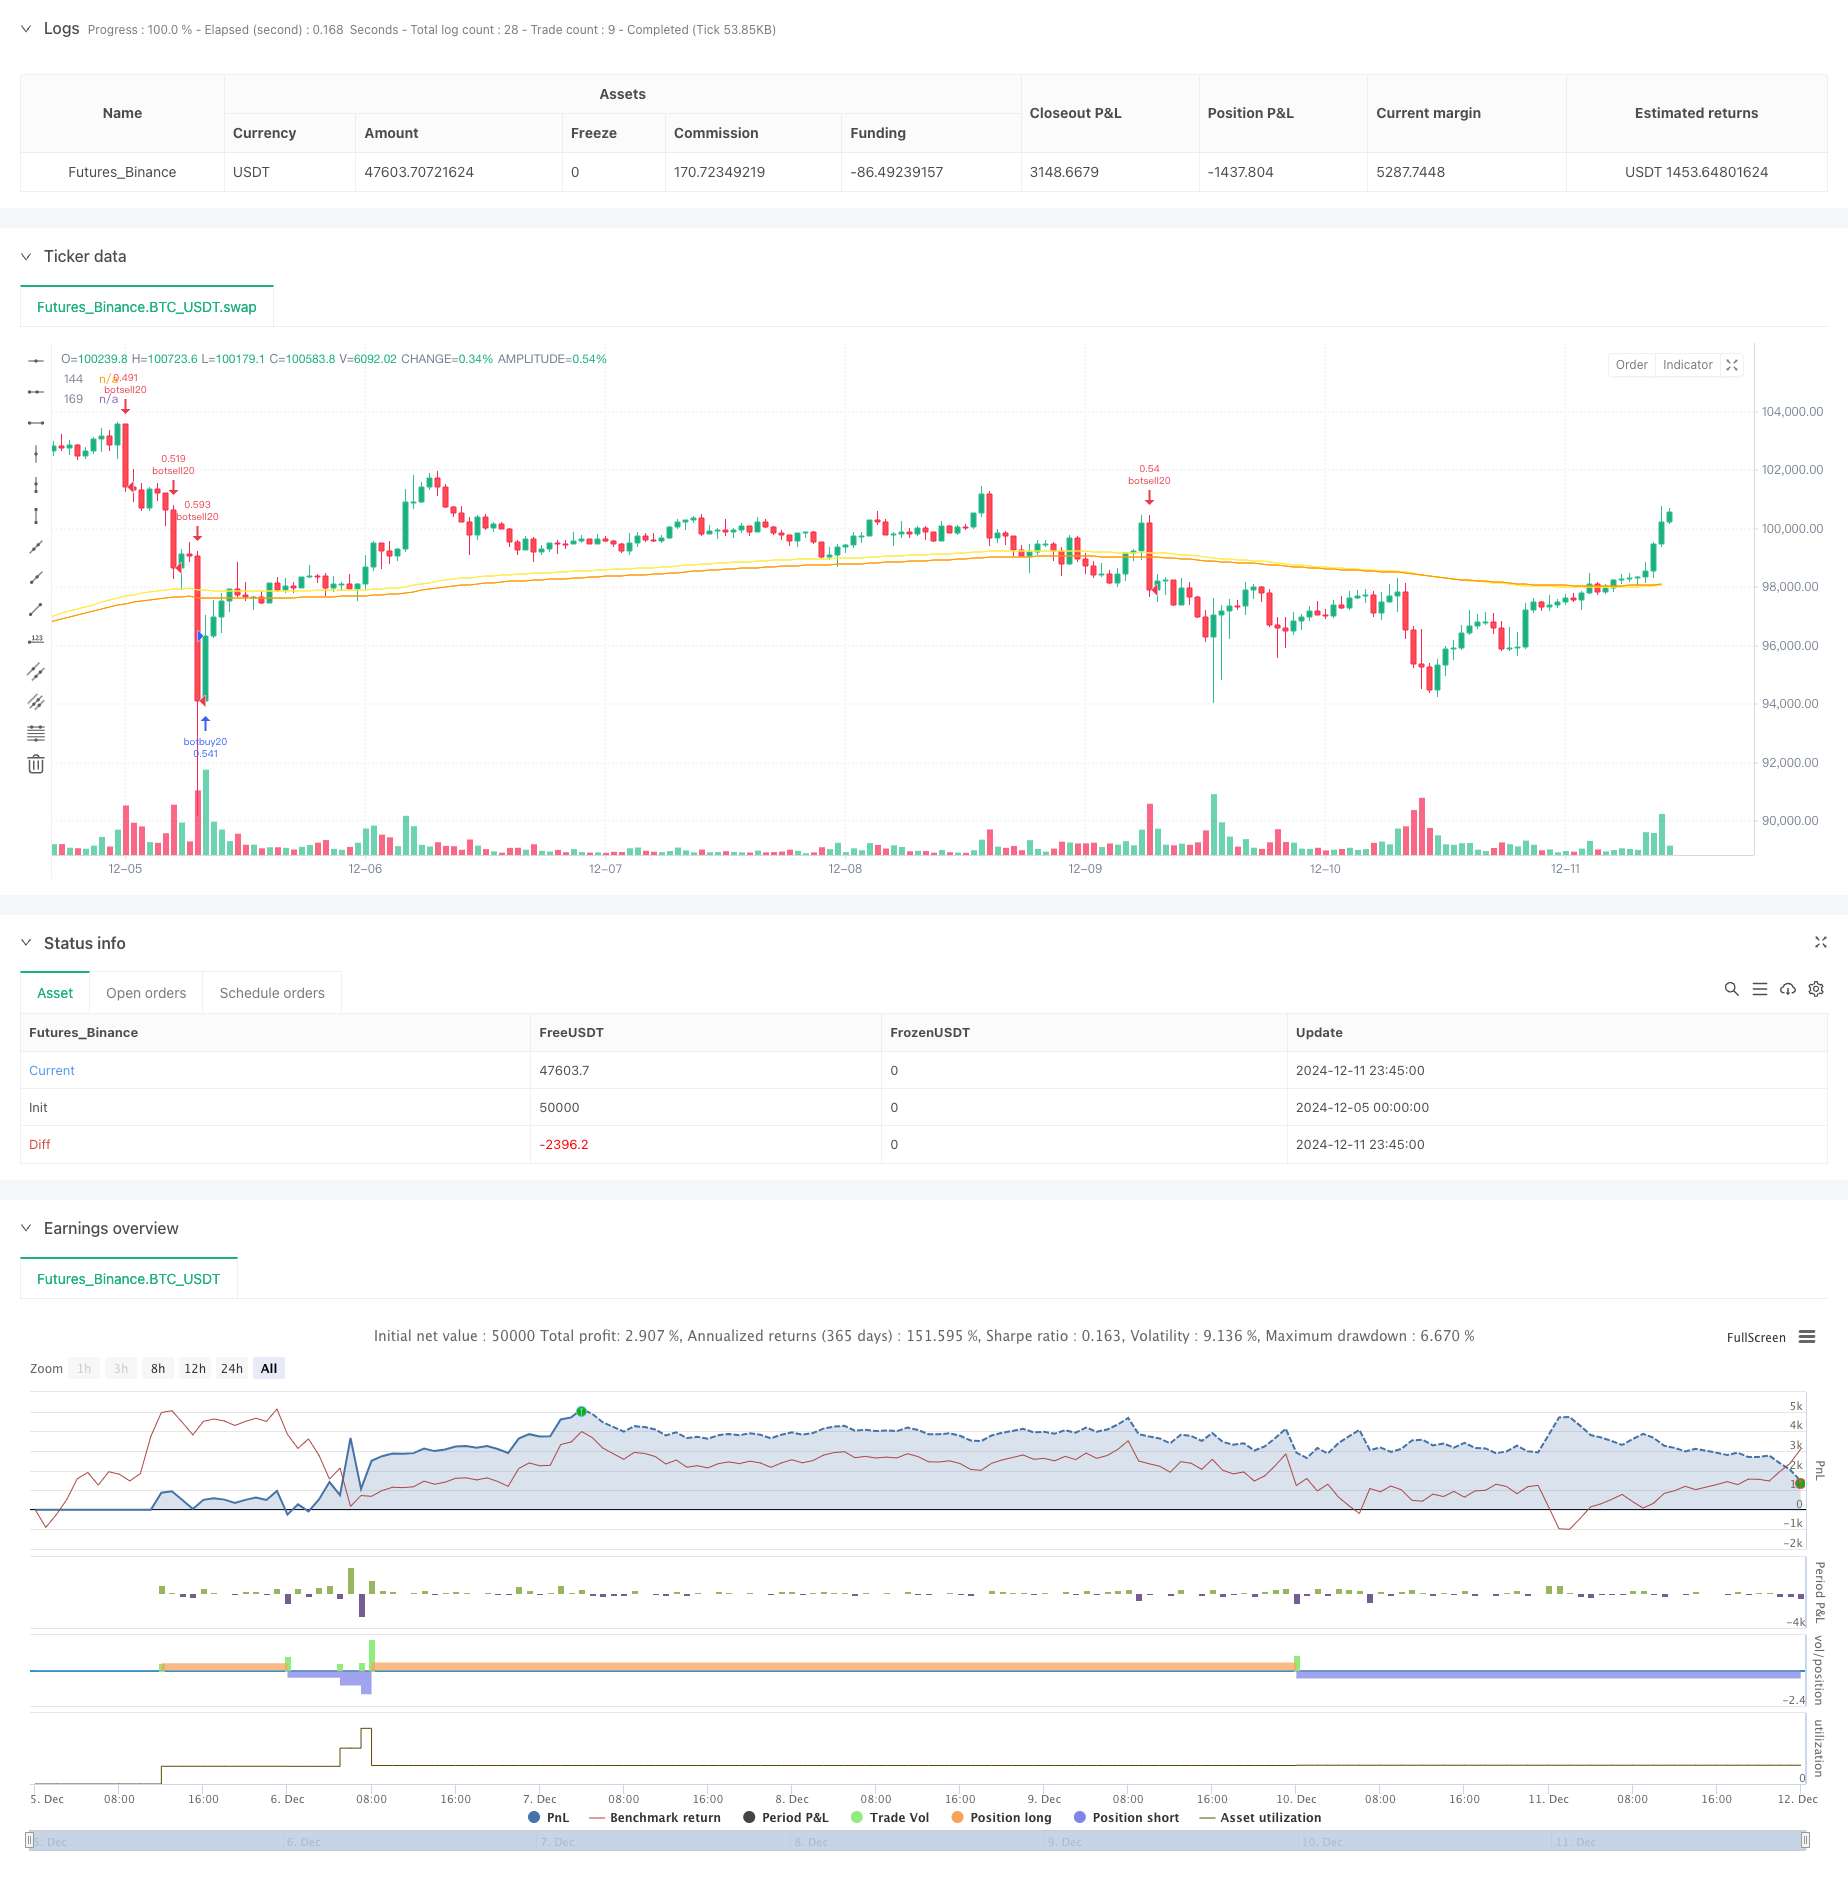
This strategy is a momentum tracking trading system based on price volatility and moving average crossovers. It triggers signals by monitoring price volatility exceeding 1.91% (Black Swan events) and combines EMA144…
Overview
This strategy is a momentum tracking trading system based on price volatility and moving average crossovers. It triggers signals by monitoring price volatility exceeding 1.91% (Black Swan events) and combines EMA144 and EMA169 crossovers to confirm trend direction and exit timing. The strategy is particularly suitable for short-term trading on 1-3 minute timeframes, capable of quickly capturing significant market volatility opportunities.
Strategy Principle
The core logic consists of two main components:
- Volatility Monitoring: Calculates the absolute difference between closing and opening prices relative to the closing price, triggering trading signals when this ratio exceeds 1.91%.
- Trend Confirmation: Uses EMA144 and EMA169 crossovers to confirm trend direction, going long on upward crosses and short on downward crosses. SMA60 and SMA20 are also incorporated as auxiliary indicators.
The strategy enters long positions when detecting upward volatility above 1.91% and short positions for downward volatility. Positions are automatically closed when moving averages cross in the opposite direction to manage risk.
Strategy Advantages
- Quick Response: The strategy promptly captures sharp market movements, ideal for short-term trading.
- Risk Control: Uses moving average crossovers as exit signals to effectively manage position risk.
- High Flexibility: Allows for backtesting period customization and parameter adjustment to optimize for different market conditions.
- Comprehensive Position Management: Uses account equity percentage for position sizing and supports up to 3x pyramid scaling.
Strategy Risks
- False Breakout Risk: May generate false signals in highly volatile markets leading to unnecessary trades.
- Slippage Risk: Short-term operations may face significant slippage losses.
- Trend Reversal Risk: Possibility of rapid trend reversals following extreme volatility.
- Parameter Sensitivity: Strategy performance is highly dependent on parameter settings, requiring frequent adjustments under different market conditions.
Optimization Directions
- Incorporate Volatility Filtering: Recommend adding ATR indicator to filter market noise and improve signal quality.
- Optimize Entry Timing: Consider adding volume confirmation to enhance entry accuracy.
- Dynamic Parameter Adjustment: Suggest developing an adaptive parameter system to automatically adjust trigger thresholds based on market conditions.
- Enhanced Stop-Loss Mechanism: Recommend adding trailing stop-loss functionality to better protect accumulated profits.
Summary
This strategy achieves quick response to market anomalies and trend following by combining volatility monitoring with moving average crossovers. While the strategy design is sound with good risk control mechanisms, traders need to optimize parameters and manage risks according to actual market conditions. It's recommended to start with small positions in live trading and gradually validate strategy performance across different market environments.
Source Pine Script
/*backtest
start: 2024-12-05 00:00:00
end: 2024-12-12 00:00:00
period: 45m
basePeriod: 45m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5

//Black Swan alarm, author (): Douglas Robot
//Suitable1Minute-3Minute(s) ofkline, when the fluctuation exceeds 2%, it will automatically alarm
strategy('Black Swan Alert', overlay=true, initial_capital=10000, currency='USD', default_qty_type=strategy.percent_of_equity, default_qty_value=100, commission_type=strategy.commission.percent, commission_value=0.075, pyramiding=3)
//-------------------------------------------
//-------------------------------------------
timecondition = timeframe.period == '480' or timeframe.period == '240' or timeframe.period == 'D' or timeframe.period == '720'
// Make input options that configure backtest date range
startDate = input.int(title='Start Date', defval=1, minval=1, maxval=31)
startMonth = input.int(title='Start Month', defval=11, minval=1, maxval=12)
startYear = input.int(title='Start Year', defval=2018, minval=1800, maxval=2100)
endDate = input.int(title='End Date', defval=1, minval=1, maxval=31)
endMonth = input.int(title='End Month', defval=11, minval=1, maxval=12)
endYear = input.int(title='End Year', defval=2031, minval=1800, maxval=2100)
// Look if the close time of the current bar
// falls inside the date range
inDateRange = time >= timestamp(syminfo.timezone, startYear, startMonth, startDate, 0, 0) and time < timestamp(syminfo.timezone, endYear, endMonth, endDate, 0, 0)


// Inputs
a = input(1, title='Key Vaule. \'This changes the sensitivity\'')
c = input(10, title='ATR Period')
h = input(false, title='Signals from Heikin Ashi Candles')


ma60 = ta.sma(close, 60)
ema144 = ta.ema(close, 144)

ema169 = ta.ema(close, 169)
ma20 = ta.sma(close, 20)


plot(ema144, color=color.new(color.yellow, 0), title='144')
plot(ema169, color=color.new(color.orange, 0), title='169')


heitiane = close - open
heitiane := math.abs(heitiane)
heitiane /= close

if inDateRange and heitiane > 0.0191 and close < open  //  and close>f3
    strategy.entry('botsell20', strategy.short, comment='Black swan short' + str.tostring(heitiane))

if ta.crossover(ema144, ema169)
    strategy.close('botsell20', comment='close short')
if inDateRange and heitiane > 0.0191 and close > open  //  and close>f3
    strategy.entry('botbuy20', strategy.long, comment='White swan long' + str.tostring(heitiane))

if ta.crossunder(ema144, ema169)
    strategy.close('botbuy20', comment='close long')
Published by ChaoZhang on the FMZ strategy square · last modified 2024-12-13. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Black-Swan-Volatility-and-Moving-Average-Crossover-Momentum-Tracking-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- KST EMA Momentum Trend Following StrategyPine Script · Momentum · 1d
- Multi EMA Trend Momentum Trading Strategy with Risk Management SystemPine Script · Momentum · 1h
- Multi Indicator Trend Momentum Trading Strategy with Dynamic Risk Management SystemPine Script · Momentum · 1h
- Triple EMA and Fisher Transform Trend Momentum StrategyPine Script · Momentum · 1d
- Advanced EMA Crossover Momentum Trend Capture StrategyPine Script · Momentum · 2h
- Multi Trend Momentum Crossover Strategy with Volatility Optimization SystemPine Script · Momentum · 1d