Bollinger Band Momentum Burst Strategy
This strategy uses Bollinger Bands to judge trends by comparing fluctuations inside and outside the bands, and uses momentum indicators to follow the trend. It belongs to trend following strategies. It generates new…
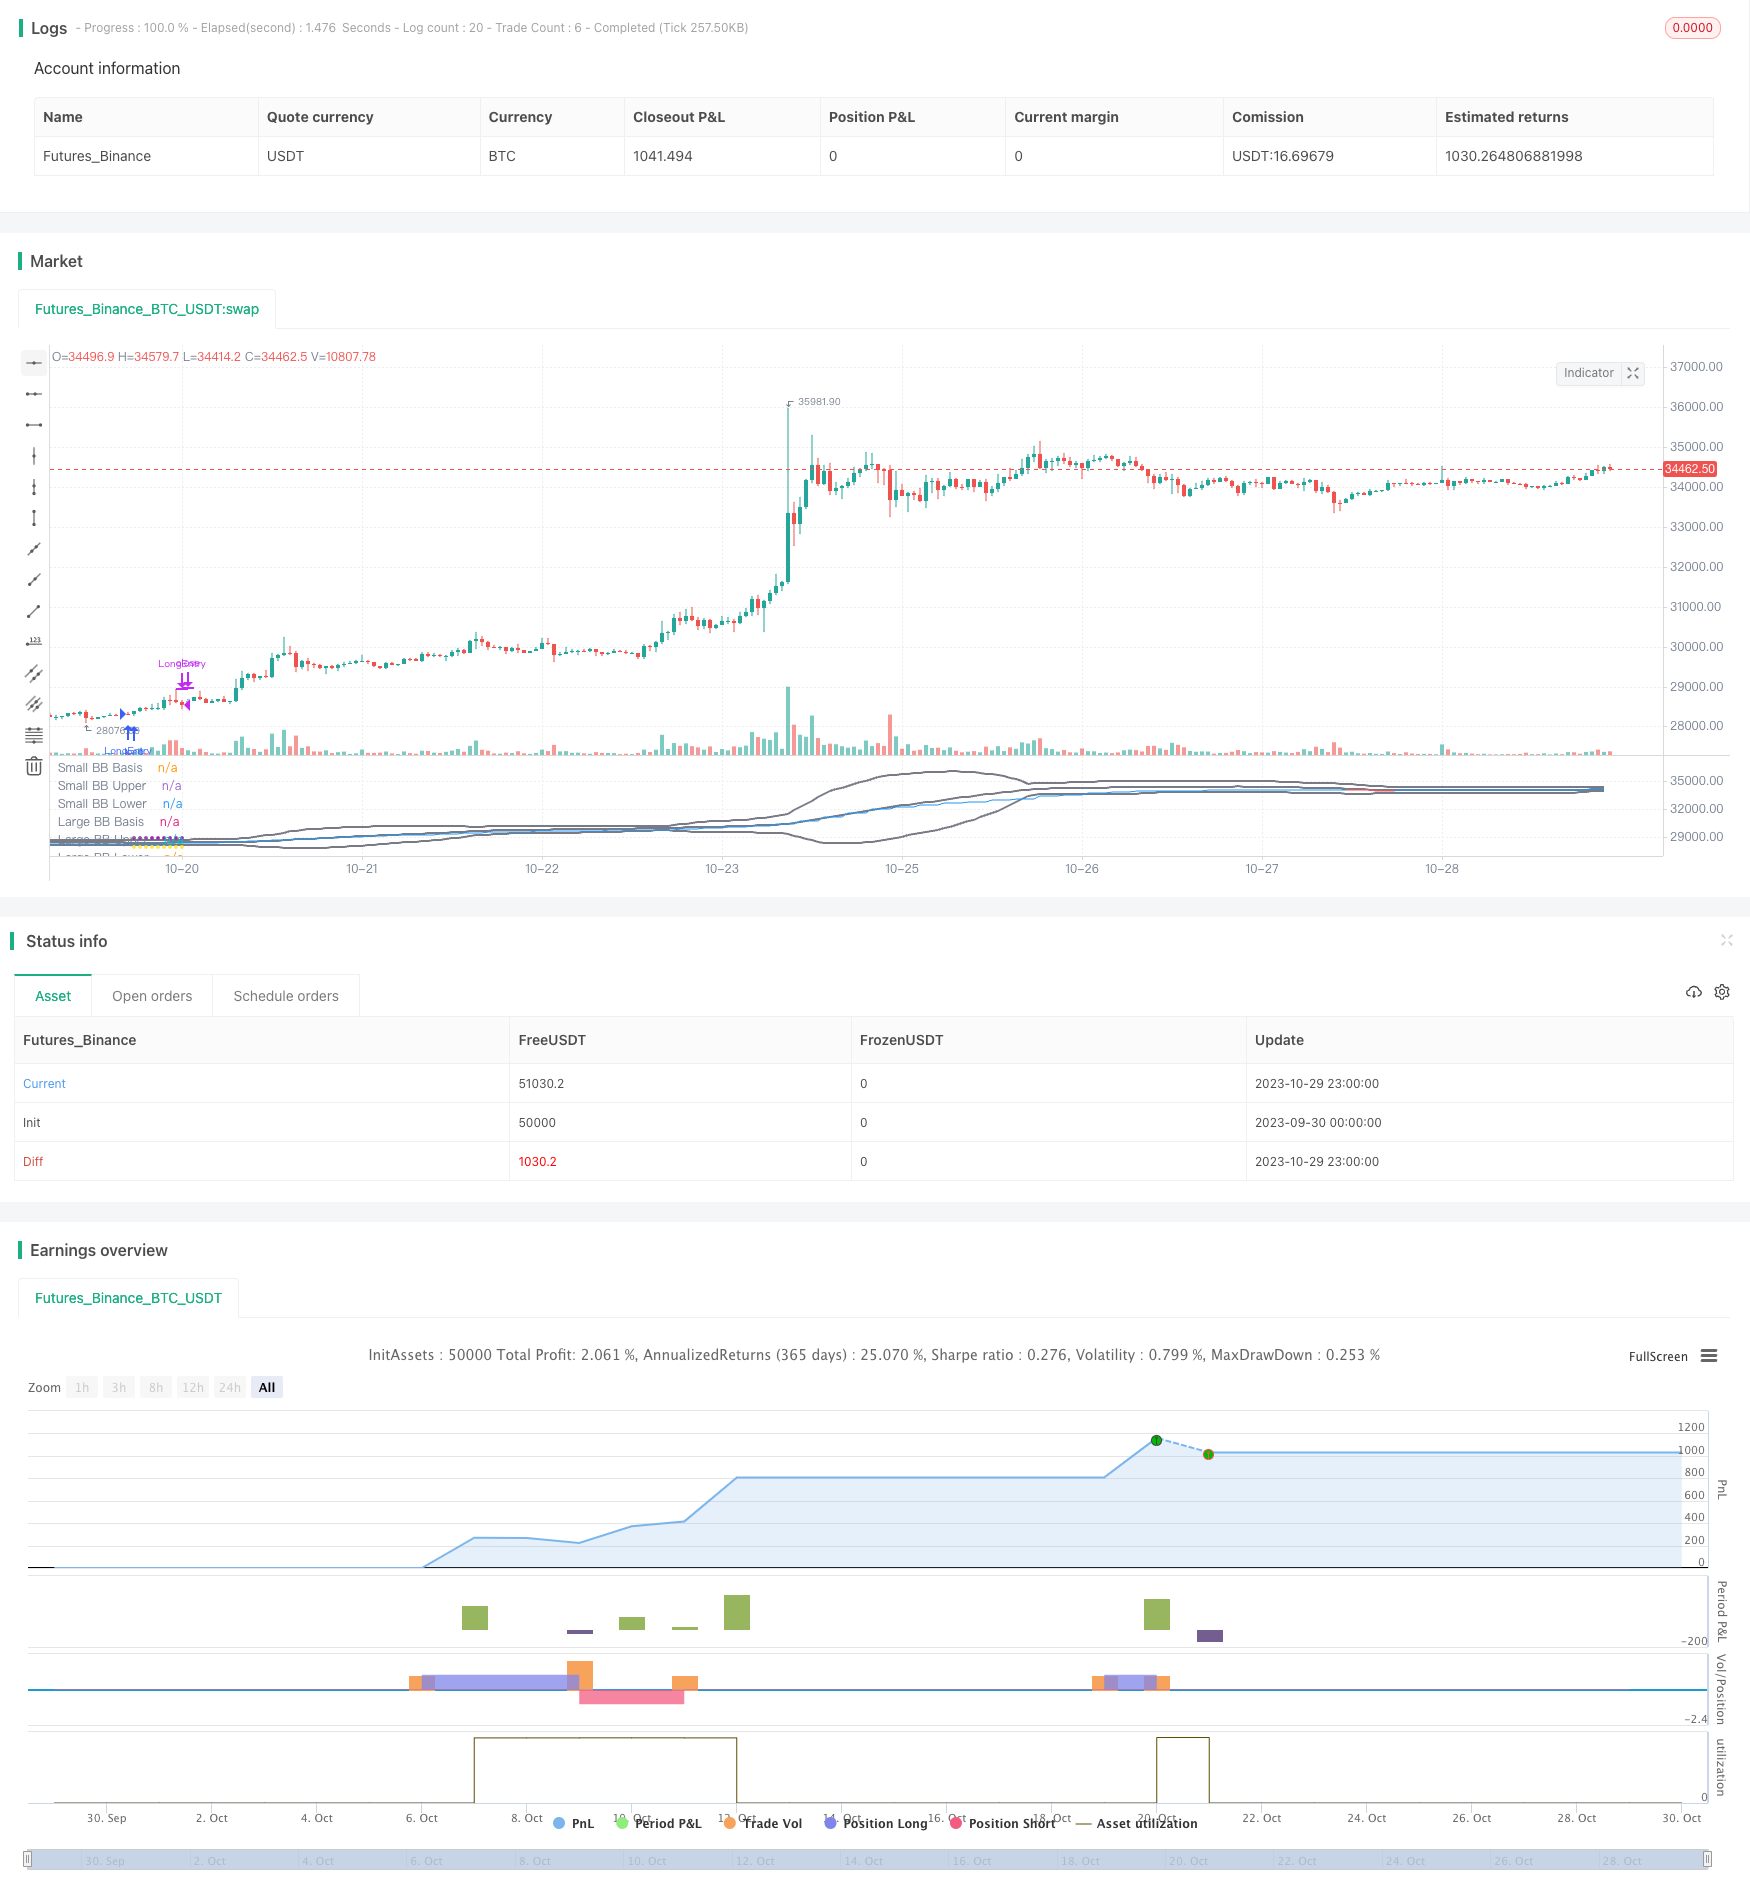
Overview
This strategy uses Bollinger Bands to judge trends by comparing fluctuations inside and outside the bands, and uses momentum indicators to follow the trend. It belongs to trend following strategies. It generates new trend direction signals when volatility inside the band is less than outside, and opens positions. The stop loss uses ATR multiples, and take profit is ATR multiples of risk reward ratio.
Principles
The strategy consists of the following main parts:
Bollinger Bands settings: Large bands with length 40, small bands length 20, band width is 2 standard deviations.
Band explosion judgment: If large band upper is below small band upper, and large band lower is above small band lower, it indicates increased volatility and generates new trend direction signals.
Momentum indicator: 240 timeframe 14 EMA judges trend direction.
ATR stop loss and take profit: ATR 14 times for stop loss distance, take profit is 1.5 times of stop loss distance.
The strategy first judges if the band explodes, then determines long or short based on momentum direction. After entry, use ATR multiples for stop loss and take profit management.
Advantages
Using double Bollinger bands can compare volatility across timeframes, to determine trend burst points.
Using momentum indicators avoids being whipsawed by ranging markets.
ATR stops adjusts stop distance based on market volatility.
Reasonable risk reward ratio, not too aggressive or conservative.
Risks
May be trapped in ranging markets without clear trends. Can optimize momentum parameters to reduce false signals.
ATR stops may be too conservative. Consider other stop methods like trailing stops.
Fixed ATR multiples may not suit all products. Consider making it adjustable.
Dual Bollinger effectiveness unproven. Test other channels like KD.
Optimization Directions
Test different momentum parameters to find optimal combinations.
Try different stop methods like trailing stops, adaptive ATR.
Make ATR multiples adjustable based on product and market conditions.
Test different channel indicators for more stability.
Consider adding compounding management for better profit control.
Filter entry signals by swings, time etc to improve win rate.
Conclusion
The strategy logic is clear, using dual Bollinger to determine trend burst is the biggest highlight. But optimizations are still needed on stops, channels, risk management etc to make parameters more adaptive across different market conditions. Overall the strategy has good advantages and potential, worth further research.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | (?BB)Large BB Resolution | |
| v_input_2 | 40 | Large BB Length |
| v_input_3 | Small BB Resolution | |
| v_input_4 | 20 | Small BB Length |
| v_input_5 | 2 | BB StdDev |
| v_input_6 | 14 | BB expand valid length |
| v_input_7 | 240 | (?SMT)EMA Trend t/f |
| v_input_8 | 14 | Length |
| v_input_9 | 3 | Smooth factor |
| v_input_10 | 0 | (?Trade)Detect Risk Management Based On: ATR | Bracket | No detection |
| v_input_11 | 3 | (?ATR)ATR Multiple |
| v_input_12 | 1.5 | Risk Reward Ratio for ATR |
| v_input_13 | 100 | (?Bracket)Stop Loss Point for Braket(tick) |
| v_input_14 | 200 | Take Profit Point for Braket(tick) |
Source Pine Script
/*backtest
start: 2023-09-30 00:00:00
end: 2023-10-30 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © kasaism
//@version=4
// strategy(title="[EURUSD60] BB Expansion Strategy", shorttitle="[EURUSD60] BBEXP",overlay=true, max_bars_back=5000, max_labels_count=500)

// === INPUTS === //
////BB
largeBbRes = input(title="Large BB Resolution", type=input.resolution, defval="", group="BB")
largeBbLength = input(title="Large BB Length", type=input.integer, defval=40, minval=1, group="BB")
smallBbRes = input(title="Small BB Resolution ", type=input.resolution, defval="", group="BB")
smallBbLength = input(title="Small BB Length", type=input.integer, defval=20, minval=1, group="BB")
multi = input(title="BB StdDev", type=input.float, defval=2.0, maxval=10, minval=0.01, group="BB")
validLen = input(title="BB expand valid length", defval=14, group="BB")

// 3 each EMA settings. EMA directions are as each time frame directions.
resFirstTime = input(title="EMA Trend t/f", type=input.resolution, defval="240", group="SMT")
// resSecondTime = input(title="Second t/f", type=input.resolution, defval="30", group="SMT")
// resThirdTime = input(title="Third t/f", type=input.resolution, defval="", group="SMT")
emaLen = input(14, minval=1, title="Length", group="SMT")
smooth = input(3, minval=1, title="Smooth factor", group="SMT")

//Lisk Management
var riskManagementRule1 = "ATR"
var riskManagementRule2 = "Bracket"
riskManagementRule = input(riskManagementRule1, "Detect Risk Management Based On", options=[riskManagementRule1, riskManagementRule2, "No detection"], group="Trade")
atrMulti = input(3.0, title="ATR Multiple", type=input.float, minval = 1.0, group="ATR")
riskRewardRatio = input(1.5, title="Risk Reward Ratio for ATR", type=input.float, minval = 0.01, group="ATR")
stopLossPoint = input(100, title="Stop Loss Point for Braket(tick)", type=input.float, minval = 1.0, group="Bracket")
takeProfitPoint = input(200, title="Take Profit Point for Braket(tick)", type=input.float, minval = 1.0, group="Bracket")
// === /INPUTS/ === //

// === CONSTANT === //
//For barmerge.lookahead_off
index = barstate.isrealtime ? 1 : 0

//For Entry
NOENTRY=0
LONG=1
SHORT=2

//SMT color
int up=1
int dn=2
int up_HL=3
int dn_HL=4

//label color
color_bearish = color.red
color_bullish = color.blue
C_label_color_bearish = color.red
C_label_color_bullish = color.blue
// === /CONSTANT/ === //


// === FUNCTIONS === //
//BB trade direction
bbTradeDetection(lrgUpper, lrgLower, smlUpper, smlLower) =>
    if not(na(lrgUpper) or na(lrgLower) or na(smlUpper) or na(smlLower))
        if lrgUpper < smlUpper and lrgLower > smlLower
            true
        else
            false
    else
        na
// === /FUNCTIONS/ === //


// === CALCURATES === //
////BB
//large BB
lrgBbBasis = security(syminfo.tickerid, largeBbRes, sma(close[index], largeBbLength))
lrgBbDev = multi * security(syminfo.tickerid, largeBbRes, stdev(close[index], largeBbLength))
lrgBbUpper = lrgBbBasis + lrgBbDev
lrgBbLower = lrgBbBasis - lrgBbDev

//small BB
smlBbBasis = security(syminfo.tickerid, smallBbRes, sma(close[index], smallBbLength))
smlBbDev = multi * security(syminfo.tickerid, smallBbRes, stdev(close[index], smallBbLength))
smlBbUpper = smlBbBasis + smlBbDev
smlBbLower = smlBbBasis - smlBbDev

bbTrade = bbTradeDetection(lrgBbUpper, lrgBbLower, smlBbUpper, smlBbLower)

//EMA Trend
base=security(syminfo.tickerid, resFirstTime, ema(close[index],emaLen))
sig=security(syminfo.tickerid, resFirstTime, ema(base[index],smooth))
emaTrend = not(na(base) or na(sig)) ? base < sig ? dn : up : na

////LISK MANAGEMENT
float stopLossLineForLong = na
float stopLossLineForShort = na
float takeProfitLineForLong = na
float takeProfitLineForShort = na
atr_ = atr(14) * atrMulti

if riskManagementRule == riskManagementRule1
    stopLossLineForLong := strategy.position_size > 0 ? stopLossLineForLong[1] ? stopLossLineForLong[1] : round(close[index] - atr_,3) : na
    stopLossLineForShort := strategy.position_size < 0 ? stopLossLineForShort[1] ? stopLossLineForShort[1] : round(close[index] + atr_,3) : na
    takeProfitLineForLong := strategy.position_size > 0 ? takeProfitLineForLong[1] ? takeProfitLineForLong[1] : close[index] + atr_*riskRewardRatio : na
    takeProfitLineForShort := strategy.position_size < 0 ? takeProfitLineForShort[1] ? takeProfitLineForShort[1] :close[index] - atr_*riskRewardRatio : na

if riskManagementRule == riskManagementRule2
    stopLossLineForLong := strategy.position_size > 0 ? stopLossLineForLong[1] ? stopLossLineForLong[1] : close[index] - stopLossPoint * syminfo.mintick : na
    stopLossLineForShort := strategy.position_size < 0 ? stopLossLineForShort[1] ? stopLossLineForShort[1] : close[index] + stopLossPoint * syminfo.mintick : na
    takeProfitLineForLong := strategy.position_size > 0 ? takeProfitLineForLong[1] ? takeProfitLineForLong[1] : close[index] +takeProfitPoint * syminfo.mintick : na
    takeProfitLineForShort := strategy.position_size < 0 ? takeProfitLineForShort[1] ? takeProfitLineForShort[1] :close[index] - takeProfitPoint * syminfo.mintick : na
// === /CALCURATES/ === //


// === CONDITIONS === //
//BB
bool isBbEntry = na
for i=0 to validLen
    isBbEntry := bbTrade==true ? true : bbTrade[i]==true ? true : false
//plotshape(isBbEntry, style=shape.circle, location=location.bottom)

isBbLong = isBbEntry and open[index] < smlBbBasis[index] and close[index] > smlBbBasis[index]
isBbShort = isBbEntry and open[index] > smlBbBasis[index] and close[index] < smlBbBasis[index]

//SMT
isEmaLong = emaTrend == up
isEmaShort = emaTrend == dn

//ATR
isAtrLongStop = low[index] <= stopLossLineForLong
isAtrShortStop = high[index] >= stopLossLineForShort
isAtrLongLimit = high[index] >= takeProfitLineForLong
isAtrShortLimit = low[index] <= takeProfitLineForShort
// === /CONDITIONS/ === //


// === TRADE === //
//ENTRY
if (isBbLong and isEmaLong)
    strategy.entry("LongEntry", strategy.long,  comment="LongEntry")
    if riskManagementRule == riskManagementRule2
        strategy.exit("LongEntry", loss=stopLossPoint, profit=takeProfitPoint, comment="bracket")
if (isBbShort and isEmaShort)
    strategy.entry("ShortEntry", strategy.short,  comment="ShortEntry")
    if riskManagementRule == riskManagementRule2
        strategy.exit("ShortEntry", loss=stopLossPoint, profit=takeProfitPoint, comment="bracket")
//EXIT
if riskManagementRule == riskManagementRule1
    if(isAtrLongStop)
        strategy.close("LongEntry", when=isAtrLongStop, comment="ATR Stop")
    if(isAtrShortStop)
        strategy.close("ShortEntry", when=isAtrShortStop, comment="ATR Stop")
    if(isAtrLongLimit)
        strategy.close("LongEntry", when=isAtrLongLimit, comment="ATR Limit")
    if(isAtrShortLimit)
        strategy.close("ShortEntry", when=isAtrShortLimit, comment="ATR Limit")
//  === /TRADE/ === //


// === PLOTS === //
plot(lrgBbBasis, title="Large BB Basis", linewidth=2, color=color.gray)
plot(lrgBbUpper, title="Large BB Upper", linewidth=2, color=color.gray)
plot(lrgBbLower, title="Large BB Lower", linewidth=2, color=color.gray)
plot(smlBbBasis, title="Small BB Basis", color=color.white)
plot(smlBbUpper, title="Small BB Upper", color=color.white)
plot(smlBbLower, title="Small BB Lower", color=color.white)
plot(base, title="EMA Line", color= emaTrend==dn ? color_bearish : emaTrend==up ? color_bullish : color.gray)

plot(stopLossLineForLong ? stopLossLineForLong : na, title="S/L Line For Long", color=color.yellow, style=plot.style_circles)
plot(stopLossLineForShort ? stopLossLineForShort : na, title="S/L Line For Short", color=color.yellow, style=plot.style_circles)
plot(takeProfitLineForLong ? takeProfitLineForLong : na, title="T/P Line For Long", color=color.purple, style=plot.style_circles)
plot(takeProfitLineForShort ? takeProfitLineForShort : na, title="T/P Line For Short", color=color.purple, style=plot.style_circles)
// /=== PLOTS ===/ //Published by ChaoZhang on the FMZ strategy square · last modified 2023-10-31. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Bollinger-Band-Momentum-Burst-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Moving Average Candle Regression StrategyPine Script · Momentum · 15m
- Multi Indicator Trend Momentum Trading Strategy An Optimized Quantitative Trading System Based on Bollinger Bands Fibonacci and ATRPine Script · Momentum · 1h
- Multi Trend Momentum Crossover Strategy with Volatility Optimization SystemPine Script · Momentum · 1d
- Momentum Trading Strategy Based on Multi factor ModelPine Script · Momentum · 1d
- Dynamic Momentum Weighted Moving Average Crossover StrategyPine Script · Momentum · 1h
- Multi Indicator Comprehensive Analysis Quantitative Trading Strategy Trend Momentum and Volatility Collaborative Prediction ModelPine Script · Momentum · 3m