Strategy vault / Mean reversion
Bollinger Bands and VWAP based Quantitative Trading Strategy
This strategy combines Bollinger Bands (BB) and Volume Weighted Average Price (VWAP) indicators to make entry and exit decisions. It can discover short-term price anomalies for trading and is suitable for short-term…
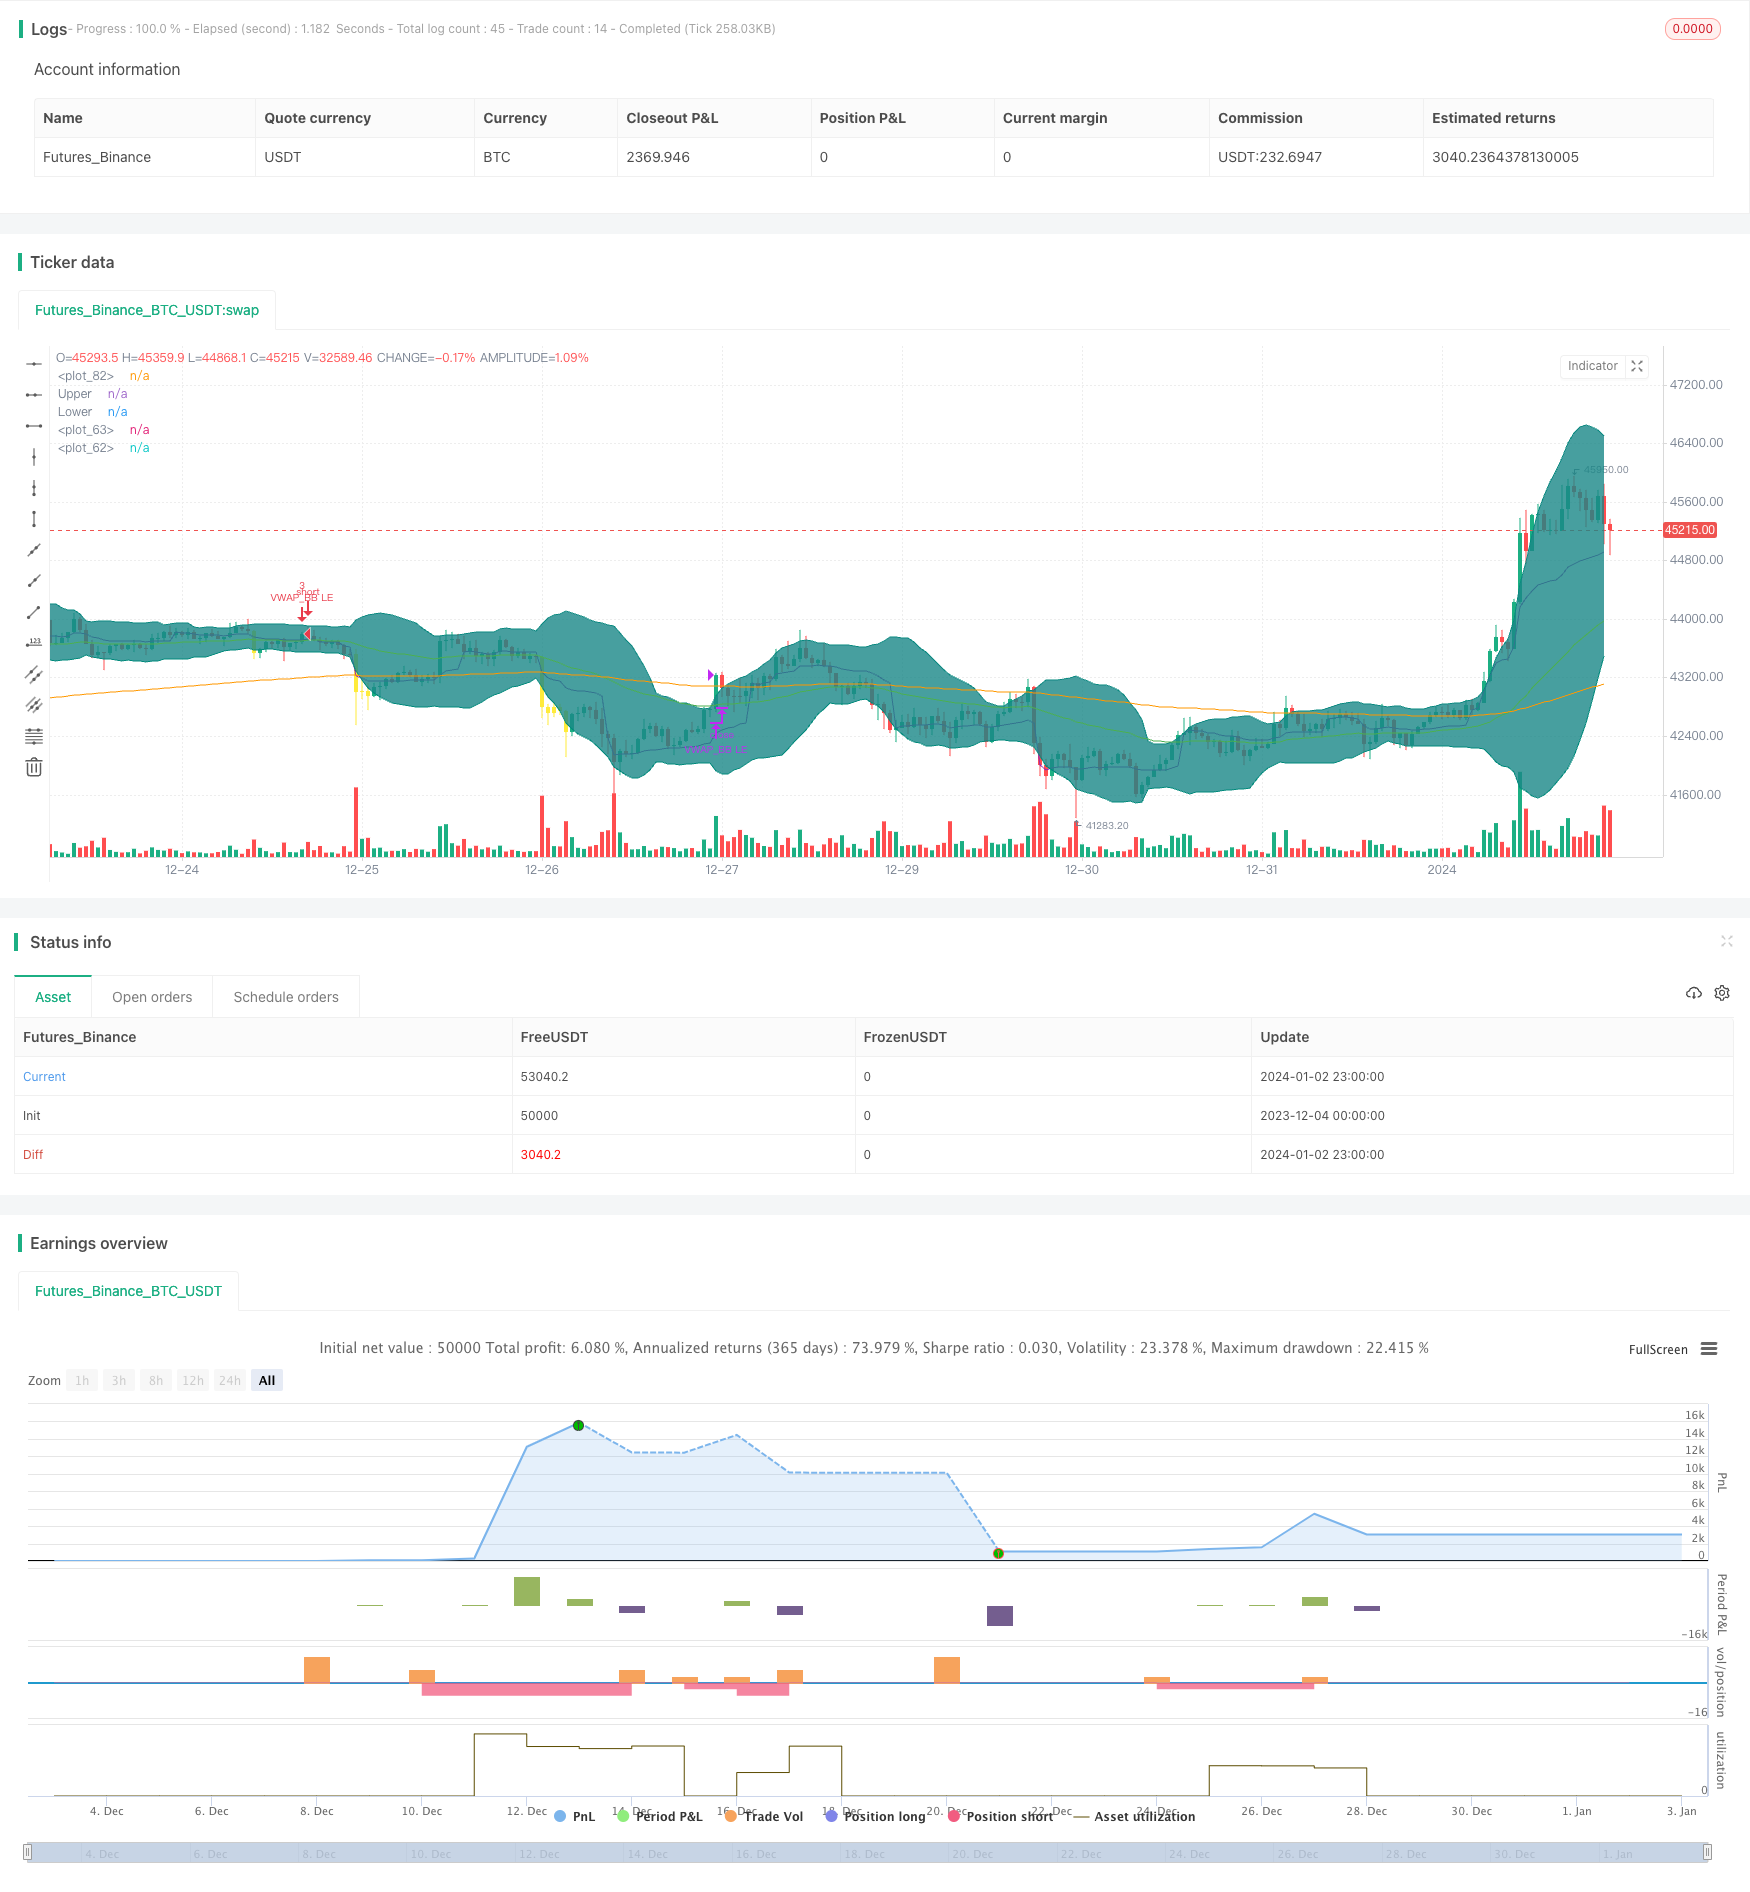
Overview
This strategy combines Bollinger Bands (BB) and Volume Weighted Average Price (VWAP) indicators to make entry and exit decisions. It can discover short-term price anomalies for trading and is suitable for short-term trading.
Strategy Logic
The strategy is mainly based on the following rules for entry and exit:
Fast EMA line above slow EMA line as prerequisite for judging trend
Buy when close price above VWAP indicating upward price
Enter long if close price dipped below BB lower band in last 10 bars indicating price anomaly
Sell when close price goes above BB upper band indicating price reversal
Specifically, it first judges if 50-day EMA is above 200-day EMA to determine the overall trend. Then combined with VWAP to judge if price is in a short-term uptrend. Finally using Bollinger Bands to detect short-term anomaly drop as entry opportunity.
The exit rule is simple, exit when price goes above BB upper band indicating price reversal.
Advantages Analysis
The strategy combines multiple indicators to increase validity of entry signals. Using EMAs to judge overall trend avoids trading against trend. VWAP captures short-term upward momentum. BB detects short-term anomalies as timing for entries.
Risk Analysis
- Inaccurate EMA trend judgment causing trading against trend
- VWAP more suitable for hourly or intraday data, less efficient in daily data
- Improper BB parameter setting, too wide or narrow bands missing signals
To mitigate the risks, parameters of EMA and BB can be adjusted. Test different indicators for trend detection. Use VWAP in lower timeframe. Optimize BB parameter for best bandwidth.
Enhancement Opportunities
- Test other indicators for trend detection like MACD
- Optimize EMA and BB parameters
- Add stop loss mechanism
- Add filters to avoid false signals
- Backtest on various products and timeframes
Conclusion
The strategy combines BB and VWAP to detect short-term price anomalies as entry timing. Using EMAs to determine overall trend avoids trading against trend. It can quickly discover short-term momentum. Suitable for intraday and short-term trading. Further enhance stability and profitability by optimizing parameters and incorporating more logic.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 50 | fast EMA |
| v_input_2 | 200 | slow EMA |
| v_input_3 | 20 | BB SMA Length |
| v_input_4_close | 0 | BB Source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_5 | 5 | Stop Loss% |
| v_input_6 | 2 | StdDev |
| v_input_7 | false | Offset |
Source Pine Script
/*backtest
start: 2023-12-04 00:00:00
end: 2024-01-03 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © mohanee

//@version=4
strategy(title="VWAP and BB strategy [EEMANI]", overlay=true,pyramiding=2, default_qty_value=3, default_qty_type=strategy.fixed,    initial_capital=10000, currency=currency.USD)
//This strategy combines VWAP and BB indicators
//BUY RULE
//1. EMA50 > EMA 200
//2. if current close > vwap session  value
//3. check if  price dipped BB lower band for any of last 10 candles
//EXIT RULE
//1. price closes above BB upper band
//STOP LOSS EXIT
//1. As configured --- default is set to 5%

is_price_dipped_bb(pds,source1) =>
    t_bbDipped=false
    for i=1 to pds
        t_bbDipped:=  (t_bbDipped   or  close[i]<source1) ? true : false
        if t_bbDipped==true
            break
        else
            continue

    t_bbDipped

// variables  BEGIN
shortEMA = input(50, title="fast EMA", minval=1)
longEMA = input(200, title="slow EMA", minval=1)

//BB

smaLength = input(20, title="BB SMA Length", minval=1)
bbsrc = input(close, title="BB Source")


//addOnDivergence = input(true,title="Add to existing on Divergence")
//exitOption = input(title="exit on RSI or BB", type=input.string, options=["RSI", "BB"],      defval="BB")

//bbSource = input(title="BB  source", type=input.string, options=["close", "vwap"],      defval="close")

//vwap_res = input(title="VWAP Resolution", type=input.resolution, defval="session")
stopLoss = input(title="Stop Loss%", defval=5, minval=1)

//variables  END


longEMAval= ema(close, longEMA)
shortEMAval= ema(close, shortEMA)


vwapVal=vwap(close)


// Drawings

//plot emas
plot(longEMAval, color = color.orange, linewidth = 1, transp=0)
plot(shortEMAval, color = color.green, linewidth = 1, transp=0)


//bollinger calculation
mult = input(2.0, minval=0.001, maxval=50, title="StdDev")
basis = sma(bbsrc, smaLength)
dev = mult * stdev(bbsrc, smaLength)
upperBand = basis + dev
lowerBand = basis - dev
offset = input(0, "Offset", type = input.integer, minval = -500, maxval = 500)
//bollinger calculation

//plot bb
//plot(basis, "Basis", color=#872323, offset = offset)
p1 = plot(upperBand, "Upper", color=color.teal, offset = offset)
p2 = plot(lowerBand, "Lower", color=color.teal, offset = offset)
fill(p1, p2, title = "Background", color=#198787, transp=95)


plot(vwapVal, color = color.purple, linewidth = 1, transp=0)


// Colour background

barcolor(shortEMAval>longEMAval and close<=lowerBand ? color.yellow: na)


//longCondition=  shortEMAval > longEMAval and  close>open and  close>vwapVal
longCondition= shortEMAval >= longEMAval  and  close>=vwapVal and close>open  //      close>vwapVal   and


//Entry
strategy.entry(id="VWAP_BB LE", comment="VB LE" , long=true,  when= longCondition and  is_price_dipped_bb(10,lowerBand) )  //and strategy.position_size<1

//add to the existing position
//strategy.entry(id="VWAP_RSI LE", comment="VR LE Add" , long=true,  when= addOnDivergence==true and strategy.position_size>=1 and close<strategy.position_avg_price   and (close<lowerBand or  low<lowerBand) and rsiVal>rsi_buy_line)

barcolor(strategy.position_size>=1  ? color.blue: na)


strategy.close(id="VWAP_BB LE", comment="TP Exit VB LE",   when=crossover(close,upperBand) )

//stoploss
stopLossVal =   strategy.position_avg_price * (1-(stopLoss*0.01) )
strategy.close(id="VB LE", comment="SL Exit",   when= close < stopLossVal)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-04. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Bollinger-Bands-and-VWAP-based-Quantitative-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Advanced 15 Minute Chart Trading Signal StrategyPine Script · Mean reversion · 3h
- Reversal Catcher StrategyPine Script · Mean reversion · 1h
- A Momentum Tracking Mean Reversion StrategyPine Script · Mean reversion · 1h
- CCTBBO Reversal Tracking StrategyPine Script · Mean reversion · 45m
- Market Cypher Wave B Automated Trading StrategyPine Script · Mean reversion · 1h
- MACD RSI and EMA StrategyPine Script · Mean reversion · 1d