Breakthrough Tracking Strategy
This strategy is designed for 5-minute K-lines of bank indices and indices to track breakthroughs. It can generate signals when breakthroughs occur for buy or sell operations.
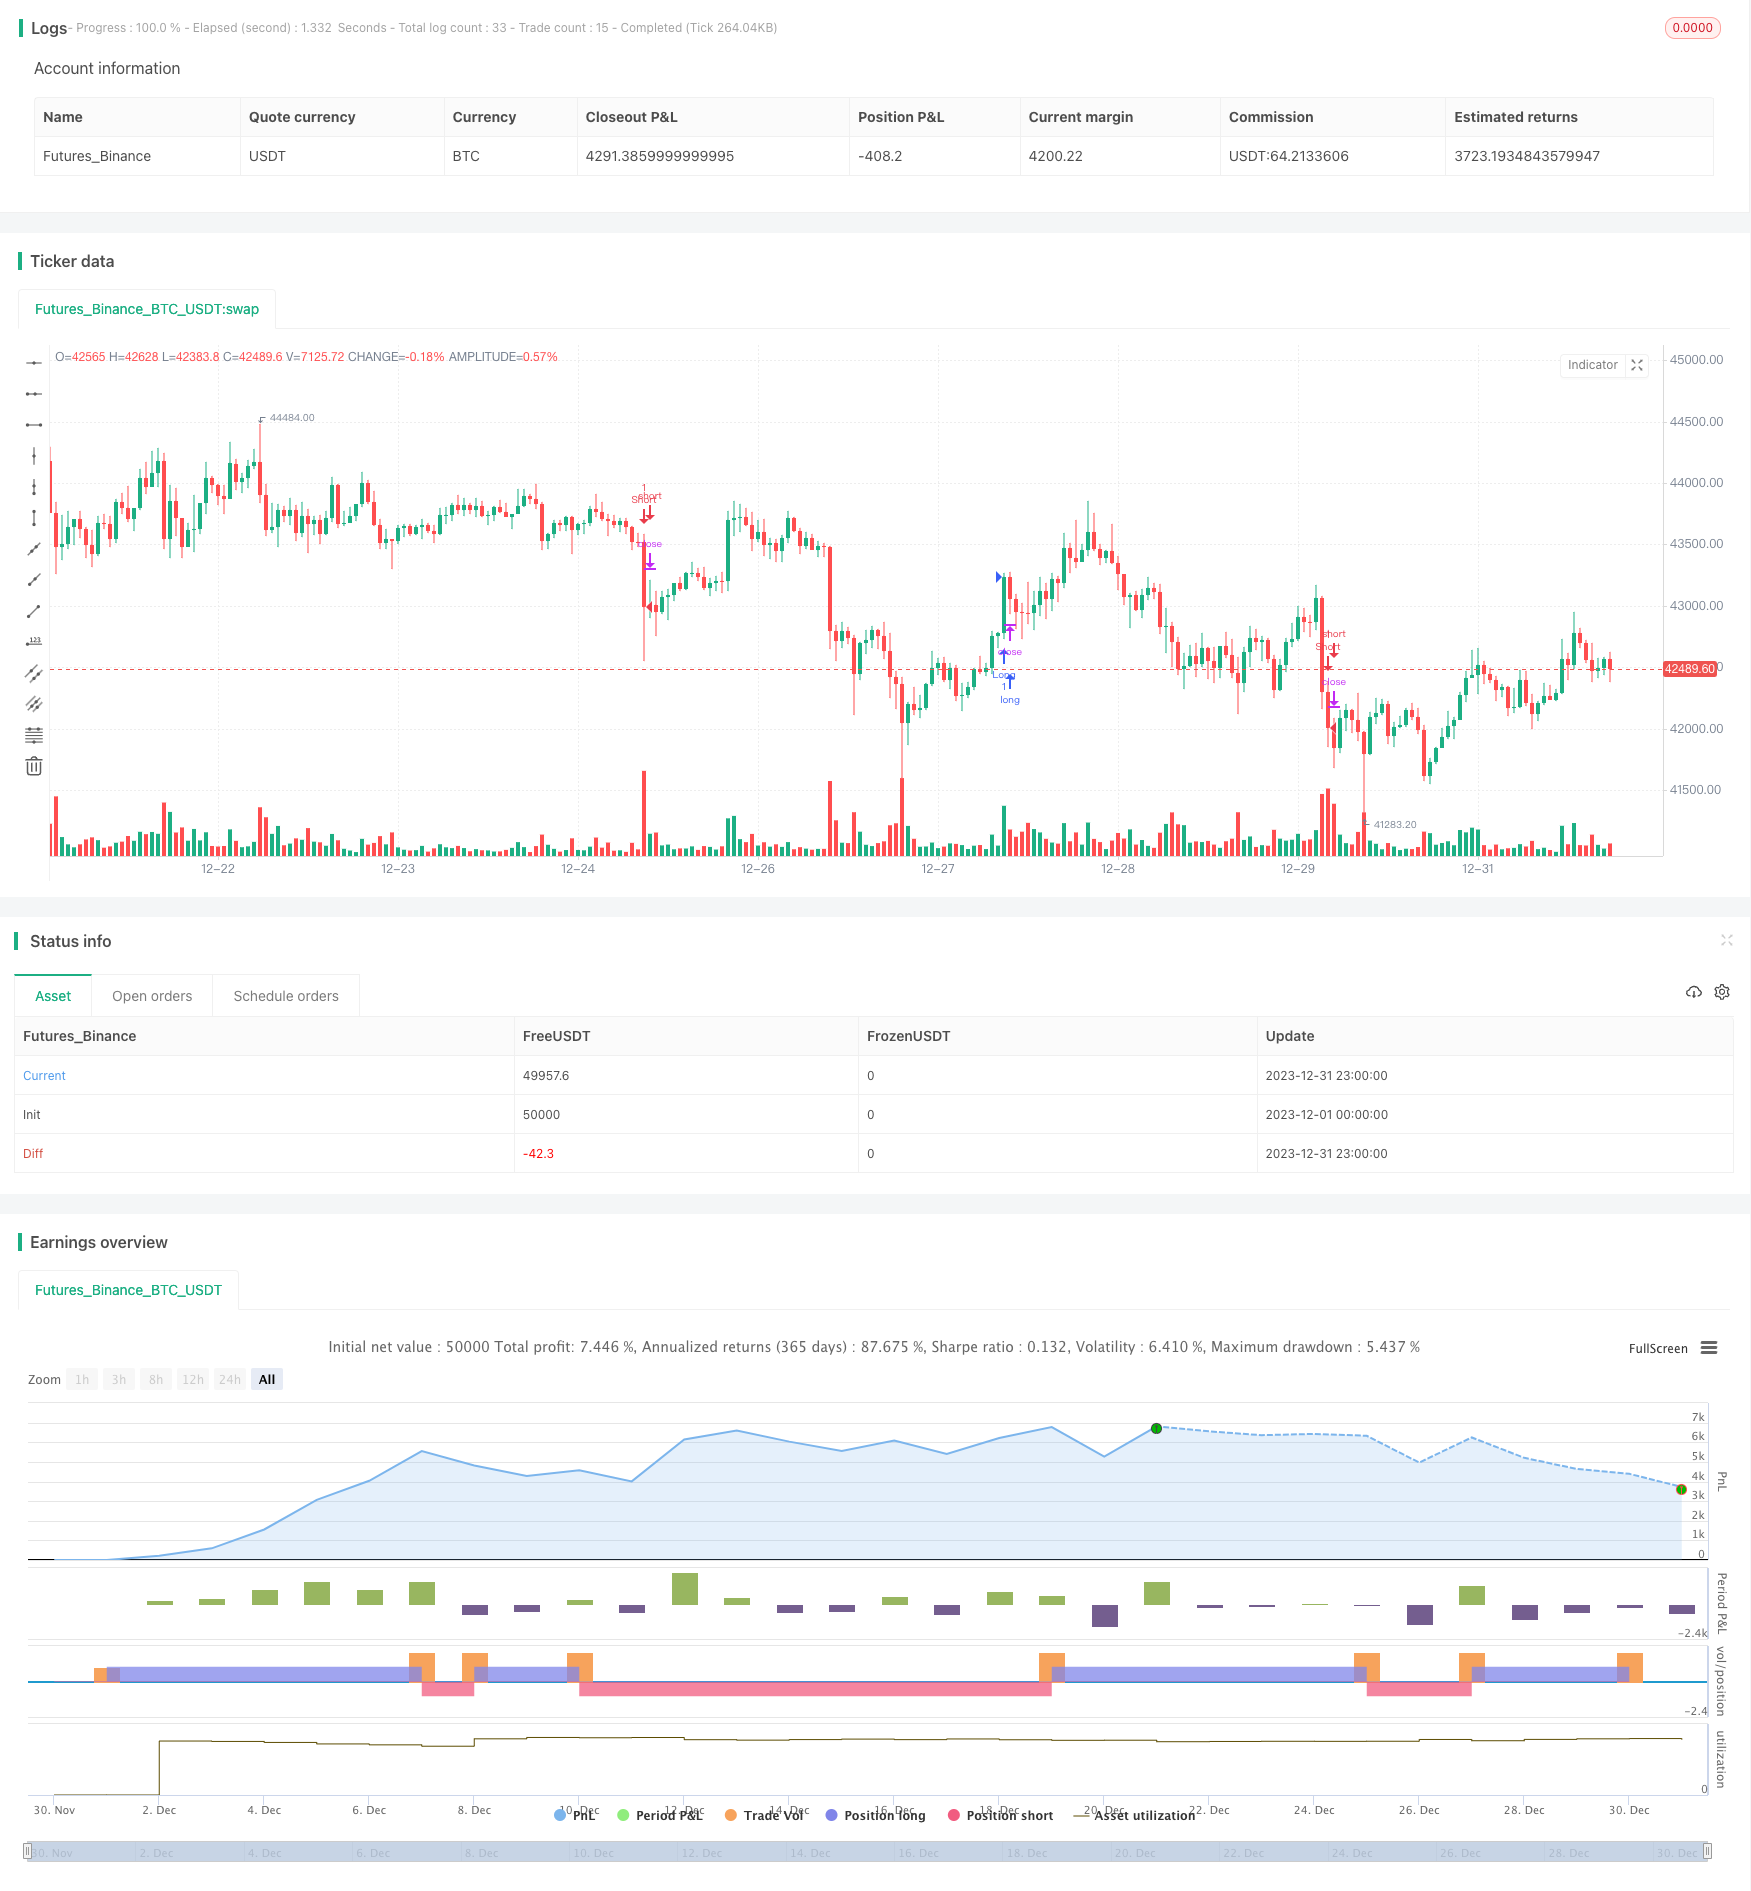
Overview
This strategy is designed for 5-minute K-lines of bank indices and indices to track breakthroughs. It can generate signals when breakthroughs occur for buy or sell operations.
Strategy Principle
This strategy calculates the highest and lowest price indicators to judge if the price breaks through the highest and lowest price range. If the price breaks through this range, it will generate buy or sell signals. To filter out some noise, it also uses auxiliary indicators for confirmation.
Advantage Analysis:
- This strategy responds quickly and can enter the market immediately when a breakthrough occurs.
- By double filtering through the high and low price range and auxiliary indicators, some false breakthroughs can be avoided.
- This strategy has no lagging as it has non-repetitive indicators.
Risk Analysis:
- If there is a huge swing in the market, this strategy may generate reverse signals, leading to losses.
- Simple breakthrough strategies are easy to fall into traps and need to be wary of breakthrough failures.
Optimization Directions:
- Trend indicators can be combined to avoid reverse operations.
- A stop-loss mechanism can be added to control single losses.
Summary
This strategy looks for trading opportunities by judging whether prices break through the high and low price range. It responds quickly and avoids lagging but also faces risks such as breakthrough failures and traps. Through optimization, this strategy can achieve better performance in trending markets.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1_close | 0 | price: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_2 | 26 | LookBack |
| v_input_3 | 10 | length |
| v_input_4 | true | length2 |
Source Pine Script
/*backtest
start: 2023-12-01 00:00:00
end: 2023-12-31 23:59:59
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4
strategy(title="MARKET DYNAMICS HH LL BREAKOUT", shorttitle="BREAKOUT STRATEGY", overlay=true)

////


//Higher High or Lower Low Entry Inputs
price = input(close)
LookBack = input(26)
Highest = highest(LookBack)
Lowest = lowest(LookBack)

long = price > Highest[1]
short = price < Lowest[1]


//Safety Confirmation Inputs - Helps to thin out false breakouts or break downs
length = input(10)
High_Guard = highest(length)
Low_Guard = lowest(length)
length2 = input(1)

long1 = long == 1 and Highest[1] > High_Guard[length2]
short1 = short == 1 and Lowest[1] < Low_Guard[length2]


strategy.entry("Long", strategy.long, when=long1)
strategy.entry("Short", strategy.short, when=short1)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-05. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Breakthrough-Tracking-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- 5 Day Moving Average Channel Breakout Strategy Combined With Mileage ConceptPine Script · Breakout · 1d
- ATR Trailing Stops StrategyPine Script · Breakout · 1h
- ATR Trend Breakout StrategyPine Script · Breakout · 1d
- Adaptive Bollinger Breakout with Moving Average Quantitative Strategy SystemPine Script · Breakout · 1h
- Adaptive Channel Breakout StrategyPine Script · Breakout · 1d
- Adaptive Multi Period Trading Strategy Based on Wave Trend Momentum BreakoutPine Script · Breakout · 2h