Strategy vault / Mean reversion
BuySell Strategy depends on AOStochRSIATR
This strategy is just for training, its purpose is just learning code in pine script. Don't make buy or sell decision with this strategy. Turkish/Turkce Bu strateji sadece pine script'te kodlamanın nasıl yapildigini…
This strategy is just for training, its purpose is just learning code in pine script. Don't make buy or sell decision with this strategy.
Turkish/Turkce Bu strateji sadece pine script'te kodlamanın nasıl yapildigini ogrenmek icindir. Bu stratejiye dayanarak, kesinlikle al-sat islemleri yapmayin.
How it works?
When RSI and Stoch are in oversold area and if awesome osc. turns positive, take long position. Stop loss and take profit levels were defined with ATR ind.
When RSI and Stoch are in overbought are and if awesome osc. turns negative, take short position. Stop loss and take profit levels were defined with ATR ind.
Turkish/Turkce
RSI ve Stoch asiri satım bölgesinde iken awesome pozitife döner ise long pozisyon açar, zarar kes ve kar al seviyeleri ATR indikatoru ile tanımlandı.
RSI ve Stoch asırı alım bölgesinde iken awesome negatife döner ise short pozisyon açar, zarar kes ve kar al seviyeleri ATR indikatoru ile tanımlandı.
backtest
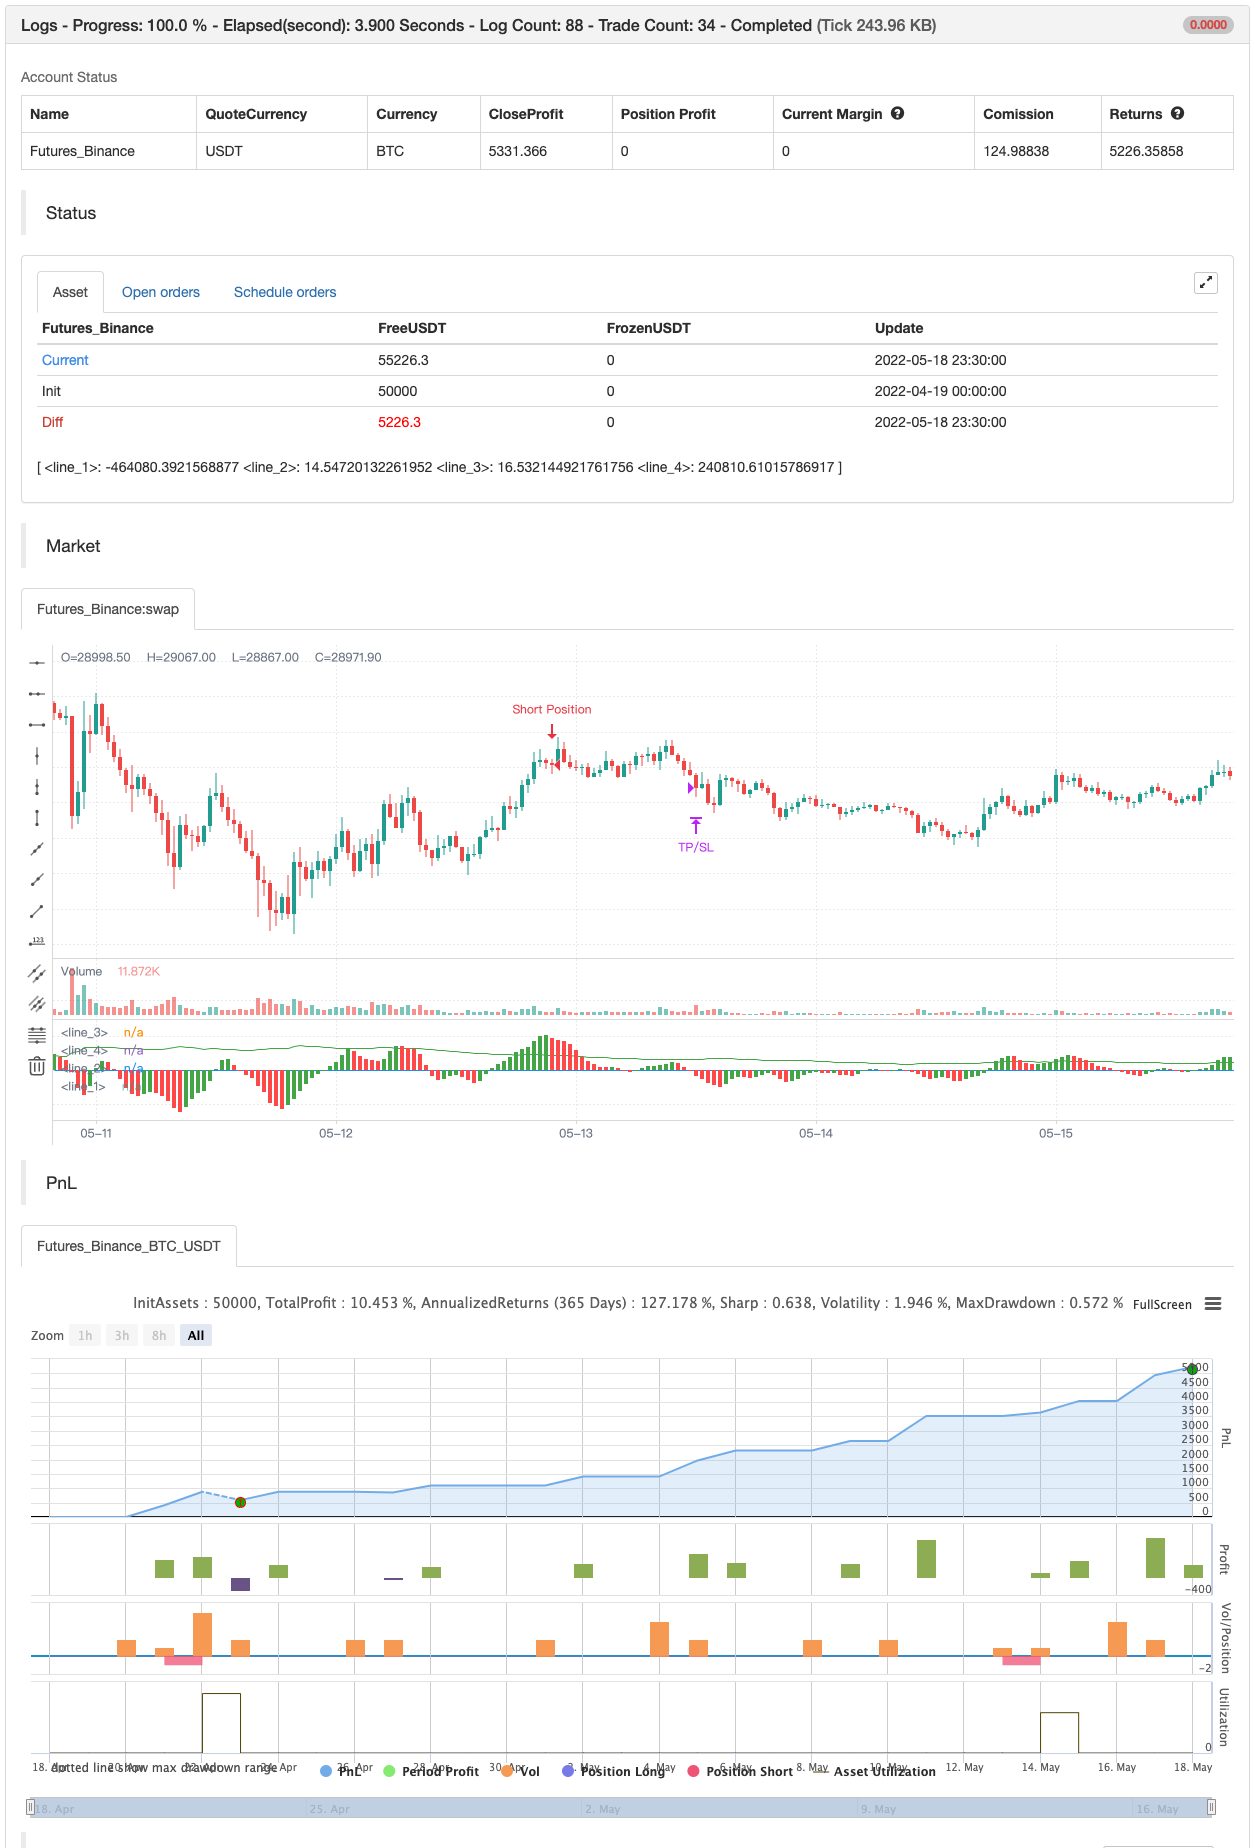
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 3 | Fast Length |
| v_input_2 | 17 | Slow length |
| v_input_3 | 14 | K |
| v_input_4 | 3 | D |
| v_input_5 | 3 | smooth |
| v_input_6_low | 0 | rsi source: low | high | close | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_7 | 10 | rsi length |
| v_input_8 | 14 | ATR Length |
Source Pine Script
/*backtest
start: 2022-04-19 00:00:00
end: 2022-05-18 23:59:00
period: 30m
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4

strategy("Buy&Sell Strategy depends on AO+Stoch+RSI+ATR by SerdarYILMAZ", shorttitle="Buy&Sell Strategy")
// Created by Serdar YILMAZ
// This strategy is just for training, its purpose is just learning code in pine script.
// Don't make buy or sell decision with this strategy.
// Bu strateji sadece pine script'te kodlamanın nasıl yapildigini ogrenmek icindir.
// Bu stratejiye dayanarak, kesinlikle al-sat islemleri yapmayin.

//AO

fast=input(title="Fast Length",type=input.integer,defval=3)
slow=input(title="Slow length",type=input.integer,defval=17)

awesome=(sma(hl2,fast)-sma(hl2,slow))*1000

plot(awesome, style=plot.style_histogram, color=(awesome>awesome[1]?color.green:color.red))

//Stoch

K=input(title="K",type=input.integer,defval=14)
D=input(title="D",type=input.integer,defval=3)
smooth=input(title="smooth",type=input.integer,defval=3)

k=sma(stoch(close,high,low,K),D)
d=sma(k,smooth)

hline(80)
hline(20)

plot(k,color=color.blue)

//RSI

rsisource=input(title="rsi source",type=input.source,defval=low)
rsilength=input(title="rsi length",type=input.integer,defval=10)

rsi=rsi(rsisource,rsilength)

hline(70,color=color.orange)
hline(30,color=color.orange)

plot(rsi,color=color.orange)

//ATR

atrlen=input(title="ATR Length", type=input.integer,defval=14)

atrvalue=rma(tr,atrlen)

plot(atrvalue*1000,color=color.green)

LongCondition=k<20 and rsi<30 and awesome>awesome[1]
ShortCondition=k>80 and rsi>70 and awesome<awesome[1]
if (LongCondition)
    stoploss=low-atrvalue
    takeprofit=close+atrvalue
    strategy.entry("Long Position", strategy.long)
    strategy.exit("TP/SL",stop=stoploss,limit=takeprofit)

if (ShortCondition)
    stoploss=high+atrvalue
    takeprofit=close-atrvalue
    strategy.entry("Short Position",strategy.short)
    strategy.exit("TP/SL",stop=stoploss,limit=takeprofit)
Published by ChaoZhang on the FMZ strategy square · last modified 2022-05-20. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/BuySell-Strategy-depends-on-AOStochRSIATR.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Dual Momentum Trend Reversal Strategy Based on RSI and Stochastic RSIPine Script · Mean reversion · 1h
- Dynamic Adaptive Multi Timeframe Trend Following and Range Reversal Hybrid StrategyPine Script · Mean reversion · 2d
- Momentum Reversal Trading Strategy 428631Pine Script · Mean reversion · 2h
- Moving Average and Stochastic RSI Combination Trading StrategyPine Script · Mean reversion · 1d
- Oma and Apollo Dual Rail Trading StrategyPine Script · Mean reversion · 5m
- 3EMA with Stochastic RSI StrategyPine Script · Mean reversion · 1h