Bybit Algorithm Needle Connection VWAP BTC
Start sharing the original Bybit penetration strategy here~ What is the main reason?/// This is very annoying, isn't it?... You said you were doing good open source and got angry without even knowing about it... Hope…
Start sharing the original Bybit penetration strategy here~
What is the main reason?///
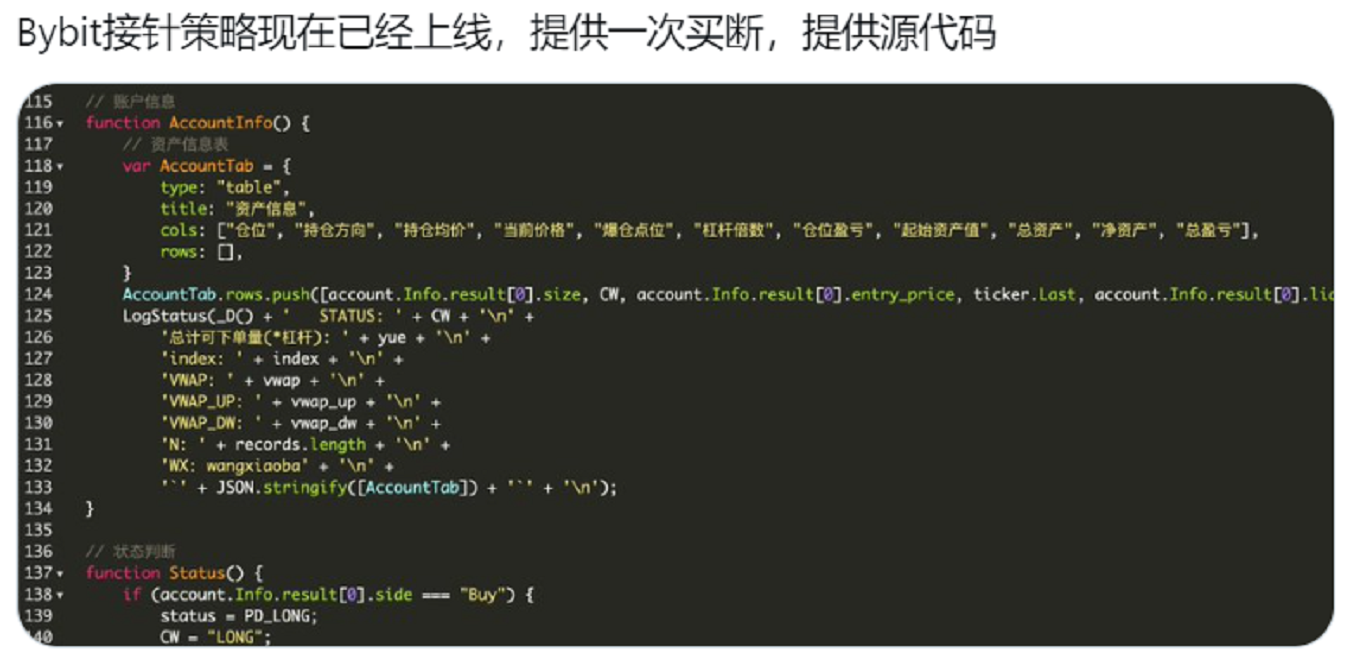
This is very annoying, isn't it?... You said you were doing good open source and got angry without even knowing about it... Hope the little brother doesn't do this anymore~ Open source directly here, It itself is not really an impressive strategy...
Everyone is free to play.~ Stop spending money to buy my crappy source code~ Let's use it directly!! Let's go!!
By the way, a quick advertisement~ For more money-losing strategies, please follow the public account "Bean's Quantitative Journal"" WX: wangxiaoba
(●'◡'●)
Parameters
| Name | Default | What it controls |
|---|---|---|
| start_balance | false | Initial amount |
| long_qty | true | Single long positionUSD |
| short_qty | true | Single short positionUSD |
| maxPosition | 500000 | Maximum Order Quantity |
| take_profit | 45 | Initial take profit(USD) |
| trailing_profit | true | Trailing take profitUSD |
| stop_loss | 9 | Stop Loss Percentage |
| long_vwap_offset | 2.5 | VWAPUpper Limit Percentage |
| short_vwap_offset | 2.5 | VWAPLower Limit Percentage |
| GG | 3 | leverage multiplier (2x-7x is suitable, the higher the leverage, the greater the risk)) |
| stop_step | 3600 | Stop time after stop loss(s) |
Source JavaScript
// JudgmentuidPermissions (UID list + getAccount uid Verification)
function user_auth() {
    user_list = [775536, 783571, 789086, 819490, 1265698, 1294567, 1299150]
    user_id = account.Info.result[0].user_id
    //Log(user_id)
    if (user_list.indexOf(user_id) == -1) {
        throw new Error('User authentication error, please contact WeChat: wangxiaoba')
    }
}

// Calculate acquisitionVWAPAnd Upper & Lower Boundaries Bybit
function VWAP() {
    // DefinitionKLine, CalculationVWAP
    if (records.length > 1440) {
        records.splice(0, 1);
    }
    var n = records.length - 1
    //Log(n)
    var total_sum = 0.0
    var volume_sum = 0
    vwap_arr = []
    vwap_up_arr = []
    vwap_dw_arr = []
    for (var i = 0; i < n + 1; i++) {
        var high_price = records[i].High
        //Log("log high_price " + high_price)
        var low_price = records[i].Low
        var close_price = records[i].Close
        //Log("log low_price " + low_price)
        var price = (high_price + low_price + close_price) / 3
        //Log("price", price)
        var volume = records[i].Volume
        //Log("log volume " + volume)
        total_sum += price * volume
        //Log("log total_sum " + total_sum)
        volume_sum += volume
        //Log("log volume_sum " + volume_sum)
        var re = total_sum / volume_sum
        var re_up = re * (1 + long_vwap_offset / 100)
        var re_dw = re * (1 - short_vwap_offset / 100)
        vwap_arr.push(re)
        vwap_up_arr.push(re_up)
        vwap_dw_arr.push(re_dw)
        //return total_sum / volume_sum
    }
    if (vwap_arr.length > 2000) {
        vwap_arr.splice(0, 1);
    }
    if (vwap_up_arr.length > 2000) {
        vwap_up_arr.splice(0, 1);
    }
    if (vwap_dw_arr.length > 2000) {
        vwap_dw_arr.splice(0, 1);
    }
    vwap = vwap_arr[vwap_arr.length - 1]
    vwap_up = vwap_up_arr[vwap_arr.length - 1]
    vwap_dw = vwap_dw_arr[vwap_arr.length - 1]
    //Log("log vwap " + vwap, "log vwap_up " + vwap_up, "log vwap_dw " + vwap_dw)
}

// Draw lines
function PlotMA_Kline(records, isFirst) {
    $.PlotRecords(records, "K")
    if (isFirst) {
        for (var i = records.length - 1; i >= 0; i--) {
            if (vwap_arr[i] !== null) {
                $.PlotLine("vwap", vwap_arr[i], records[i].Time)
                $.PlotLine("vwap_up", vwap_up_arr[i], records[i].Time)
                $.PlotLine("vwap_dw", vwap_dw_arr[i], records[i].Time)
            }
        }
        PreBarTime = records[records.length - 1].Time
    } else {
        if (PreBarTime !== records[records.length - 1].Time) {
            $.PlotLine("vwap", vwap_arr[vwap_arr.length - 2], records[records.length - 2].Time)
            $.PlotLine("vwap_up", vwap_up_arr[vwap_up_arr.length - 2], records[records.length - 2].Time)
            $.PlotLine("vwap_dw", vwap_dw_arr[vwap_dw_arr.length - 2], records[records.length - 2].Time)
            PreBarTime = records[records.length - 1].Time
        }
        $.PlotLine("vwap", vwap_arr[vwap_arr.length - 1], records[records.length - 1].Time)
        $.PlotLine("vwap_up", vwap_up_arr[vwap_up_arr.length - 1], records[records.length - 1].Time)
        $.PlotLine("vwap_dw", vwap_dw_arr[vwap_dw_arr.length - 1], records[records.length - 1].Time)
    }
}

// Encapsulate order, Many, Empty Bybit
// DefinitionBuy
function buy(Price, Amount, dec) {
    exchange.SetDirection("buy");
    var orderId = null;
    orderId = exchange.Buy(Price, Amount, dec, '@');
    while (!orderId && typeof(orderId) != "undefined" && orderId != 0) {
        Log(orderId);
        Sleep(100);
        orderId = exchange.Buy(Price, Amount, dec, '@');

    }
    return orderId;
}

// DefinitionSell
function sell(Price, Amount, dec) {
    exchange.SetDirection("sell");
    var orderId = null;
    orderId = exchange.Sell(Price, Amount, dec, '@');
    while (!orderId && typeof(orderId) != "undefined" && orderId != 0) {
        Log(orderId);
        Sleep(100);
        orderId = exchange.Sell(Price, Amount, dec, '@');

    }
    return orderId;
}

// Account Information
function AccountInfo() {
    // Asset Information Table
    var AccountTab = {
        type: "table",
        title: "Asset information",
        cols: ["Position", "Position direction", "Average position price", "Current price", "Liquidation point", "Leverage multiple", "Position profit and loss", "Starting asset value", "Total assets", "Net assets", "Total profit and loss""],
        rows: [],
    }
    AccountTab.rows.push([account.Info.result[0].size, CW, account.Info.result[0].entry_price, ticker.Last, account.Info.result[0].liq_price, account.Info.result[0].leverage, account.Info.result[0].unrealised_pnl, start_balance, account.Info.result[0].wallet_balance, jzc, pt])
    LogStatus(_D() + '   STATUS: ' + CW + '\n' +
        'Total orderable quantity(*leverage): ' + yue + '\n' +
        'index: ' + index + '\n' +
        'VWAP: ' + vwap + '\n' +
        'VWAP_UP: ' + vwap_up + '\n' +
        'VWAP_DW: ' + vwap_dw + '\n' +
        'N: ' + records.length + '\n' +
        'WX: wangxiaoba' + '\n' +
        '`' + JSON.stringify([AccountTab]) + '`' + '\n');
}

// Status judgment
function Status() {
    if (account.Info.result[0].side === "Buy") {
        status = PD_LONG;
        CW = "LONG";
    } else if (account.Info.result[0].side === "Sell") {
        status = PD_SHORT;
        CW = "SHORT";
    } else {
        status = idle;
        CW = "IDLE";
    }
}

// Trailing Take Profit Initial%, TrackingU
function TP() {
    var TP_first_long = account.Info.result[0].entry_price + take_profit
    var TP_trailing_long = TP_HH - trailing_profit
    var TP_first_short = account.Info.result[0].entry_price - take_profit
    var TP_trailing_short = TP_LL + trailing_profit
    // When holding a long position, Current price greater than opening+Initial Take Profit Price -> Trigger trailing take profit
    if ((status === PD_LONG) && (ticker.Last > TP_first_long)) {
        // Log('When holding a long position, Current price greater than opening+Initial Take Profit Price -> Trigger trailing take profit', TP_HH)
        TP_status = true
        // Trigger trailing take profit, Uninitialized maximum opening price -> After opening a position, update the maximum price to the current price
        if (TP_status === true && TP_HH == 0) {
            Log('Trigger trailing take profit, Uninitialized maximum opening price -> After opening a position, update the maximum price to the current price', TP_HH)
            TP_HH = ticker.Last
        }
        // Trigger trailing take profit, Maximum price after existing positions opened, The current price is greater than the maximum price after opening the position -> After opening a position, update the maximum price to the current price
        else if (TP_status === true && TP_HH != 0 && ticker.Last > TP_HH) {
            Log('Trigger trailing take profit, Maximum price after existing positions opened, The current price is greater than the maximum price after opening the position -> After opening a position, update the maximum price to the current price', TP_HH)
            TP_HH = ticker.Last
        }
        // Trigger trailing take profit, Maximum price after existing positions opened, Current price is less than (Maximum price reduction after opening a position - RetracementUSD) -> Close short position with take profit
        else if (TP_status === true && TP_HH != 0 && ticker.Last < TP_trailing_long) {
            Log('Trigger trailing take profit, Maximum price after existing positions opened, Current price is less than (Maximum price reduction after opening a position - RetracementUSD) -> Close short position with take profit', TP_HH)
            sell(-1, account.Info.result[0].size, "At/In" + ticker.Last + "Take Profit Close Long Position!! Opening price: " + account.Info.result[0].entry_price + "Quantity: " + account.Info.result[0].size)
            status = idle
            $.PlotFlag(new Date().getTime(), 'Close_Long', 'PT_L')
            TP_status = false
            TP_HH = 0
            LogProfit(pt, pt * ticker.Last)
        }
    }
    // When holding a short position, Current price less than opening-Initial Take Profit Price -> Trigger trailing take profit
    else if ((status === PD_SHORT) && (ticker.Last < TP_first_short)) {
        // Log('When holding a short position, Current price less than opening-Initial Take Profit Price -> Trigger trailing take profit', TP_LL)
        TP_status = true
        // Trigger trailing take profit, Uninitialized maximum opening price -> After opening a position, update the minimum price to the current price
        if (TP_status === true && TP_LL == 0) {
            Log('Trigger trailing take profit, Uninitialized maximum opening price -> After opening a position, update the minimum price to the current price', TP_LL)
            TP_LL = ticker.Last
        }
        // Trigger trailing take profit, Minimum price after existing positions opened, The current price is less than the minimum price after opening the position -> After opening a position, update the minimum price to the current price
        else if (TP_status === true && TP_LL != 0 && ticker.Last < TP_LL) {
            Log('Trigger trailing take profit, Minimum price after existing positions opened, The current price is less than the minimum price after opening the position -> After opening a position, update the minimum price to the current price', TP_LL)
            TP_LL = ticker.Last
        }
        // Trigger trailing take profit, Minimum price after existing positions opened, Current price is greater than (After opening a position, the minimum price is reduced + RetracementUSD) -> Close long position with take profit
        else if (TP_status === true && TP_LL != 0 && ticker.Last > TP_trailing_short) {
            Log('Trigger trailing take profit, Minimum price after existing positions opened, Current price is greater than (After opening a position, the minimum price is reduced + RetracementUSD) -> Close long position with take profit', TP_LL)
            buy(-1, account.Info.result[0].size, "At/In" + ticker.Last + "Take Profit Close Short Position!! Opening price: " + account.Info.result[0].entry_price + "Quantity: " + account.Info.result[0].size)
            status = idle
            $.PlotFlag(new Date().getTime(), 'Close_Short', 'PT_S')
            TP_status = false
            TP_LL = 0
            LogProfit(pt, pt * ticker.Last)
        }
    }
}

// stop loss %
function Stoploss() {
    // When holding a long position, Current price less than opening-Stop loss price, Short to close long
    if ((status === PD_LONG) && (ticker.Last < account.Info.result[0].entry_price - (ticker.Last * stop_loss / 100))) {
        Log('When holding a long position, Current price less than opening-Stop loss price, Short to close long')
        sell(-1, account.Info.result[0].size, "At/In" + ticker.Last + "Stop Loss Close Long Position!! Opening price: " + account.Info.result[0].entry_price + " Quantity: " + account.Info.result[0].size)
        status = idle
        isstoploss = true
        $.PlotFlag(new Date().getTime(), 'Close_Long', 'ST_L')
        LogProfit(pt, pt * ticker.Last)
    }
    // When holding a short position, Current price greater than opening+Stop loss price, Long to close short
    else if ((status === PD_SHORT) && (ticker.Last > account.Info.result[0].entry_price + (ticker.Last * stop_loss / 100))) {
        Log('When holding a short position, Current price greater than opening+Stop loss price, Long to close short')
        buy(-1, account.Info.result[0].size, "At/In" + ticker.Last + "Stop Loss Close Short Position!! Opening price: " + account.Info.result[0].entry_price + " Quantity: " + account.Info.result[0].size)
        status = idle
        isstoploss = true
        $.PlotFlag(new Date().getTime(), 'Close_Short', 'ST_S')
        LogProfit(pt, pt * ticker.Last)
    }
}

function AtrIndex() {
    if (records && records.length > 14) {
        var atr = TA.ATR(records, 14)
    }
    if (atr && atr.length > 20) {
        var eamatr = TA.EMA(atr, 20)
        // Log(eamatr[eamatr.length - 1])
    }
    if (eamatr){
        var temp = 0
        for(var i=0; i<eamatr.length; i++){
            temp += atr[atr.length - 1]/eamatr[eamatr.length - 1]
        }
    }
    index = _N((temp/eamatr.length), 4)
}


// Calculate income
function PT_log() {
    time = new Date().getTime();
    if (time >= (timep + 7200000)) {
        LogProfit(pt, pt * ticker.Last);
        timep = time;
    }
}


function main() {
    // Initialize parameters
    PreBarTime = 0
    isFirst = true
    exchange.SetMarginLevel(GG)
    exchange.SetContractType('swap');
    _CDelay(100);
    idle = -1;
    status = idle;
    CW = 0;
    timep = 0;
    TP_status = false // Whether to trigger trailing take profit
    TP_HH = 0
    TP_LL = 0
    isstoploss = false
    index = 0
    // WS Configuration
    var param = {
        "op": "subscribe",
        "args": "liquidation"
    }
    var client = Dial("wss://www.bitmex.com/realtime|reconnect=true&payload=" + JSON.stringify(param), 3800)
    client.write('{"op": "subscribe", "args": "liquidation"}')
    while (1) {
        // Define basic information
        account = _C(exchange.GetAccount)
        records_5m = _C(exchange.GetRecords, PERIOD_M5)
        records = _C(exchange.GetRecords, PERIOD_M1)
        ticker = _C(exchange.GetTicker)
        yue = account.Info.result[0].wallet_balance * ticker.Last * GG; // Total openable position (Wallet coins x Latest price x Leverage))
        jzc = account.Info.result[0].wallet_balance + account.Info.result[0].unrealised_pnl; // Net asset amount (total assets - unrealized P&L))
        pt = jzc - start_balance; // Profit (Net Assets - Initial Coin Amount)
        //Log('Initialize')
        // Status judgment
        Status()
        //Log('Status judgment')
        // Permission verification
        // user_auth()
        //Log('Permission verification')
        // Packaging indicators, Parallel drawingKLine
        AtrIndex()
        VWAP()
        //Log('Indicator packaging')
        if (records) {
            PlotMA_Kline(records_5m, isFirst)
            //Log('Draw lines')
            isFirst = false
        }
        // ReadWSMessage
        bitmexData = client.read(-1)
        obj = null
        //Log('ReadWSMessage')
        if (bitmexData) {
            obj = JSON.parse(bitmexData)
            //Log('bitmex liquidation Data ', obj)
        }
        //Log('ReadWSMessage completed')
        // Order logic!
        // Determine trading pair, and liquidation value (BTC>100000, ETH>7500 , EOS?? , XRP??) {"table":"liquidation","action":"insert","data":[{"orderID":"77e987c5-03c2-814e-0fb3-5632f9438f31","symbol":"XBTUSD","side":"Buy","price":9938,"leavesQty":32618}]}
        // trading pair
        if (obj) {
            if (obj.table == "liquidation" && obj.action == "insert" && obj.data[0].symbol == "XBTUSD") {
                // Log('Determine trading pair')
                // Direction and size
                // When liquidation direction isBuy, Liquidation amount greater than10W, Latest price greater thanvwapUpper bound time, is less than the maximum opening amount!! go short
                if (obj.data[0].side == "Buy" && obj.data[0].leavesQty > 250000 && ticker.Last > vwap_up && account.Info.result[0].size < maxPosition) {
                    Log('Determine size direction, Empty')
                    sell(-1, short_qty, "At/In" + ticker.Last + "- go short " + short_qty + "|")
                    $.PlotFlag(new Date().getTime(), 'Sell', 'SK')
                }
                // When liquidation direction isSell, Liquidation amount greater than10W, Latest price less thanvwapNether time, is less than the maximum opening amount!! go long
                else if (obj.data[0].side == "Sell" && obj.data[0].leavesQty > 250000 && ticker.Last < vwap_dw && account.Info.result[0].size < maxPosition) {
                    Log('Determine size direction, Many')
                    buy(-1, long_qty, "At/In" + ticker.Last + "- go long " + long_qty + "|")
                    $.PlotFlag(new Date().getTime(), 'Buy', 'BK')
                }
            }
        }
        // stop loss
        Stoploss()
        if (isstoploss === true) {
            Log("Trigger stop loss, Pause after stop loss!! " + stop_step + "s!!!")
            AccountInfo()
            Sleep(stop_step * 1000)
            isstoploss = false
        }
        //Log('stop loss')
        // Trailing take profit
        TP()
        //Log('Trailing take profit')
        // Account information update
        AccountInfo()
        // Interval time
        //Log('Interval time')
        Sleep(600);
    }
}Published by 扁豆子 on the FMZ strategy square · last modified 2021-01-29. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Bybit-Algorithm-Needle-Connection-VWAP-BTC.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.