Center of Gravity Backtesting Trading Strategy
The Center of Gravity backtesting trading strategy is a trading strategy based on moving averages. It calculates the "center" of the price, i.e. the position of the center of gravity, and constructs price channels as…
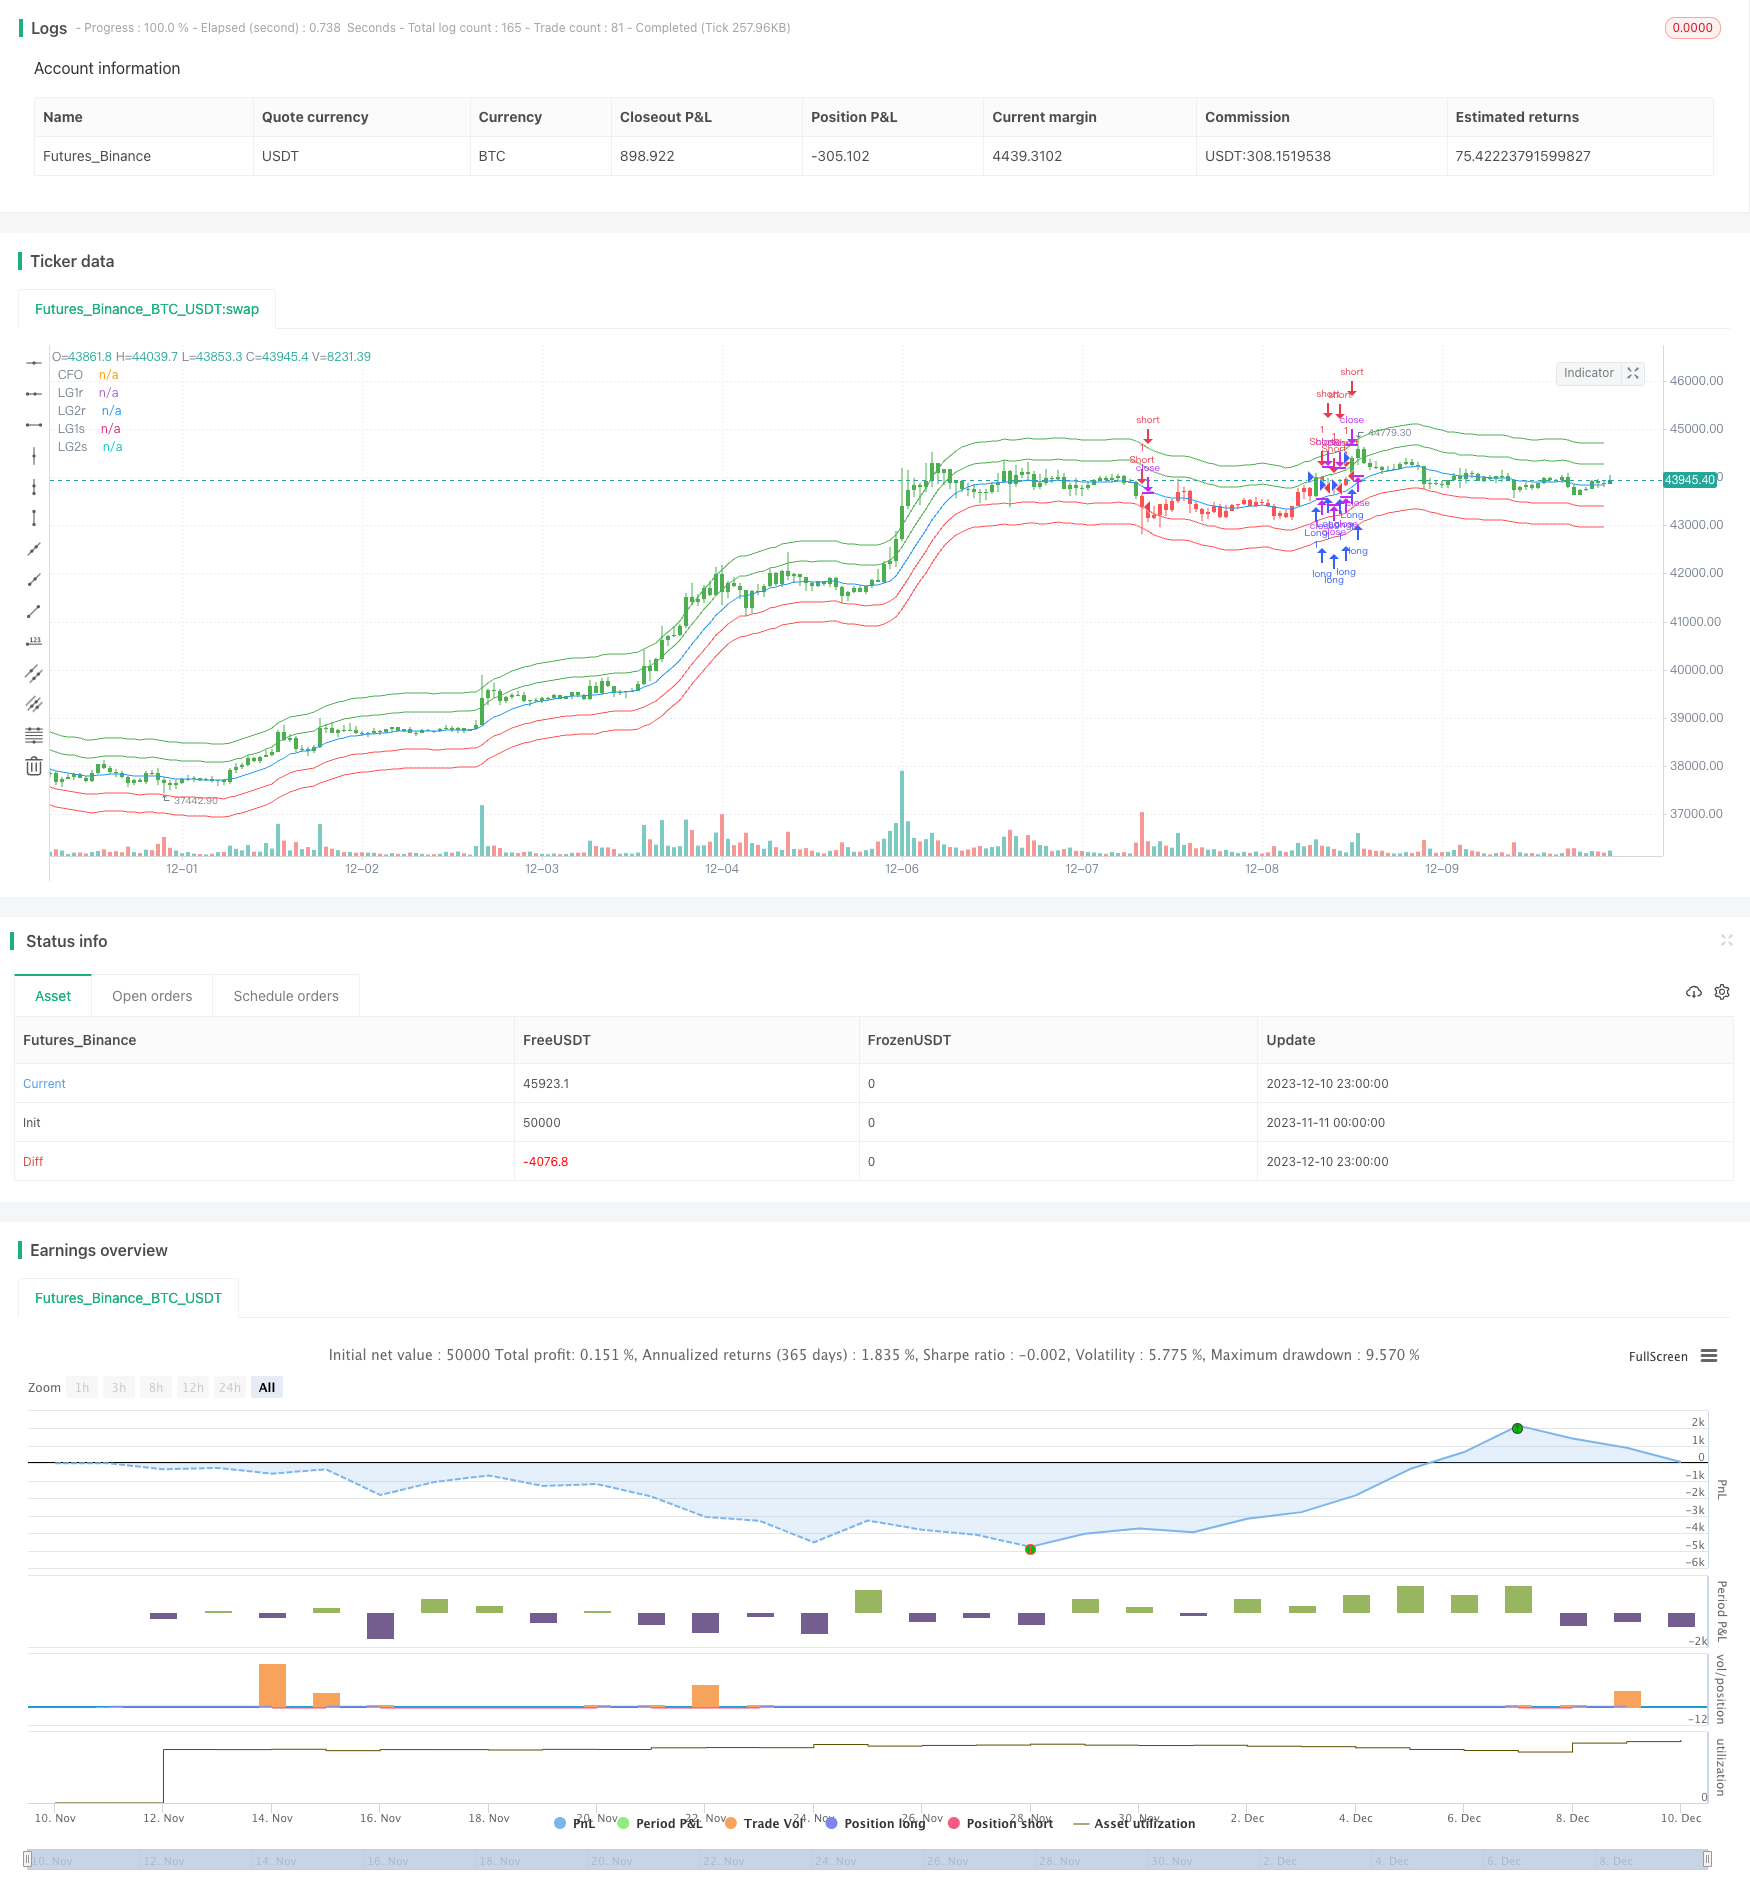
Overview
The Center of Gravity backtesting trading strategy is a trading strategy based on moving averages. It calculates the "center" of the price, i.e. the position of the center of gravity, and constructs price channels as corridors for asset quotes. The strategy can change long to short in the Input Settings.
Strategy Principle
The strategy calculates the center of gravity position through linear regression function. Specifically, it calculates the linear regression value of the closing price over the Length period, which is the "center" of the price. Price channels are then constructed by moving up and down Percent% on this basis. The upper and lower boundaries of the price channel serve as long and short signals respectively. When the price breaks through the upper rail, go long; when the price breaks below the lower rail, go short. The SignalLine parameter is used to select whether to use the first channel or the second channel's upper and lower rails as trading signals. The reverse parameter is used to reverse long and short.
Advantage Analysis
This is a very simple breakout strategy with the following main advantages:
- The idea is clear and easy to understand and implement.
- Good backtest results with certain practical feasibility.
- Flexible parameter settings to adapt to different market environments.
- Configurable reversal trading, suitable for two-way operation.
Risk Analysis
The strategy also has some risks:
- There may be overfitting risks in the backtest process. Parameters need to be re-optimized for live trading.
- Failed breakouts can lead to large losses.
- The trading frequency may be relatively high, so the capital usage ratio needs to be controlled.
Risks can be controlled by adjusting parameters like Bands, Length, etc. Stop loss can also be set to limit maximum loss.
Optimization Directions
The strategy can be further optimized in the following ways:
- Combine with trend indicators to filter signals and avoid trading against the trend.
- Add stop loss mechanism.
- Optimize parameter settings to increase profit ratio.
- Add position control to reduce risk.
Summary
The Center of Gravity backtesting trading strategy is a simple breakout strategy. It has clear logic, good practicability, and flexible parameter settings. At the same time, there are also certain risks that need to be properly optimized and controlled. The strategy is suitable as a basic strategy for live trading and optimization, and is also very suitable for beginners to learn.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 20 | Length |
| v_input_2 | 5 | m |
| v_input_3 | true | Percent |
| v_input_4 | true | Trade from line (1 or 2) |
| v_input_5 | false | Trade reverse |
Source Pine Script
/*backtest
start: 2023-11-11 00:00:00
end: 2023-12-11 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=2
////////////////////////////////////////////////////////////
//  Copyright by HPotter v1.0 15/03/2018
// The indicator is based on moving averages. On the basis of these, the
// "center" of the price is calculated, and price channels are also constructed,
// which act as corridors for the asset quotations.
//
// You can change long to short in the Input Settings
// WARNING:
//  - For purpose educate only
//  - This script to change bars colors.
////////////////////////////////////////////////////////////
strategy(title="Center Of Gravity Backtest", shorttitle="CFO", overlay = true)
Length = input(20, minval=1)
m = input(5, minval=0)
Percent = input(1, minval=0)
SignalLine = input(1, minval=1, maxval = 2, title = "Trade from line (1 or 2)")
reverse = input(false, title="Trade reverse")
xLG = linreg(close, Length, m)
xLG1r = xLG + ((close * Percent) / 100)
xLG1s = xLG - ((close * Percent) / 100)
xLG2r = xLG + ((close * Percent) / 100) * 2
xLG2s = xLG - ((close * Percent) / 100) * 2
xSignalR = iff(SignalLine == 1, xLG1r, xLG2r)
xSignalS = iff(SignalLine == 1, xLG1s, xLG2s)
pos = iff(close > xSignalR, 1,
       iff(close < xSignalS, -1, nz(pos[1], 0)))
possig = iff(reverse and pos == 1, -1,
          iff(reverse and pos == -1, 1, pos))
if (possig == 1)
    strategy.entry("Long", strategy.long)
if (possig == -1)
    strategy.entry("Short", strategy.short)
barcolor(possig == -1 ? red: possig == 1 ? green : blue )
plot(xLG, color=blue, title="CFO")
plot(xLG1r, color=green, title="LG1r")
plot(xLG2r, color=green, title="LG2r")
plot(xLG1s, color=red, title="LG1s")
plot(xLG2s, color=red, title="LG2s")
Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-12. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Center-of-Gravity-Backtesting-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- 5 Day Moving Average Channel Breakout Strategy Combined With Mileage ConceptPine Script · Breakout · 1d
- ATR Trailing Stops StrategyPine Script · Breakout · 1h
- ATR Trend Breakout StrategyPine Script · Breakout · 1d
- Adaptive Bollinger Breakout with Moving Average Quantitative Strategy SystemPine Script · Breakout · 1h
- Adaptive Channel Breakout StrategyPine Script · Breakout · 1d
- Adaptive Multi Period Trading Strategy Based on Wave Trend Momentum BreakoutPine Script · Breakout · 2h