Strategy vault / Mean reversion
Compound Quantitative Trading Strategy Based on MACD
This is a compound quantitative trading strategy based on the MACD indicator. It combines multiple indicators such as MACD and KDJ to generate trading signals through the combination of indicators.
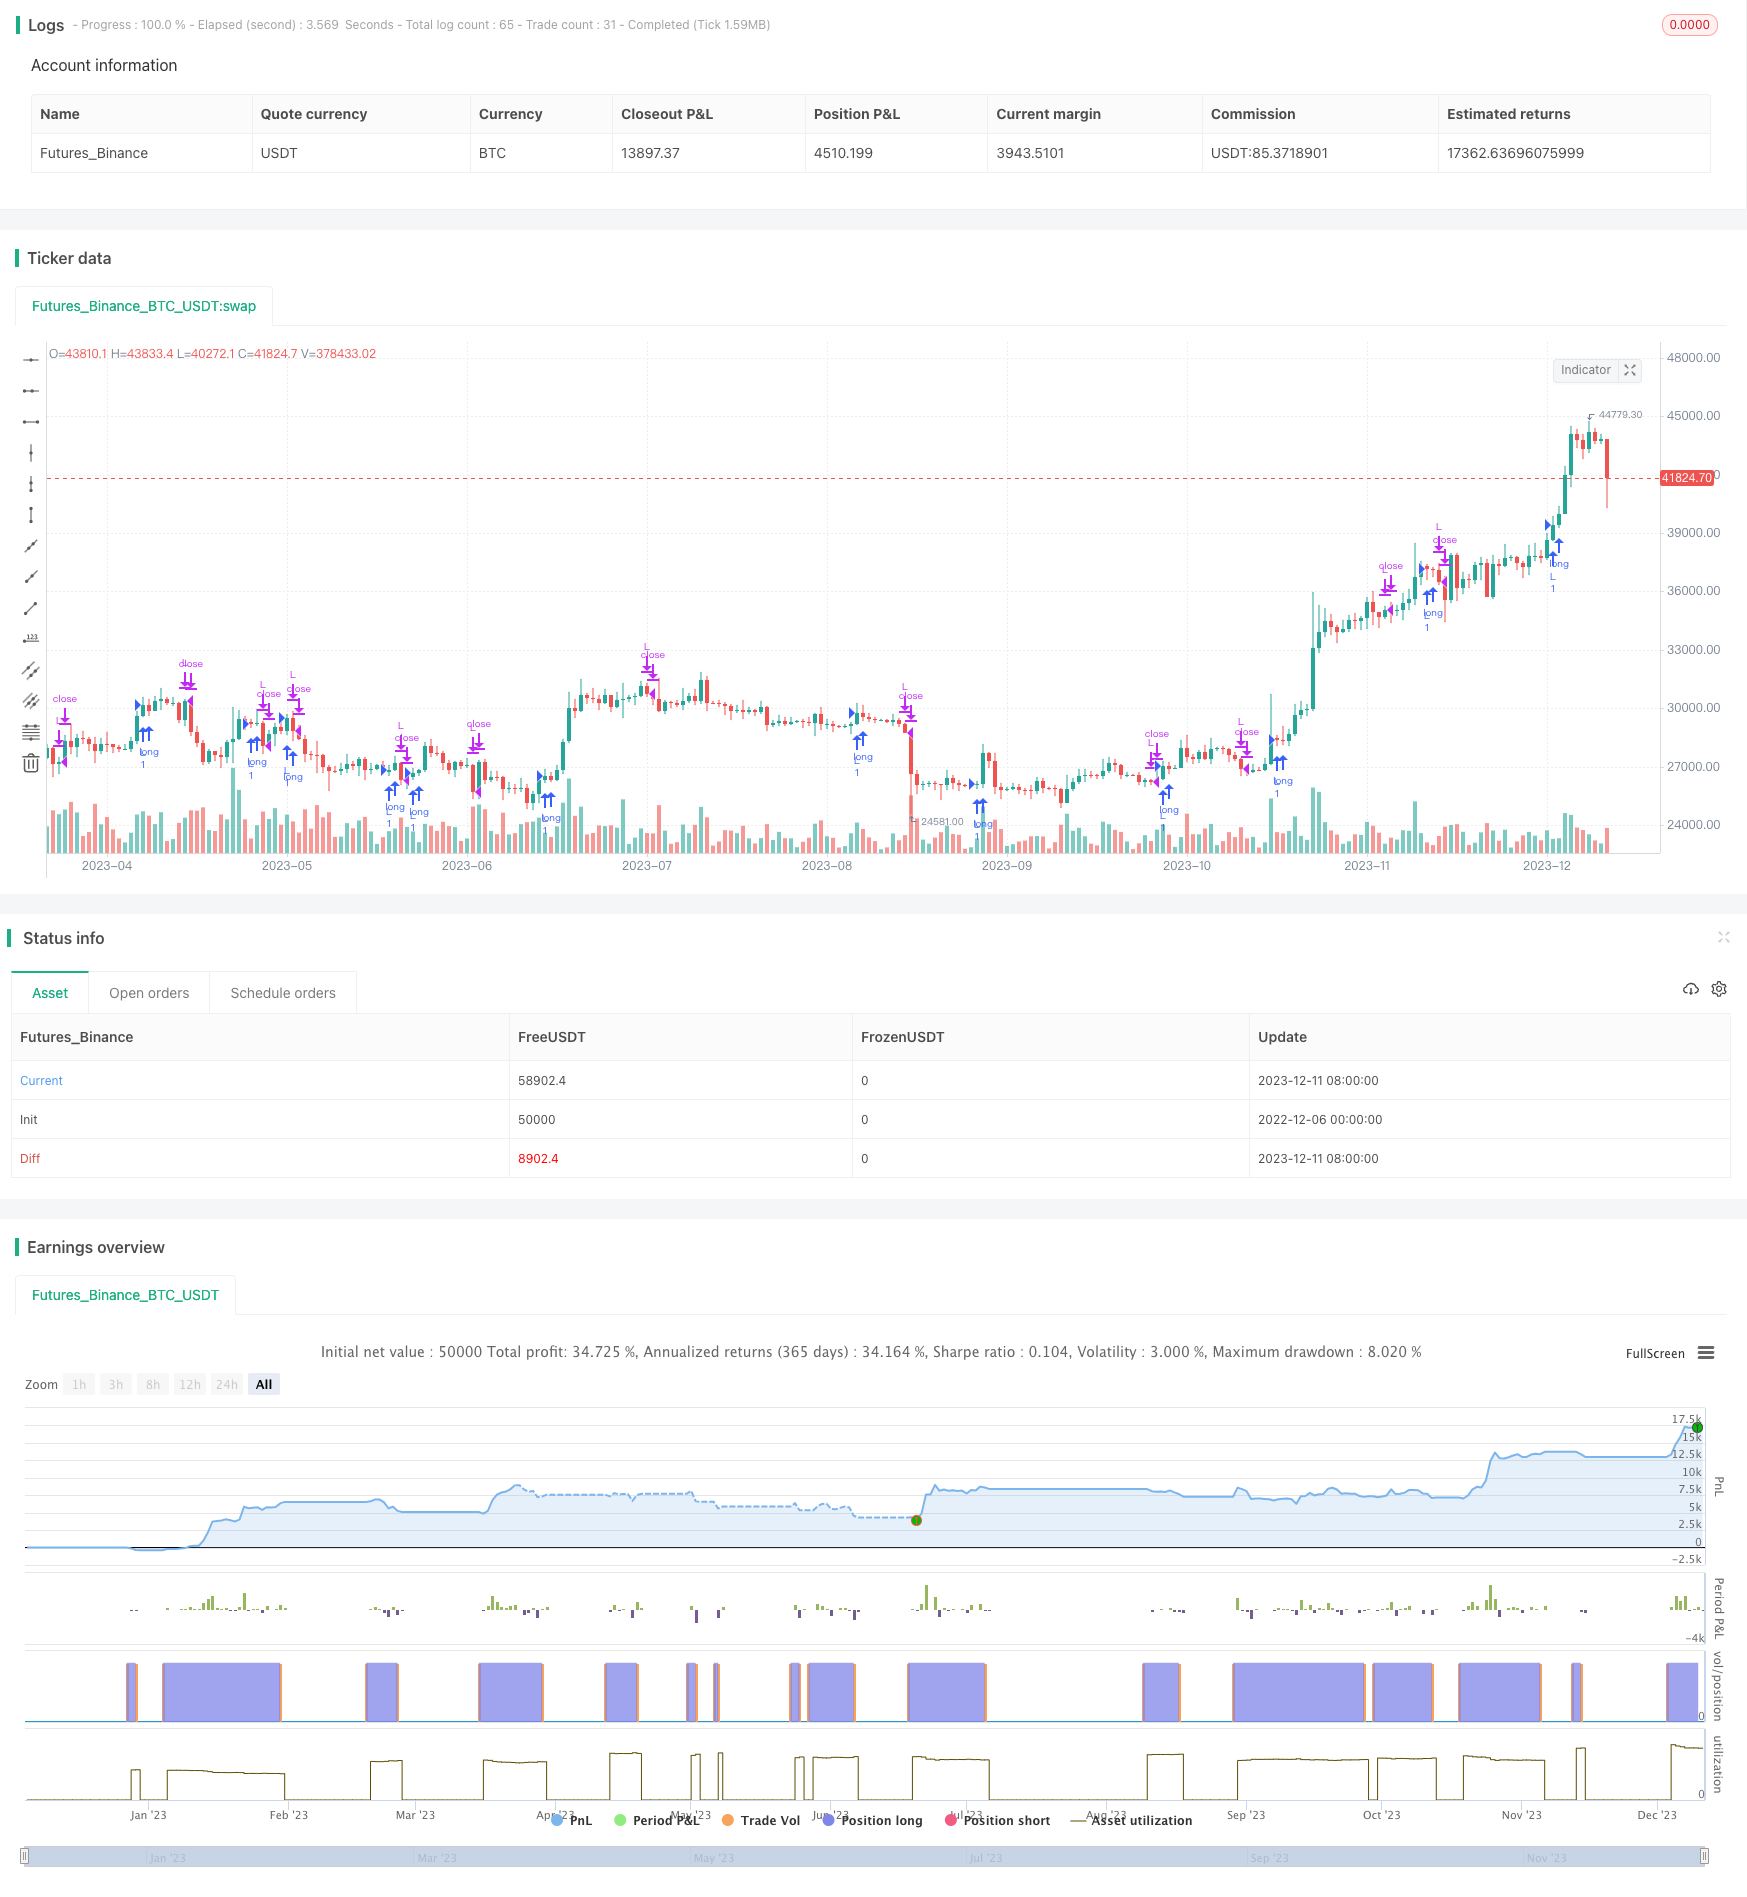
Overview
This is a compound quantitative trading strategy based on the MACD indicator. It combines multiple indicators such as MACD and KDJ to generate trading signals through the combination of indicators.
Strategy Principle
The core indicator of this strategy is MACD. MACD stands for Moving Average Convergence Divergence, which is a trend-following indicator. It consists of a fast moving average (EMA) and a slow moving average (EMA). The default parameters are 12 for the fast line and 26 for the slow line. The strategy calculates the difference between the two EMA lines, called the DIF. Then a 9-day EMA is calculated on the DIF to get the DEA indicator. When the DIF crosses above the DEA, a buy signal is generated. When crossing below, a sell signal is generated.
The strategy also incorporates the KDJ indicator. The KDJ indicator includes the K value, D value, and J value. Among them, the K value refers to the random value, the D value is the moving average of the K value, and the J value refers to the deterministic value. The KDJ indicator reflects the overbought and oversold levels in the market. When the J value is greater than 100, it represents overbought conditions. When less than 10, it represents oversold conditions. The strategy combines the KDJ indicator to avoid generating wrong signals at market turning points.
Advantages of the Strategy
The strategy combines multiple indicators such as MACD and KDJ, which can effectively filter out market noise and identify trend directions. The MACD indicator can capture short-term price changes in a timely manner, while the KDJ indicator can confirm medium and long term trends. The combination of the two can balance the pursuit of agility and stability.
In addition, the strategy incorporates a time range selector, which provides greater flexibility in evaluating strategy performance.
Risks and Solutions
When the market fluctuates for an extended period, MACD will have multiple false signals. At this point, we can properly adjust the parameters of the EMA lines to filter out some noise.
Improper KDJ parameter settings will also affect results. We can test multiple parameter groups and select a more stable parameter combination.
Inappropriate selection of backtest timeframe will overestimate or underestimate the profitability of the strategy. Representative timeframes should be chosen for testing.
Optimization Directions
The strategy can be optimized in the following aspects:
Add a stop loss mechanism. When the price triggers the stop loss line, it will force a position exit for stop loss purposes.
Incorporate more indicator filters, combining indicators such as RSI and Bollinger Bands to improve signal accuracy.
Optimize indicator parameters. Change the combination of EMA and KDJ parameters to find the optimal settings.
Use machine learning techniques to automatically optimize. Use neural networks for parameter training and optimization.
Conclusion
This is a typical quantitative strategy that mainly follows the trend, supplemented by overbought and oversold control. It combines the advantages of multiple indicators and effectively balances stability and sensitivity. Through continuous optimization and adjustment, the applicability of the strategy can be further expanded to obtain long-term steady profits.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 12 | fastlength |
| v_input_2 | 26 | slowlength |
| v_input_3 | 9 | signallength |
| v_input_4 | true | From Month |
| v_input_5 | true | From Day |
| v_input_6 | 2018 | From Year |
| v_input_7 | 12 | Thru Month |
| v_input_8 | 31 | Thru Day |
| v_input_9 | 2020 | Thru Year |
| v_input_10 | true | Show Date Range |
Source Pine Script
/*backtest
start: 2022-12-06 00:00:00
end: 2023-12-12 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4
strategy(title="New Renaissance", shorttitle="New Renaissance", overlay=true,initial_capital=10000)

source = close

fastlength=input(12, minval=1)
slowlength=input(26,minval=1)
signallength=input(9,minval=1)

// === Defining the MACD oscillator
fastMA=ema(source,fastlength)
slowMA=ema(source,slowlength)
MACD=fastMA-slowMA
signal=sma(MACD,signallength)
delta=MACD-signal

// === Buy and Sell Signals ===
buy=crossover(MACD, signal)
sell=crossunder(MACD, signal)

// === INPUT BACKTEST RANGE ===
fromMonth = input(defval = 1,    title = "From Month",      type = input.integer, minval = 1, maxval = 12)
fromDay   = input(defval = 1,    title = "From Day",        type = input.integer, minval = 1, maxval = 31)
fromYear  = input(defval = 2018, title = "From Year",       type = input.integer, minval = 1970)
thruMonth = input(defval = 12,    title = "Thru Month",      type = input.integer, minval = 1, maxval = 12)
thruDay   = input(defval = 31,    title = "Thru Day",        type = input.integer, minval = 1, maxval = 31)
thruYear  = input(defval = 2020, title = "Thru Year",       type = input.integer, minval = 1970)

// === INPUT SHOW PLOT ===
showDate  = input(defval = true, title = "Show Date Range", type = input.bool)

// === FUNCTION EXAMPLE ===
start     = timestamp(fromYear, fromMonth, fromDay, 00, 00)        // backtest start window
finish    = timestamp(thruYear, thruMonth, thruDay, 23, 59)        // backtest finish window
window()  => true       // create function "within window of time"

// === EXECUTION ===
strategy.entry("L", strategy.long, when = window() and buy)    // enter long when "within window of time" AND crossover
strategy.close("L", when = window() and sell)                   // exit long when "within window of time" AND crossunder
Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-13. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Compound-Quantitative-Trading-Strategy-Based-on-MACD.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Advanced 15 Minute Chart Trading Signal StrategyPine Script · Mean reversion · 3h
- BONK Multi Factor Trading StrategyPine Script · Mean reversion · 1d
- Customizable Non Repainting HTF MACD MFI Scalable Bot StrategyPine Script · Mean reversion · 1d
- Dynamic Adaptive Multi Timeframe Trend Following and Range Reversal Hybrid StrategyPine Script · Mean reversion · 2d
- MACD Cross Period Trading StrategyPine Script · Mean reversion · 1d
- MACD Double Optimization Trading StrategyPine Script · Mean reversion · 1d