Strategy vault / Mean reversion
Comprehensive Quantitative Trading Strategy Based on Multiple Indicators
The strategy is named "Comprehensive Quantitative Trading Strategy Based on Multiple Indicators". It integrates several technical indicators including SuperTrend, QQE and Trend Indicator A-V2 to form a comprehensive…
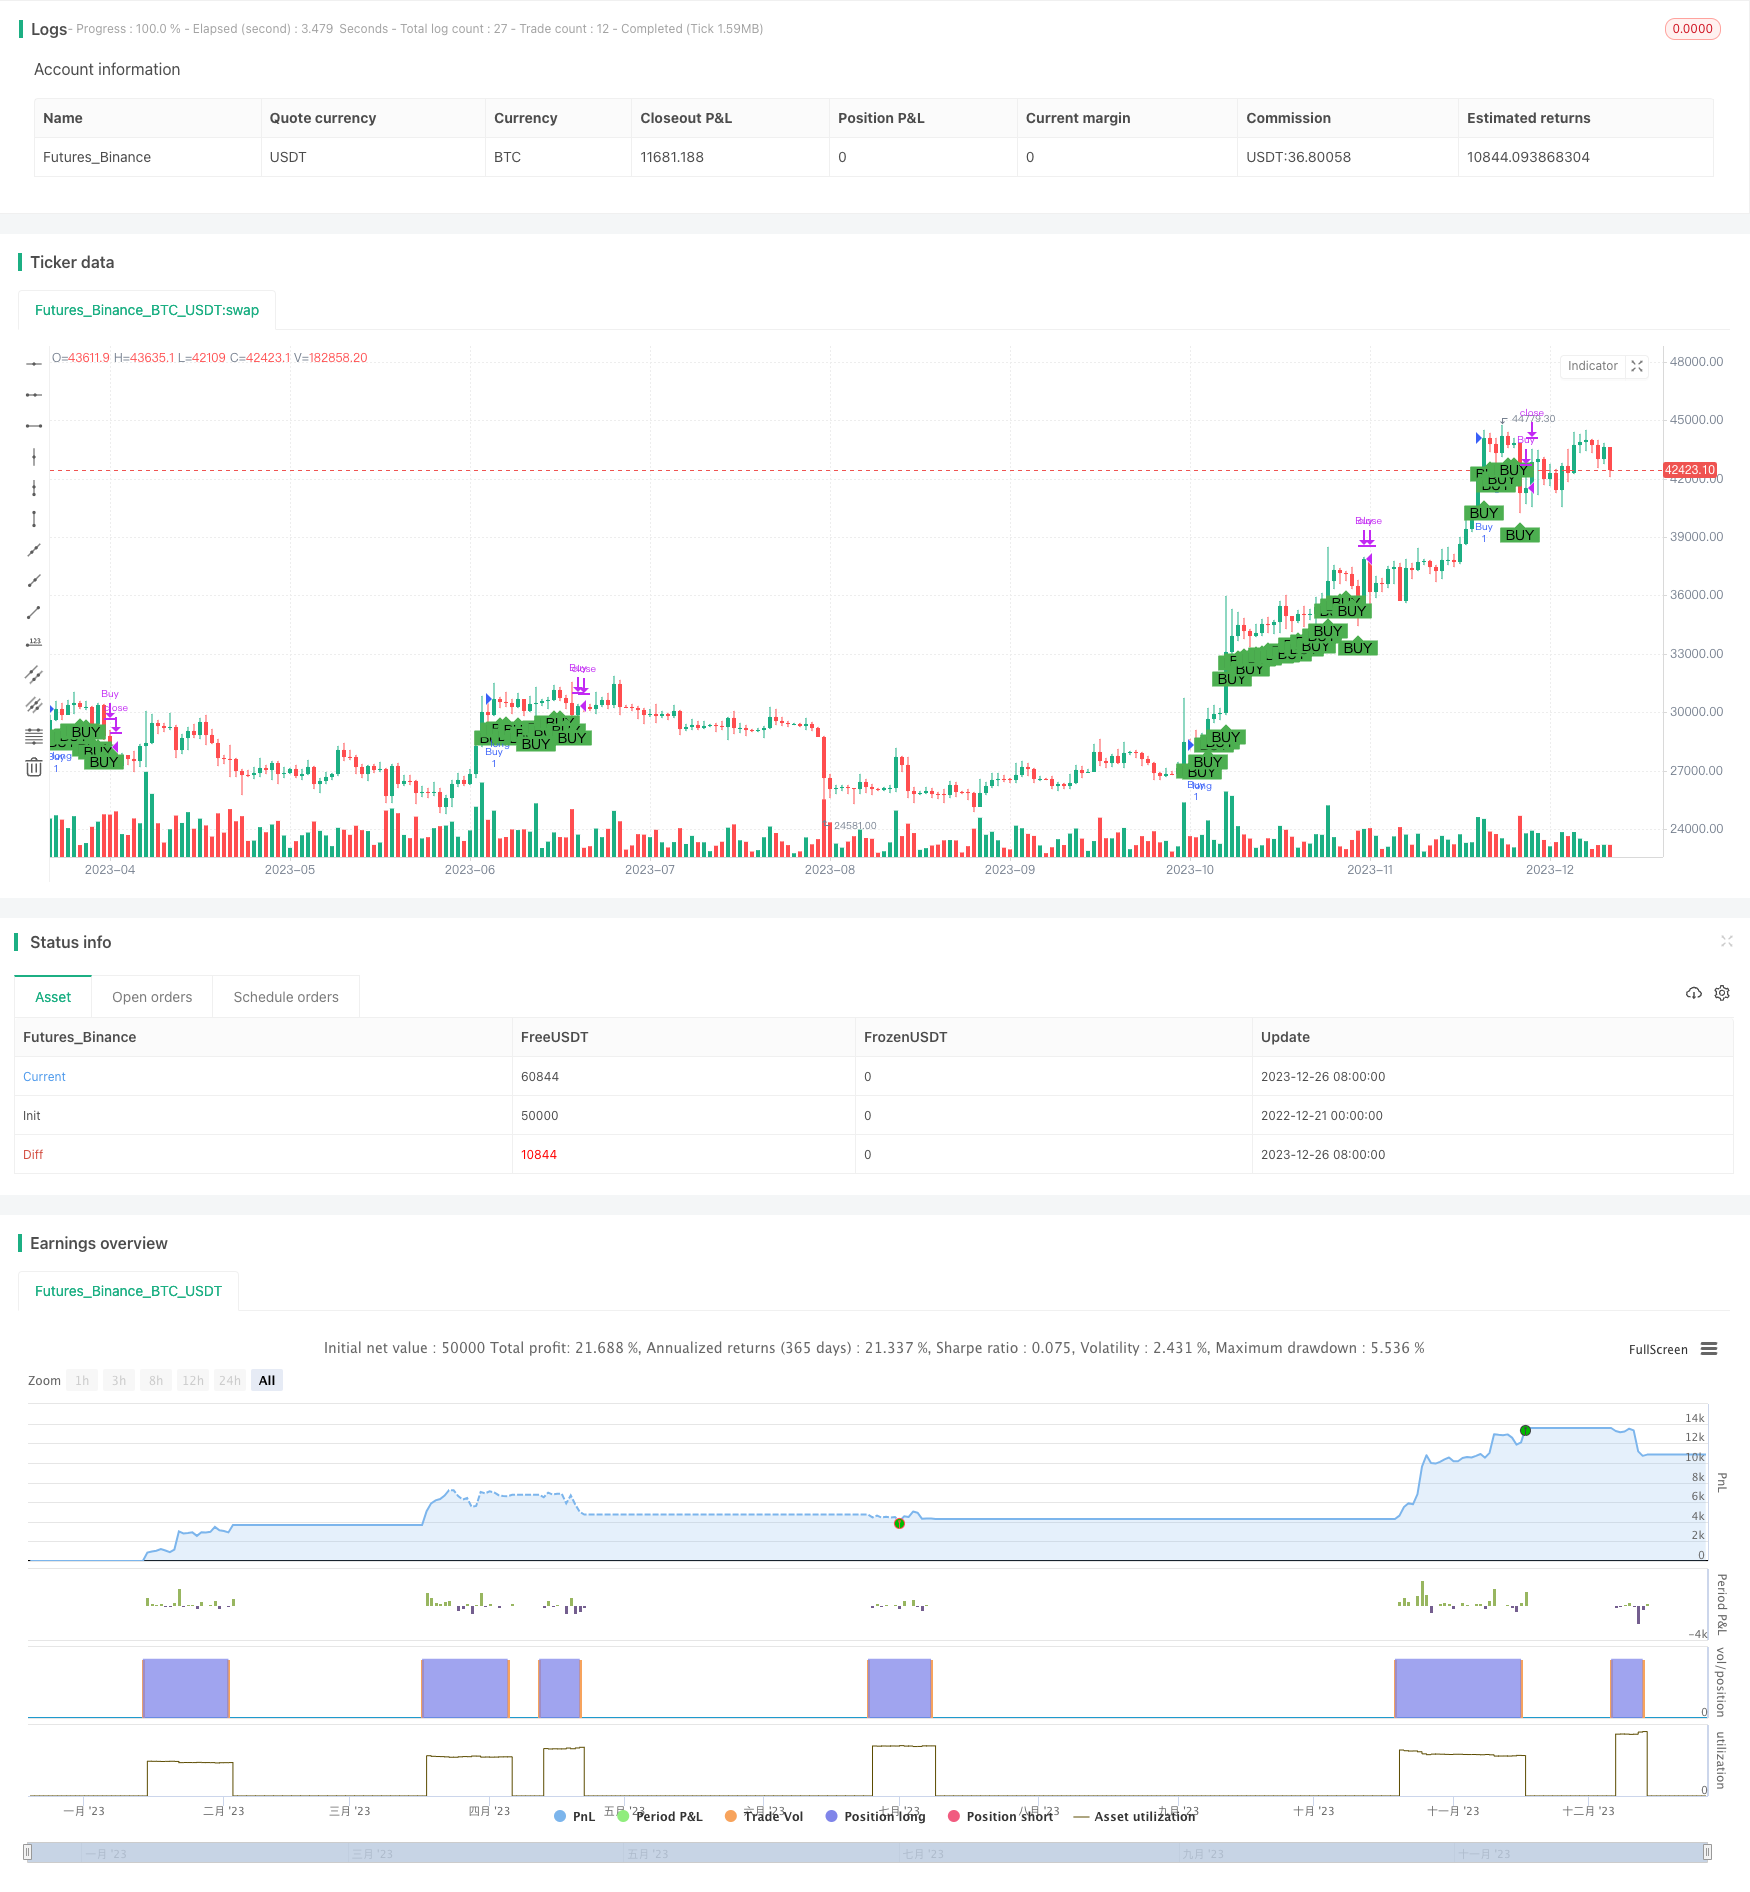
Overview
The strategy is named "Comprehensive Quantitative Trading Strategy Based on Multiple Indicators". It integrates several technical indicators including SuperTrend, QQE and Trend Indicator A-V2 to form a comprehensive trading system that analyzes the market from multiple dimensions.
The core idea is to combine different indicators to improve the accuracy of judgment while capturing the major trends in the market, so as to provide traders with steady and efficient trading signals. This strategy takes into account trend, overbought/oversold levels, as well as intermediate and long-term trends, forming a multi-layer verification logic for trading decisions.
Strategy Logic
The core trading logic of this strategy is based on the combined judgments of the following three indicators:
SuperTrend: To determine if the price is in an uptrend or a downtrend. It generates buy and sell signals when the close price breaks through the upper or lower band.
QQE: An improved version of RSI that incorporates mean reversion characteristics. It is used to judge if the market is overbought or oversold. The threshold is dynamically adjusted based on RSI's standard deviation band.
Trend Indicator A-V2: Compare EMA of price and EMA of open price to determine trend direction. It verifies the intermediate and long-term trend.
The above three indicators have different focuses. SuperTrend targets at trends and reversal points. QQE focuses on overbought/oversold levels. A-V2 helps determine the intermediate and long-term trend. This strategy integrates them to form a complete trading decision system.
The specific trading logic is as follows:
A buy signal is generated when SuperTrend shows an uptrend, QQE shows the RSI is below the oversold level, and the A-V2 EMAs are rising.
A sell signal is generated when SuperTrend shows a downtrend, QQE shows the RSI is above the overbought level, and the A-V2 EMAs are falling.
The comprehensive judgment of multiple indicators ensures high accuracy in signals while maximizing opportunities in the market to achieve steady and efficient trading.
Advantage Analysis
The major advantages of this strategy are:
More accurate judgment due to indicator fusion. The integration of multiple indicators enables mutual verification, thus greatly improving accuracy.
More comprehensive coverage for dual-directional trading. Allowing long and short positions can gain decent profits from both upside and downside market swings.
Better risk control. Combination of indicators prevents individual indicator false signals. Indicators like QQE also control risks inherently.
Easy to use, flexible parameter tuning. The input parameters are simple for users to adjust based on their own preferences to suit different market conditions.
Wide applicability across major markets. It can be applied to markets like stocks, forex, cryptocurrencies and suits technical traders in particular.
Risk Analysis
The major risks of this strategy include:
Risk of bias in indicator judgments. Rare price anomalies may cause biases in indicator signals and hence risks.
Risk of trend reversal. This strategy focuses on trend-following, so major fundamental-driven reversals can cause huge losses.
Risk from improper parameter tuning. Inadequate user settings on parameters can skew indicator signals.
The main risk management solutions are: 1) Verify signals across indicators to prevent reliance on single indicator; 2) Control position sizing for managed loss per trade; 3) Adjust parameters per different markets.
Optimization Directions
The strategy can be optimized in the following aspects:
Add stop loss for profit taking and drawdown reduction. Trailing stop loss or stop loss with profit can be introduced.
Integrate more indicators for improved system stability. Indicators like MACD, DMI, OBV can be added for signal confirmation.
Introduce volatility-based position sizing. Dynamically adjust position sizes according to changing market volatility.
Optimize parameter tuning. Longer backtests can be conducted to find the optimal parameter sets for this strategy.
Use different parameter sets for different markets. Parameters can be separately optimized for the best results in different markets (stocks, forex, crypto etc).
Conclusion
This strategy integrates SuperTrend, QQE and A-V2 indicators into a comprehensive quantitative trading system with robust signal judgments. By combining trend, overbought/oversold levels and intermediate-long term trend verifications, it can effectively identify opportunities while strictly controlling risks. The strategy has significant advantages and is worth evaluating and optimizing in live trading by technical traders. It also provides valuable references for other strategy development.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | true | One-sided |
| v_input_2 | 9 | ST ATR Period |
| v_input_3 | 3.9 | ST ATR Multiplier |
| v_input_4_hl2 | 0 | ST Source: hl2 | high | low | open | close | hlc3 | hlcc4 | ohlc4 |
| v_input_5 | 6 | QQE RSI Length |
| v_input_6 | 5 | QQE RSI Smoothing |
| v_input_7 | 3 | QQE Fast Factor |
| v_input_8 | 3 | QQE Thresh-hold |
| v_input_9_close | 0 | QQE RSI Source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_10 | 52 | TIA-V2 EMA Period |
Source Pine Script
/*backtest
start: 2022-12-21 00:00:00
end: 2023-12-27 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4
//author:Lu Zhenxing, graduated from Furong Chinese High School, earned a master's degree from Yuda University of Science and Technology
//Reference Materials : QQE MOD By:Mihkel00 ,SuperTrend By:KivancOzbilgic , TrendIndicator A-V2 By:Dziwne

strategy("Comprehensive trading strategy", shorttitle="Comprehensive Strategy", overlay=true)

// Add one-sided or long-short parameters
OnlyLong = input(true, title="One-sided")

// SuperTrend Parameters
PeriodsST = input(9, title="ST ATR Period")
MultiplierST = input(3.9, title="ST ATR Multiplier")
srcST = input(hl2, title="ST Source")

atrST = atr(PeriodsST)
upST = srcST - (MultiplierST * atrST)
upST := close[2] > upST[1] ? max(upST, upST[1]) : upST
dnST = srcST + (MultiplierST * atrST)
dnST := close[2] < dnST[1] ? min(dnST, dnST[1]) : dnST
trendST = 1
trendST := nz(trendST[1], trendST)
trendST := trendST == -1 and close[2] > dnST[1] ? 1 : trendST == 1 and close[2] < upST[1] ? -1 : trendST

// QQE Parameters
RSI_PeriodQQE = input(6, title='QQE RSI Length')
SFQQE = input(5, title='QQE RSI Smoothing')
QQE = input(3, title='QQE Fast Factor')
ThreshHoldQQE = input(3, title="QQE Thresh-hold")
srcQQE = input(close, title="QQE RSI Source")

Wilders_PeriodQQE = RSI_PeriodQQE * 2 - 1

RsiQQE = rsi(srcQQE, RSI_PeriodQQE)
RsiMaQQE = ema(RsiQQE, SFQQE)
AtrRsiQQE = abs(RsiMaQQE[1] - RsiMaQQE)
MaAtrRsiQQE = ema(AtrRsiQQE, Wilders_PeriodQQE)
darQQE = ema(MaAtrRsiQQE, Wilders_PeriodQQE) * QQE

basisQQE = sma(RsiMaQQE - 50, 50)
devQQE = 0.35 * stdev(RsiMaQQE - 50, 50)
upperQQE = basisQQE + devQQE
lowerQQE = basisQQE - devQQE

qqeCondition = RsiMaQQE[1] - 50 > upperQQE[1] ? true : RsiMaQQE[1] - 50 < lowerQQE[1] ? false : na

// Trend Indicator A-V2 Parameters
ma_periodA_V2 = input(52, title="TIA-V2 EMA Period")
oA_V2 = ema(open, ma_periodA_V2)
cA_V2 = ema(close, ma_periodA_V2)
trendIndicatorAV2Condition = cA_V2[1] >= oA_V2[1] ? true : false

// Comprehensive trading logic
longCondition = trendST == 1 and qqeCondition and trendIndicatorAV2Condition
shortCondition = trendST == -1 and not qqeCondition and not trendIndicatorAV2Condition

// Open/close logic for long positions
if (OnlyLong)
    if (longCondition)
        strategy.entry("Buy", strategy.long)
    else
        strategy.close("Buy")

// The logic of doing both long and short positions
if (not OnlyLong)
    if (longCondition)
        strategy.entry("Buy", strategy.long)
    else if (shortCondition)
        strategy.entry("Sell",strategy.short)

    // Add long and short closing logic
    if (not longCondition)
        strategy.close("Buy")
    if (not shortCondition)
        strategy.close("Sell")

// Visual Signal
plotshape(series=longCondition, title="Buy Signal", location=location.belowbar, color=color.green, style=shape.labelup, text="BUY")
plotshape(series=shortCondition and not OnlyLong, title="Sell Signal", location=location.abovebar, color=color.red, style=shape.labeldown, text="SELL")
Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-28. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Comprehensive-Quantitative-Trading-Strategy-Based-on-Multiple-Indicators.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Multi Indicator Weighted Smart Trading StrategyPine Script · Mean reversion · 2d
- Multi Indicator Trend Reversal Volatility Conditional Selective Options Selling StrategyPine Script · Mean reversion · 1h
- Advanced Momentum EMA Trend Following with RSI Overbought Oversold Trading StrategyPine Script · Mean reversion · 1d
- Customizable Non Repainting HTF MACD MFI Scalable Bot StrategyPine Script · Mean reversion · 1d
- Dynamic Adaptive Multi Timeframe Trend Following and Range Reversal Hybrid StrategyPine Script · Mean reversion · 2d
- MACD Cross Period Trading StrategyPine Script · Mean reversion · 1d