Consolidation Zones Live
This is the script that finds Consolidation Zones in Realtime. How it works? - The script finds highest/lowest bars by using "Loopback Period" - Then it calculates direction - By using the direction and…
This is the script that finds Consolidation Zones in Realtime.
How it works?
- The script finds highest/lowest bars by using "Loopback Period"
- Then it calculates direction
- By using the direction and highest/lowest bar info it calculates consolidation zones in realtime
- If the length of consolidation area is equal/greater than user-defined min length then this area is shown as consolidation zone
- Then Consolidation Zone extends automatically if there is no breakout
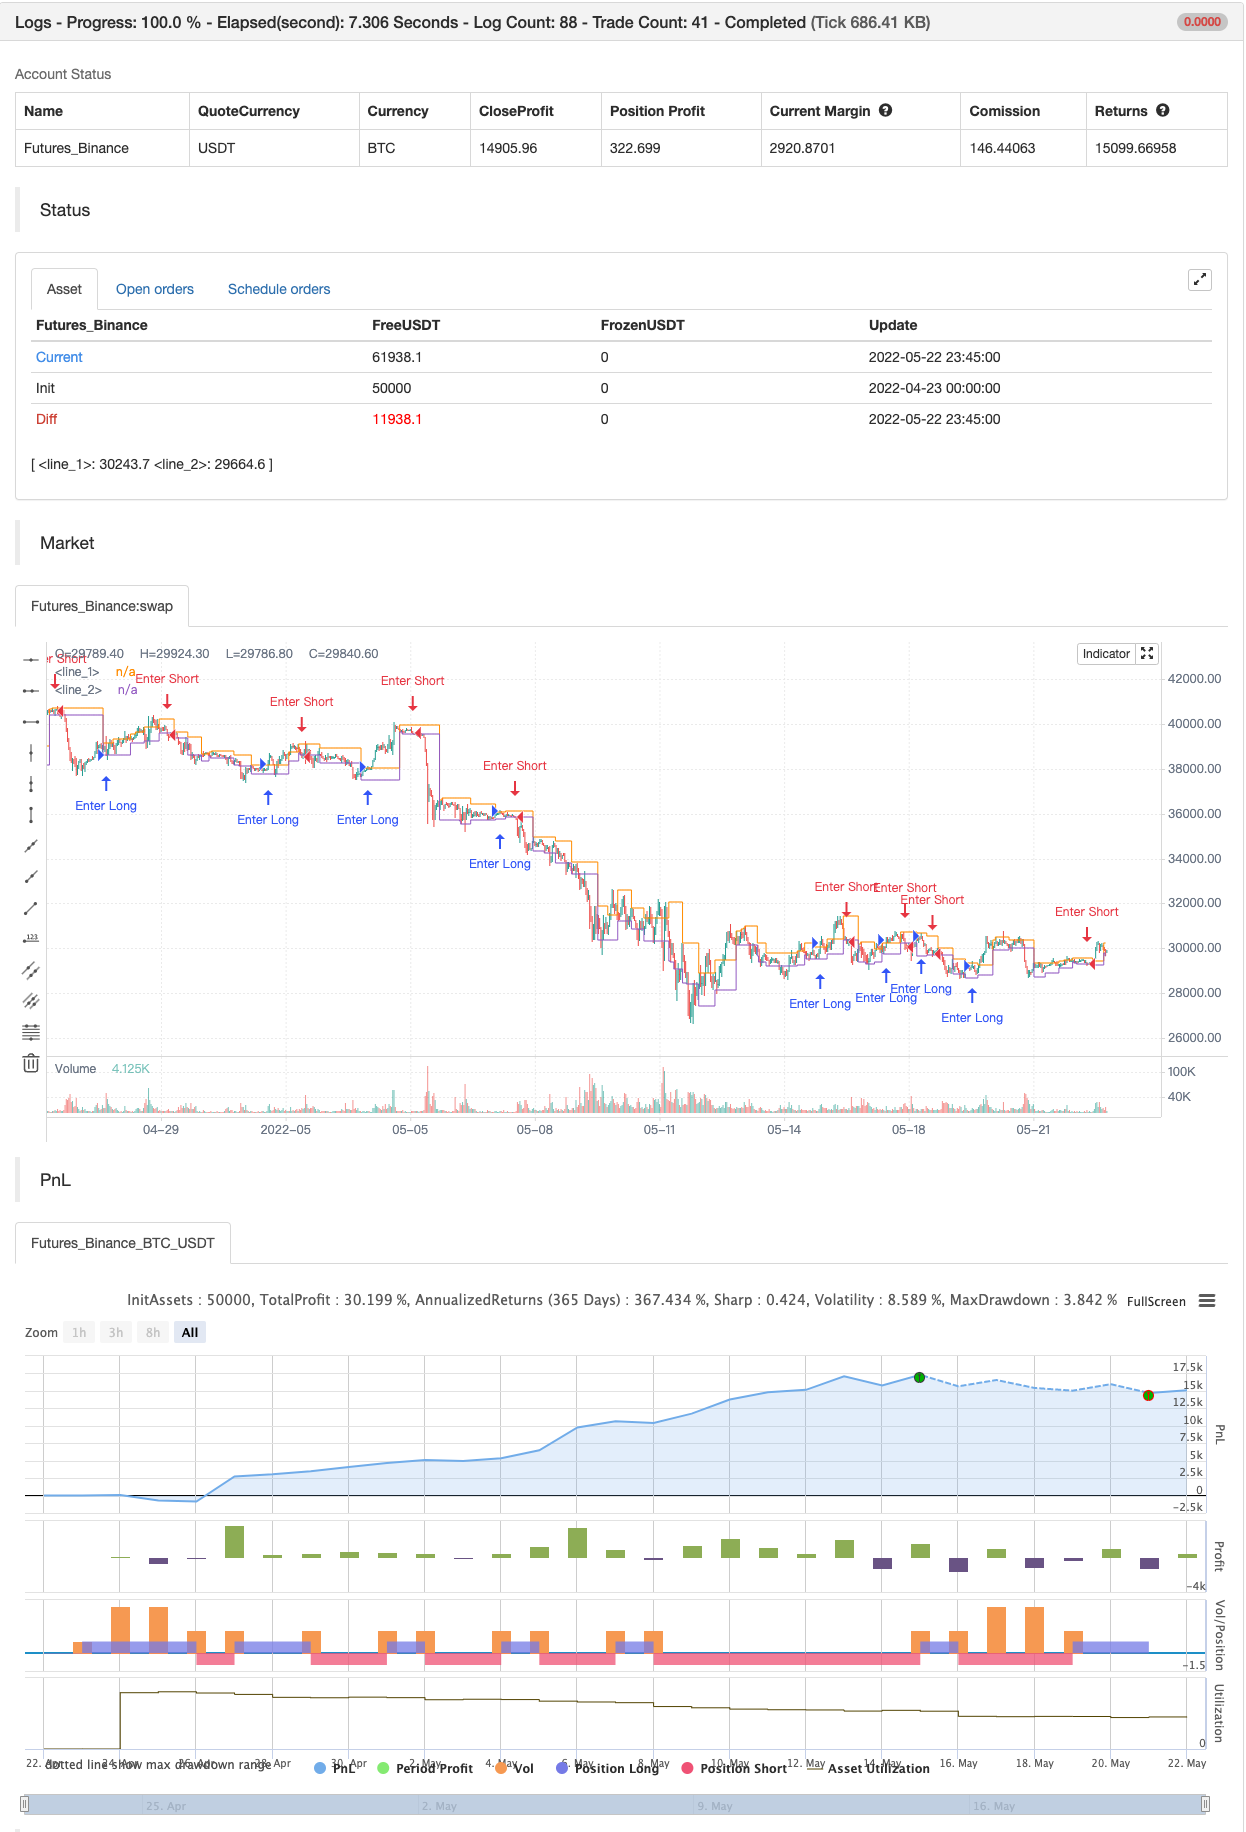
backtest
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 10 | Loopback Period |
| v_input_2 | 5 | Min Consolidation Length |
| v_input_3 | true | Paint Consolidation Area |
| v_input_4 | blue | Zone Color |
Source Pine Script
/*backtest
start: 2022-04-23 00:00:00
end: 2022-05-22 23:59:00
period: 45m
basePeriod: 5m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © LonesomeTheBlue

//@version=4
study("Consolidation Zones - Live", overlay = true, max_bars_back = 1100)
prd = input(defval = 10, title="Loopback Period", minval = 2, maxval = 50)
conslen = input(defval = 5, title="Min Consolidation Length", minval = 2, maxval = 20)
paintcons = input(defval = true, title = "Paint Consolidation Area ")
zonecol = input(defval = color.new(color.blue, 70), title = "Zone Color")

float hb_ = highestbars(prd) == 0 ? high : na
float lb_ = lowestbars(prd) == 0 ? low : na
var int dir = 0
float zz = na
float pp = na

dir := iff(hb_ and na(lb_), 1, iff(lb_ and na(hb_), -1, dir))
if hb_ and lb_
    if dir == 1
        zz := hb_
    else
        zz := lb_
else
    zz := iff(hb_, hb_, iff(lb_, lb_, na))

for x = 0 to 1000
    if na(close) or dir != dir[x]
        break
    if zz[x]
        if na(pp)
            pp := zz[x]
        else
            if dir[x] == 1 and zz[x] > pp
                pp := zz[x]
            if dir[x] == -1 and zz[x] < pp
                pp := zz[x]

var int conscnt = 0
var float condhigh = na
var float condlow = na
float H_ = highest(conslen)
float L_ = lowest(conslen)
var line upline = na
var line dnline = na
bool breakoutup = false
bool breakoutdown = false

if change(pp)
    if conscnt > conslen
        if pp > condhigh
            breakoutup := true
        if pp < condlow
            breakoutdown := true
    if conscnt > 0 and pp <= condhigh and pp >= condlow
        conscnt := conscnt + 1
    else
        conscnt := 0
else
    conscnt := conscnt + 1

if conscnt >= conslen
    if conscnt == conslen
        condhigh := H_
        condlow  := L_
    else
        // line.delete(upline)
        // line.delete(dnline)
        condhigh := max(condhigh, high)
        condlow := min(condlow, low)

    // upline := line.new(bar_index, condhigh, bar_index - conscnt, condhigh, color = color.red, style = line.style_dashed)
    // dnline := line.new(bar_index, condlow , bar_index - conscnt, condlow, color = color.lime, style = line.style_dashed)

fill(plot(condhigh, color = na, style = plot.style_stepline),
   plot(condlow, color = na, style = plot.style_stepline),
   color = paintcons and conscnt > conslen ? zonecol : color.new(color.white, 100))

alertcondition(breakoutup, title='Breakout Up', message='Breakout Up')
alertcondition(breakoutdown, title='Breakout Down', message='Breakout Down')

if breakoutup
    strategy.entry("Enter Long", strategy.long)
else if breakoutdown
strategy.entry("Enter Short", strategy.short)Published by ChaoZhang on the FMZ strategy square · last modified 2022-05-24. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Consolidation-Zones-Live.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- 5 Day Moving Average Channel Breakout Strategy Combined With Mileage ConceptPine Script · Breakout · 1d
- ATR Trailing Stops StrategyPine Script · Breakout · 1h
- ATR Trend Breakout StrategyPine Script · Breakout · 1d
- Adaptive Bollinger Breakout with Moving Average Quantitative Strategy SystemPine Script · Breakout · 1h
- Adaptive Channel Breakout StrategyPine Script · Breakout · 1d
- Adaptive Multi Period Trading Strategy Based on Wave Trend Momentum BreakoutPine Script · Breakout · 2h