Strategy vault / Trend following
Cross Limit Order Cross Period Trading Strategy
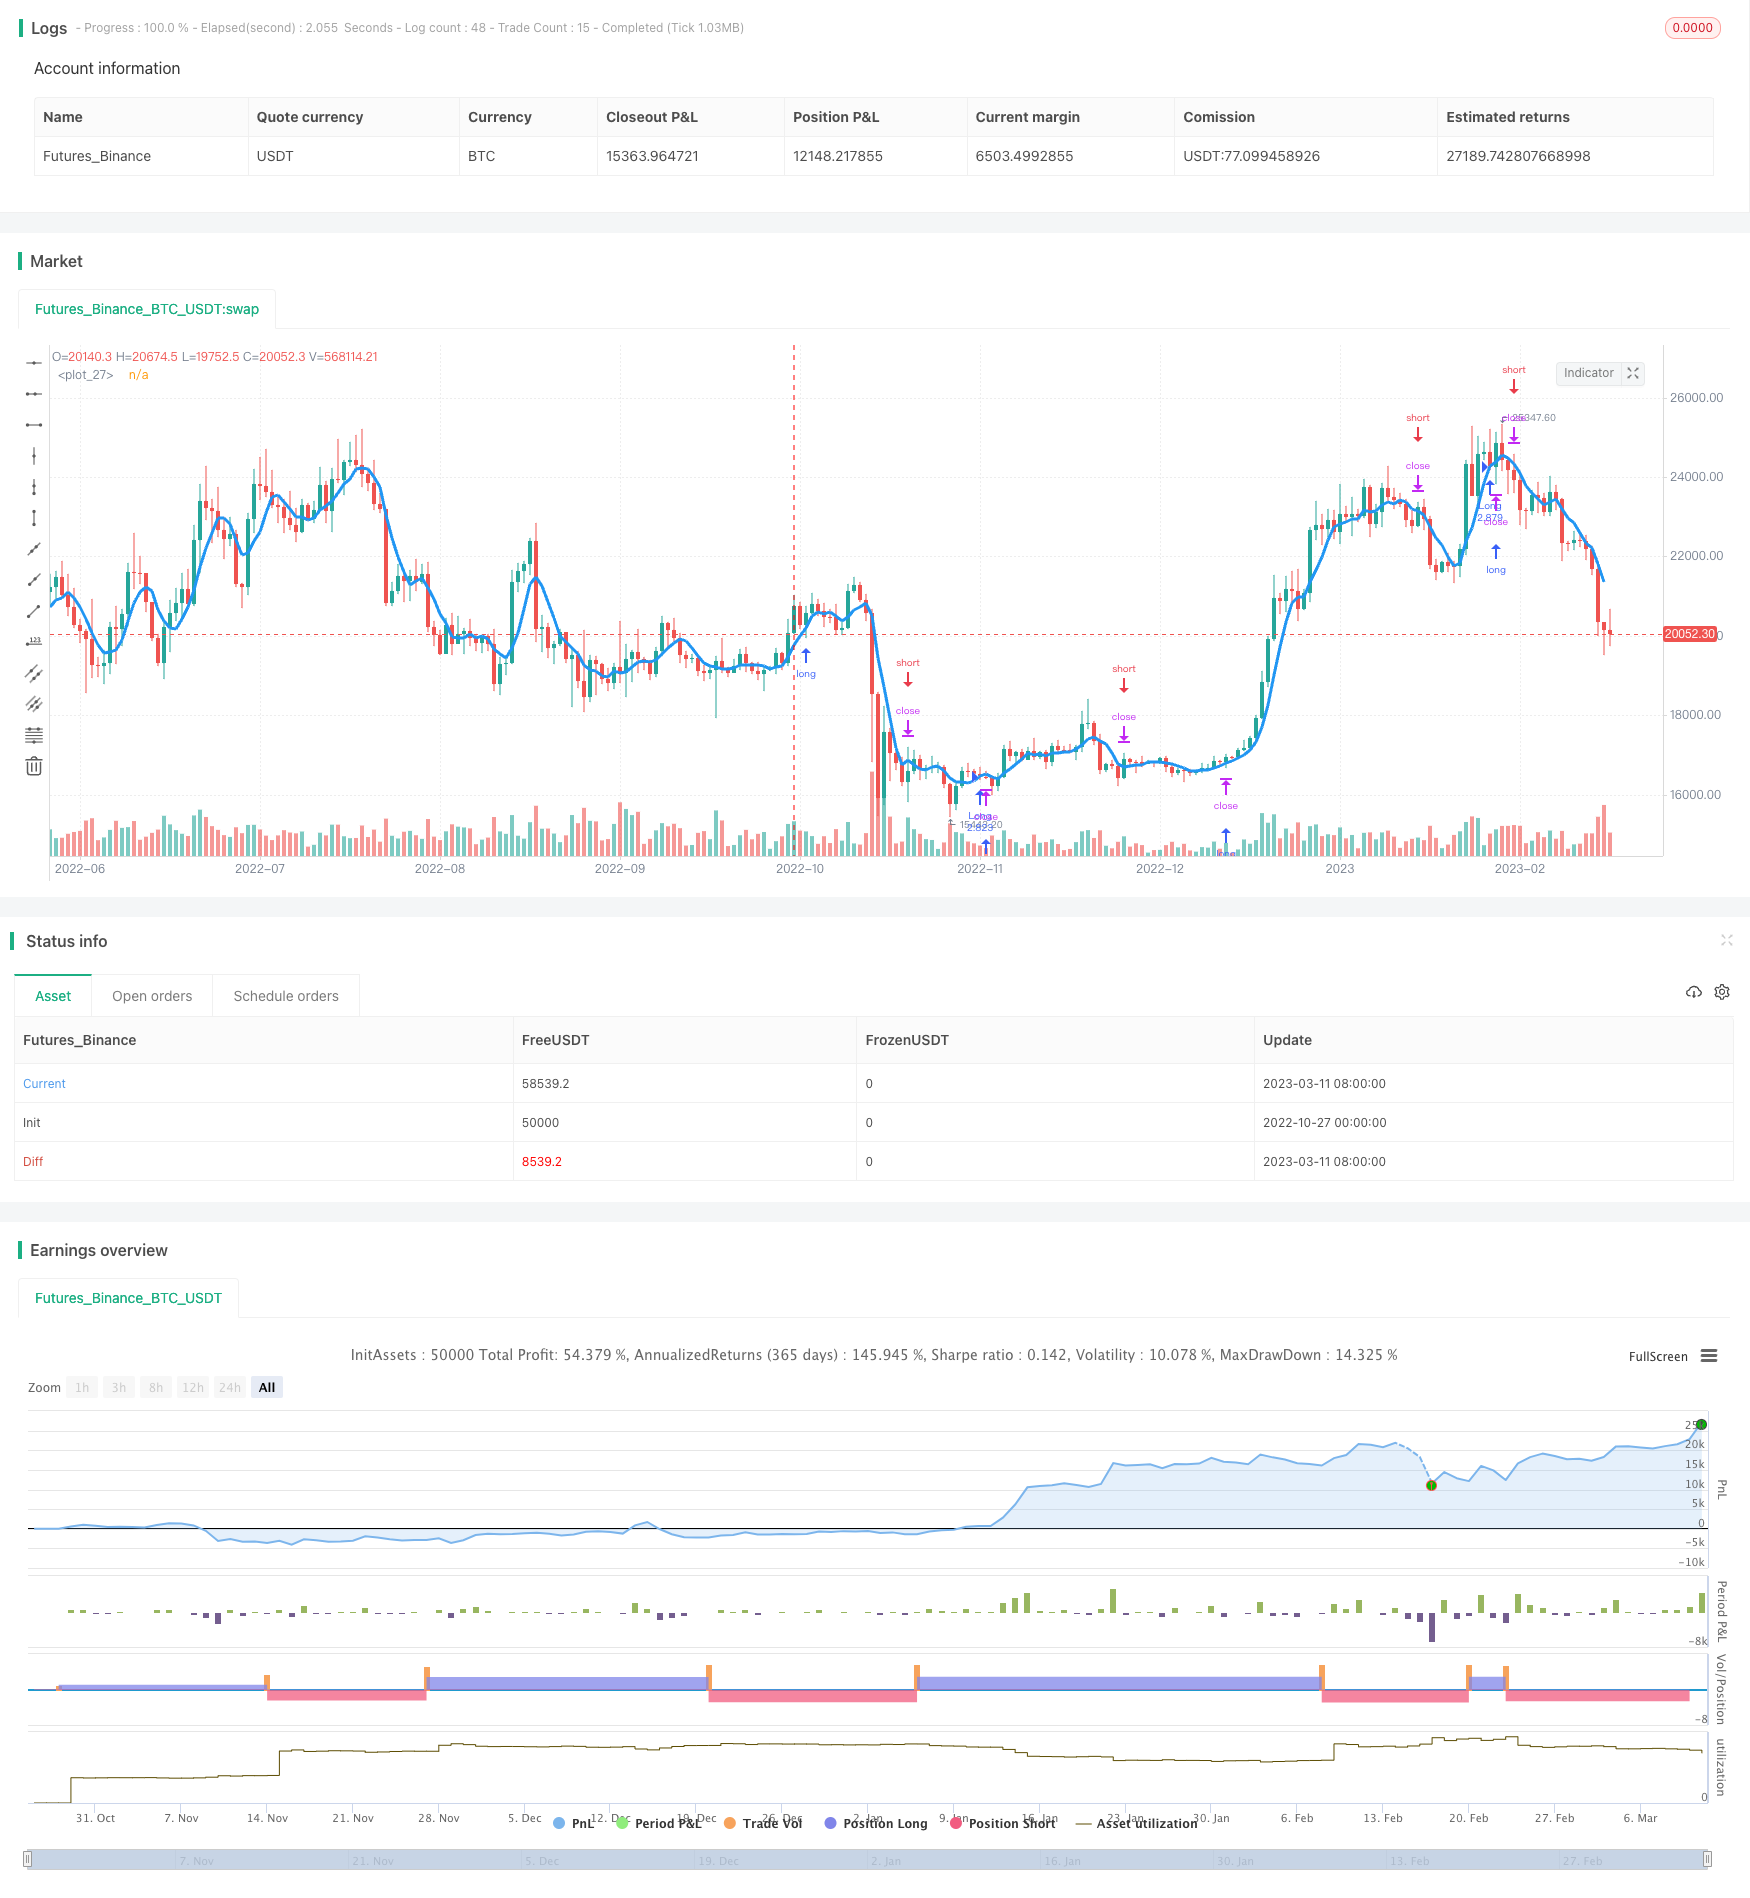
This strategy is a trend following trading strategy that uses simple moving average to determine market trend direction and place limit orders along the moving average line to follow the trend. 1. Calculate the…
Summary
This strategy is a trend following trading strategy that uses simple moving average to determine market trend direction and place limit orders along the moving average line to follow the trend.
Strategy Logic
Calculate the Simple Moving Average (SMA) and the trend direction trend.
If Anti-Saw filter is enabled, uptrend is identified when lows are above SMA, downtrend is identified when highs are below SMA. If Anti-Saw filter is disabled, uptrend is identified when close is above SMA, downtrend is identified when close is below SMA.
Place limit orders at SMA price according to the trend direction trend and enabled trading directions needlong and needshort:
If long trade is needed (needlong is true) and in uptrend, place long limit order at SMA price
If short trade is needed (needshort is true) and in downtrend, place short limit order at SMA price
Set stop loss logic to exit positions if position direction does not match trend direction.
Only trade within specified date range based on date range parameters.
Advantage Analysis
Using SMA to determine trend can effectively filter market noise and lock in longer term trend.
Placing limit orders at SMA price can get good entry points when trend starts.
Flexibility to only go long or short according to personal trading style.
Stop loss in place to avoid enlarging losses.
Trading time range sets to avoid volatility around major events.
Risk Analysis
SMA as trend indicator has lagging effect, may miss trend turning points and cause losses.
Limit orders lack flexibility, may not get into positions due to short term trend adjustments.
SMA period parameter needs proper configuration, improper settings lead to wrong trend determination.
Trading session parameters need to be reasonable to avoid missing opportunities or trading in risky periods.
Optimization Directions
Consider adding other indicators for multi-indicator confirmation, avoiding SMA lagging issues.
Switch to market order trailing when price breaks SMA, improving tracking flexibility.
Dynamically optimize SMA period to adapt to different market cycles.
Set stop loss to swing low/high instead of strictly at SMA price for more flexible stops.
Increase algorithmic elements for smarter dynamic trading sessions avoiding major risk events.
Summary
Overall this is a relatively simple trend following strategy, with the core idea of determining trend direction with SMA and placing limit orders at SMA price to follow the trend. With certain optimizations it can improve flexibility, adaptability and intelligence. The strategy is easy to understand and implement, suitable for algorithmic trading beginners, but requires risk awareness, cautious backtest evaluation, strict monitoring and optimization for live trading.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | true | long |
| v_input_2 | true | short |
| v_input_3 | 100 | Lot, % |
| v_input_4_close | 0 | MA Source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_5 | 5 | SMA length |
| v_input_6 | false | SMA offset |
| v_input_7 | true | Anti-saw filter |
| v_input_8 | false | Reverse |
| v_input_9 | true | Show MA |
| v_input_10 | false | Show background |
| v_input_11 | 1900 | From Year |
| v_input_12 | 2100 | To Year |
| v_input_13 | true | From Month |
| v_input_14 | 12 | To Month |
| v_input_15 | true | From day |
| v_input_16 | 31 | To day |
Source Pine Script
/*backtest
start: 2022-10-27 00:00:00
end: 2023-03-12 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//Noro
//2020

//@version=4
strategy(title = "Noro's CrossLimit", shorttitle = "CrossLimit", overlay = true, default_qty_type = strategy.percent_of_equity, default_qty_value = 100.0, pyramiding = 0, commission_value = 0.0)

needlong = input(true, "long")
needshort = input(true, "short")
lotsize = input(100, defval = 100, minval = 1, maxval = 10000, title = "Lot, %")
src = input(close, defval = close, title = "MA Source")
len = input(5, defval = 5, minval = 1, title = "SMA length")
off = input(0, defval = 0, minval = 0, title = "SMA offset")
anti = input(true, defval = true, title = "Anti-saw filter")
rev = input(false, defval = false, title = "Reverse")
showma = input(true, defval = true, title = "Show MA")
showbg = input(false, defval = false, title = "Show background")
fromyear = input(1900, defval = 1900, minval = 1900, maxval = 2100, title = "From Year")
toyear = input(2100, defval = 2100, minval = 1900, maxval = 2100, title = "To Year")
frommonth = input(01, defval = 01, minval = 01, maxval = 12, title = "From Month")
tomonth = input(12, defval = 12, minval = 01, maxval = 12, title = "To Month")
fromday = input(01, defval = 01, minval = 01, maxval = 31, title = "From day")
today = input(31, defval = 31, minval = 01, maxval = 31, title = "To day")

//MA
ma = sma(src, len)[off]
macol = showma ? color.blue : na
plot(ma, color = macol, linewidth = 3, transp = 0)

//Background
trend = 0
trend := anti == false and close > ma ? 1 : anti == false and close < ma ? -1 : low > ma ? 1 : high < ma ? -1 : trend[1]
bgcol = showbg ? trend == 1 ? color.lime : trend == -1 ? color.red : na : na
bgcolor(bgcol, transp = 70)

//Signals
bar = close > open ? 1 : close < open ? -1 : 0
up = (trend == 1 and rev == false) or (trend == -1 and rev == true)
dn = (trend == -1 and rev == false) or (trend == 1 and rev == true)

//Trading
size = strategy.position_size
truetime = time > timestamp(fromyear, frommonth, fromday, 00, 00) and time < timestamp(toyear, tomonth, today, 23, 59)
lot = 0.0
lot := size != size[1] ? strategy.equity / close * lotsize / 100 : lot[1]
if trend != 0
    strategy.entry("Long", strategy.long, lot, limit = ma, when = needlong and truetime and up)
    strategy.entry("Short", strategy.short, lot, limit = ma, when = needshort and truetime and dn)
if size > 0 and needshort == false and trend == -1
    strategy.exit("Stop Long", "Long", limit = ma)
if size < 0 and needlong == false and trend == 1
    strategy.exit("Stop Short", "Short", limit = ma)
if time > timestamp(toyear, tomonth, today, 23, 59)
    strategy.close_all()
    strategy.cancel("Long")
strategy.cancel("Short")Published by ChaoZhang on the FMZ strategy square · last modified 2023-11-03. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Cross-Limit-Order-Cross-Period-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ADX MA and EMA Long Only Trend Tracking StrategyPine Script · Trend following · 1d
- ATR and Moving Average Crossover Hybrid StrategyPine Script · Trend following · 1h
- Adaptive FVG Detection and MA Trend Trading Strategy with Dynamic ResistancePine Script · Trend following · 1d
- Adaptive Risk Management Strategy Based on Dynamic ATR and Moving Average CrossoverPine Script · Trend following · 2h
- Adaptive Trading Strategy Based on Stochastic RSI Dual Line CrossoverPine Script · Trend following · 4h
- Adaptive Volatility Based Trend Following Short Strategy with Time Delay and Stop Loss ProtectionPine Script · Trend following · 2m