Strategy vault / Mean reversion
Cross Moving Average Reversal Strategy
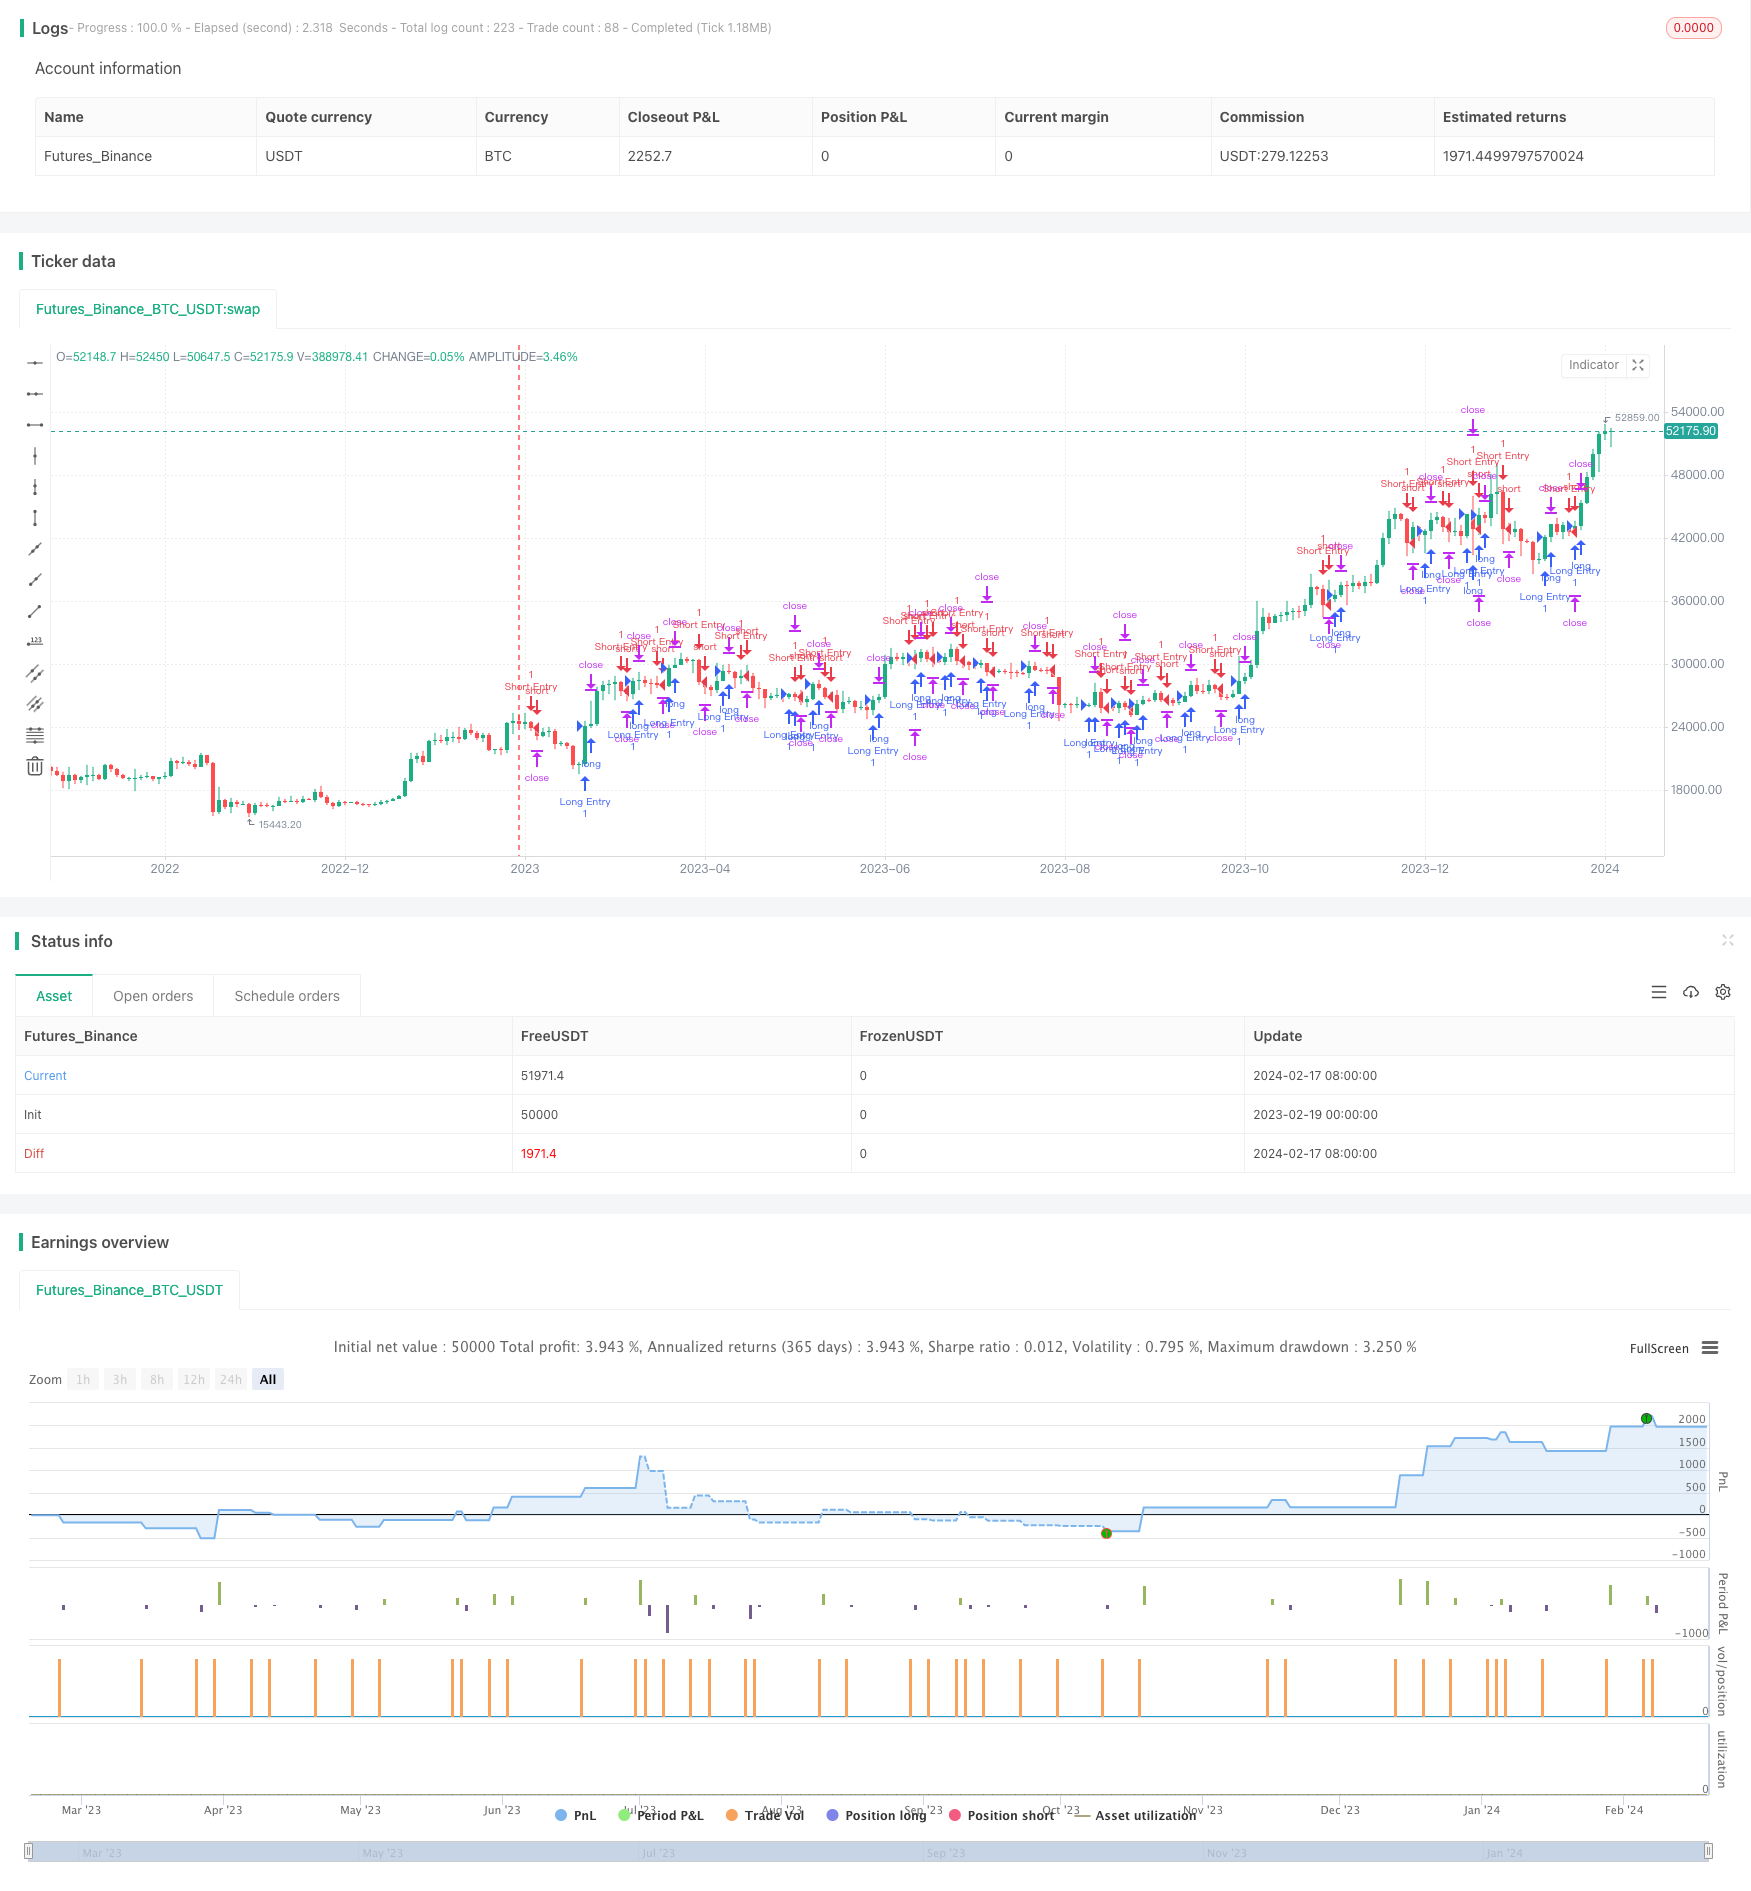
This is a reversal strategy based on simple moving average crossover. It uses 1-day and 5-day simple moving averages. When the shorter SMA crosses above the longer SMA, it goes long. When the shorter SMA crosses…
Overview
This is a reversal strategy based on simple moving average crossover. It uses 1-day and 5-day simple moving averages. When the shorter SMA crosses above the longer SMA, it goes long. When the shorter SMA crosses below the longer SMA, it goes short. It's a typical trend following strategy.
Strategy Logic
The strategy calculates the 1-day SMA (sma1) and 5-day SMA (sma5) of the closing price. When sma1 crosses over sma5, it enters a long position. When sma1 crosses below sma5, it enters a short position. After opening a long position, the stop loss is set at 5 USD below the entry price and take profit at 150 USD above. For short positions, stop loss is 5 USD above entry and take profit 150 USD below.
Advantage Analysis
- Using double SMAs to determine market trend, avoiding loss trades after stop loss
- SMA parameters simple and reasonable, good backtest results
- Small stop loss to withstand certain price fluctuations
- Big profit target to make enough money
Risk Analysis
- Double SMAs are prone to whipsaws, high probability of stop loss when choppy
- Hard to catch trending moves, limited profit for long term trades
- Limited optimization space, easy to overfit
- Parameters need adjustment for different trading instruments
Improvement Directions
- Add other filters to avoid wrong signals
- Dynamic stop loss and take profit
- Optimize SMA parameters
- Combine volatility index to control position sizing
Conclusion
This simple double SMA strategy is easy to understand and implement for fast strategy verification. But it has limited risk tolerance and profit potential. Further optimizations are needed in parameters and filters to adapt more market conditions. As a starter quant strategy, it contains basic building blocks for iterable improvements.
Source Pine Script
/*backtest
start: 2023-02-19 00:00:00
end: 2024-02-19 00:00:00
period: 2d
basePeriod: 1d
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("Valeria 181 Bot Strategy Mejorado 2.21", overlay=true, margin_long=100, margin_short=100)

var float lastLongOrderPrice = na
var float lastShortOrderPrice = na

longCondition = ta.crossover(ta.sma(close, 1), ta.sma(close, 5))
if (longCondition)
    strategy.entry("Long Entry", strategy.long)  // Enter long

shortCondition = ta.crossunder(ta.sma(close, 1), ta.sma(close, 5))
if (shortCondition)
    strategy.entry("Short Entry", strategy.short)  // Enter short

if (longCondition)
    lastLongOrderPrice := close

if (shortCondition)
    lastShortOrderPrice := close

// Calculate stop loss and take profit based on the last executed order's price
stopLossLong = lastLongOrderPrice - 5  // 10 USDT lower than the last long order price
takeProfitLong = lastLongOrderPrice + 151  // 100 USDT higher than the last long order price
stopLossShort = lastShortOrderPrice + 5  // 10 USDT higher than the last short order price
takeProfitShort = lastShortOrderPrice - 150  // 100 USDT lower than the last short order price

// Apply stop loss and take profit to long positions
strategy.exit("Long Exit", from_entry="Long Entry", stop=stopLossLong, limit=takeProfitLong)

// Apply stop loss and take profit to short positions
strategy.exit("Short Exit", from_entry="Short Entry", stop=stopLossShort, limit=takeProfitShort)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-02-20. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Cross-Moving-Average-Reversal-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- 3 10 Oscillator Profile Flagging StrategyPine Script · Mean reversion · 1d
- A Trend Reversal Strategy Based on Moving Averages Price Patterns and VolumePine Script · Mean reversion · 1d
- Adaptive Mean Reversion Trading Strategy Based on Chande Momentum OscillatorPine Script · Mean reversion · 1d
- Adaptive Trading Strategy Combining Dynamic Trend Reversal and Stochastic IndicatorPine Script · Mean reversion · 1d
- Advanced 15 Minute Chart Trading Signal StrategyPine Script · Mean reversion · 3h
- Advanced Momentum EMA Trend Following with RSI Overbought Oversold Trading StrategyPine Script · Mean reversion · 1d