Cross Timeframe Double Breakout Levels Strategy
This is a strategy that utilizes key levels on different timeframes to generate double breakout trading signals. It can enter long or short positions when trend prices break through key support or resistance levels…
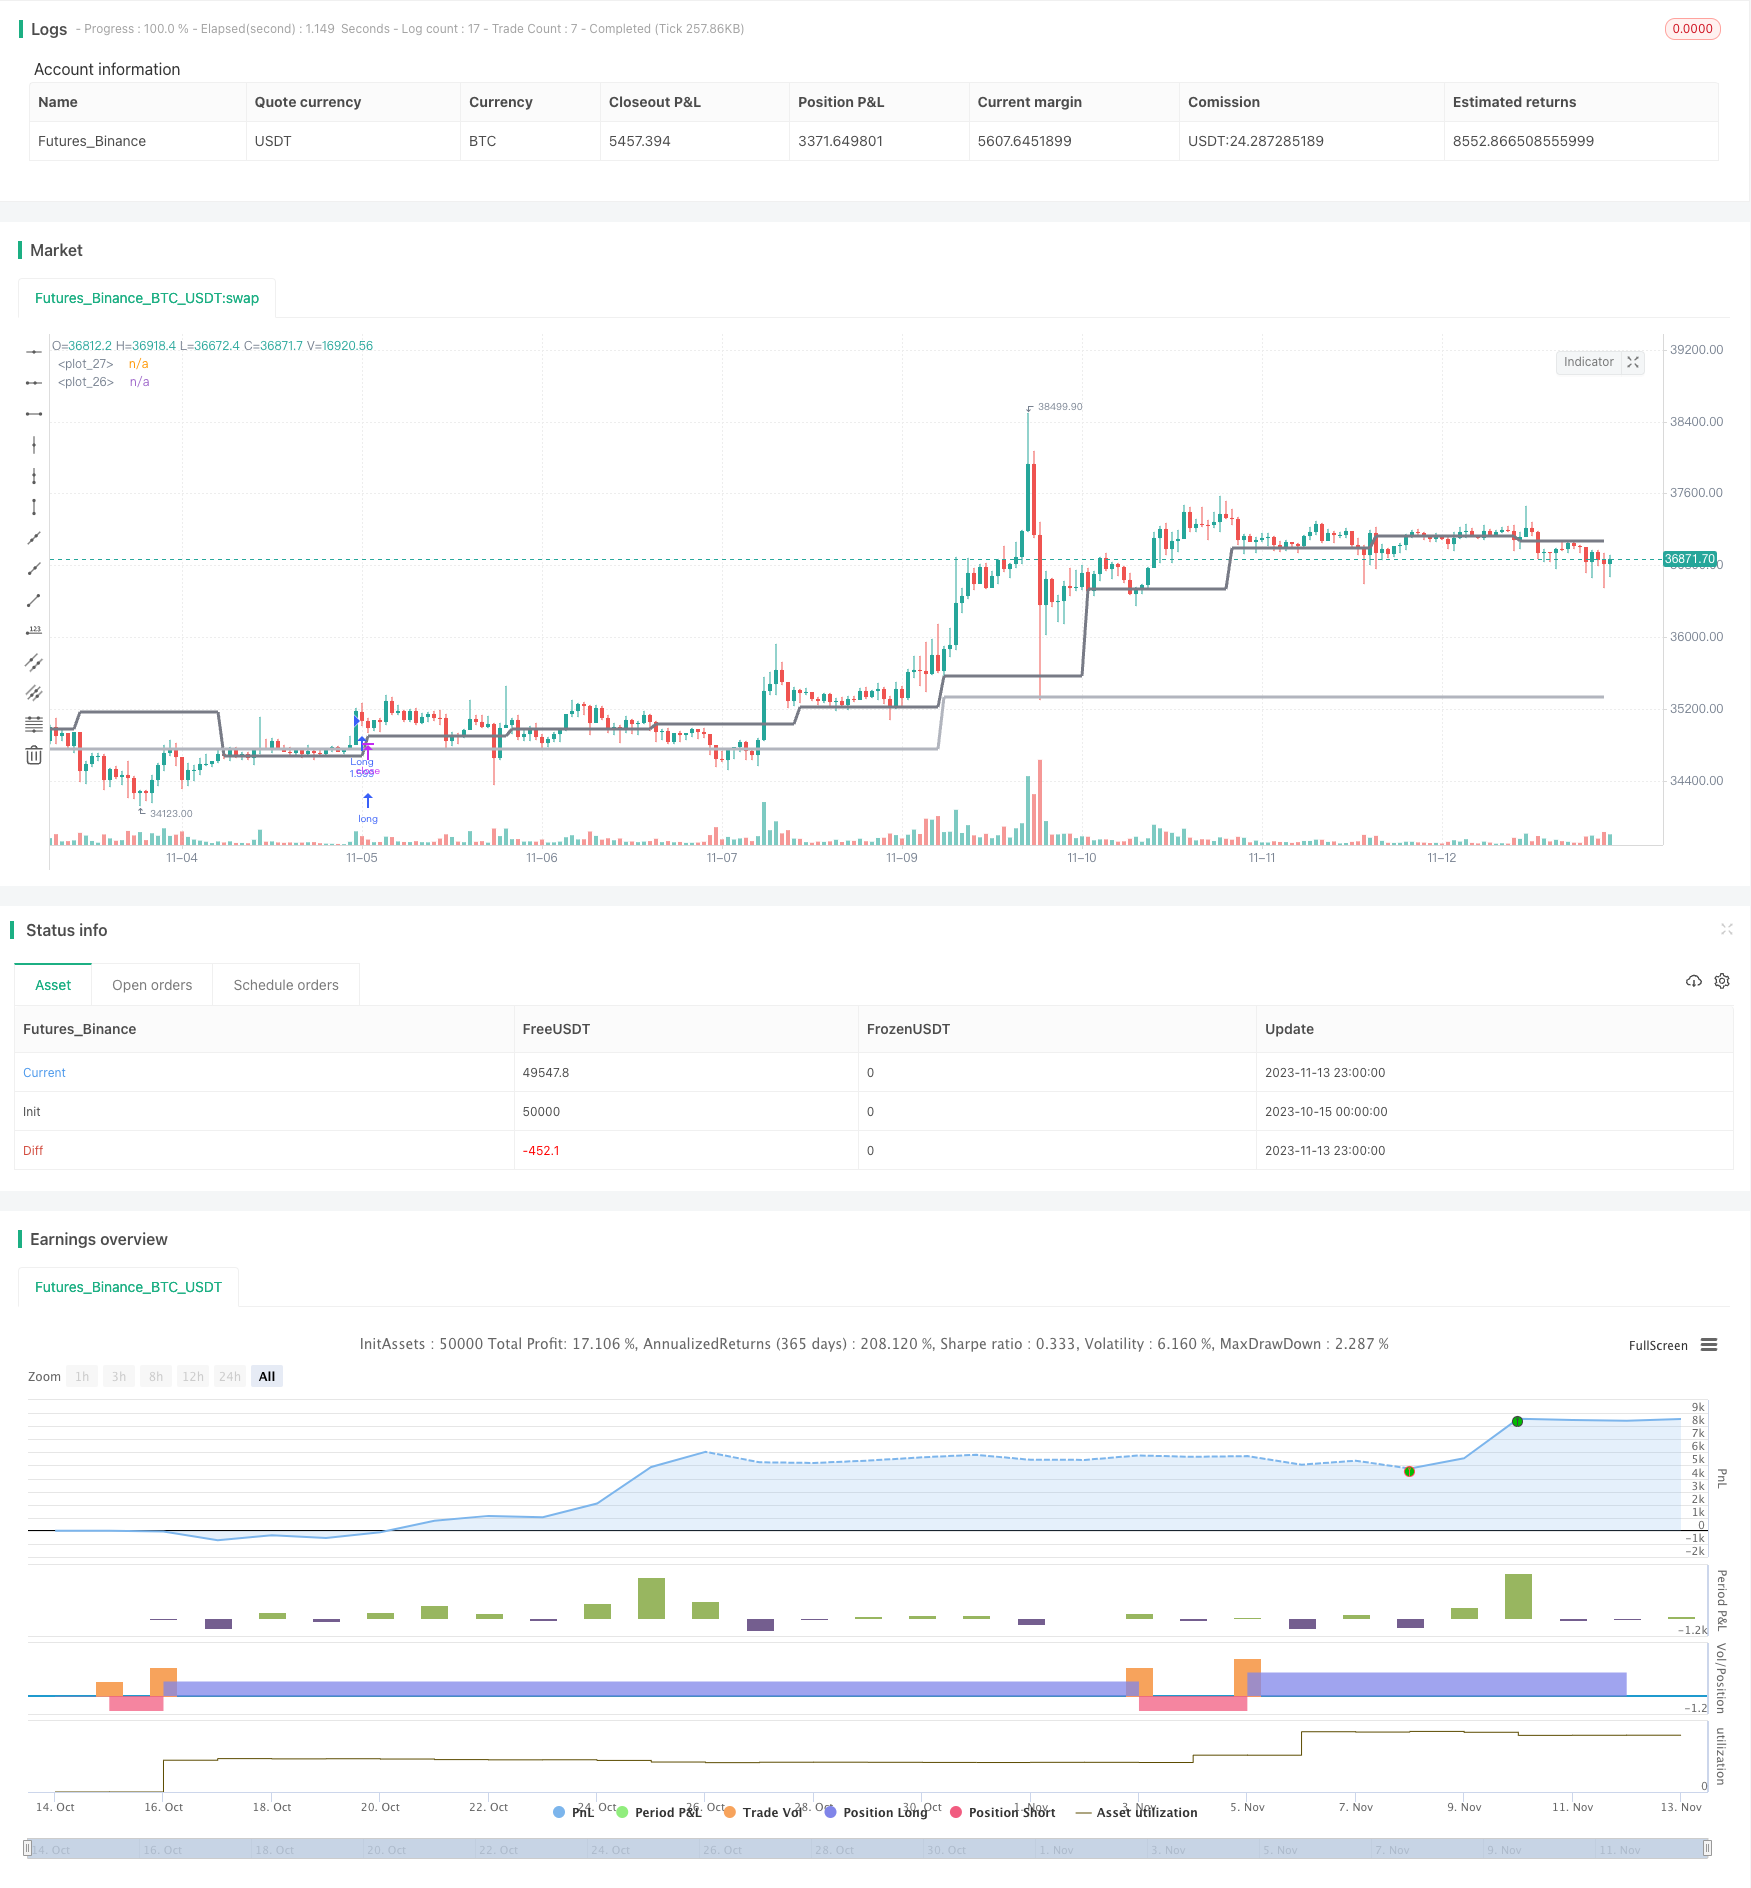
Overview
This is a strategy that utilizes key levels on different timeframes to generate double breakout trading signals. It can enter long or short positions when trend prices break through key support or resistance levels to capture mid-to-long term trends.
Strategy Logic
The strategy analyzes price action simultaneously on two different timeframes (tf and tf2), with tf being the longer timeframe reflecting the mid-to-long term trend, and tf2 being the shorter timeframe reflecting short-term moves. The strategy monitors the following trading signals:
- When price breaks above the level (level) on tf timeframe, record up1=true
- When price breaks below the level on tf timeframe, record dn1=true
- When price breaks above the level (level2) on tf2 timeframe, record up2=true
- When price breaks below the level on tf2 timeframe, record dn2=true
The trading signal is formed when up1 and up2 are true together, indicating long and short term are both bullish, go long; when dn1 and dn2 are both true, indicating long and short term both bearish, go short.
The strategy also incorporates some filters such as inverse scalping and color candlesticks to avoid wrong signals from non-trending breakouts.
Overall, the strategy takes full advantage of multi-timeframe analysis, ensuring the mid-to-long term trend meets expectations while avoiding interference from short-term market noise, generating high quality trading signals.
Advantage Analysis
Catch mid-to-long term trends by breaking key levels
By monitoring key level breakouts across two timeframes, it can capture clear entry signals at trend initiation stages.
Dual confirmation significantly reduces false signals
Requiring concurrent breakouts on two different timeframes greatly lowers false signals from random fluctuations, improving signal quality.
Filters such as inverse scalps and color candlesticks
Adding inverse scalping and color candle filters can remove some low quality breakout signals and prevent huge losses.
Simple parameter settings
The strategy only needs two timeframe parameters to function, offers flexible tuning for different products.
Easy to understand and optimize
The clear structure makes it easy to understand the logic, and parameters can be adjusted based on market conditions for optimization.
Risk Analysis
Delayed entry due to dual breakout
Compared to single breakout, dual breakout may cause some entry delay, missing early strong trend profits.
Key level selection
Selecting suitable key levels for different products and market cycles is very important, otherwise it may generate false signals.
Breakout failure
Even with dual breakout, there is still a chance of breakout failure and fast pullback, causing losses.
Loss from trend reversal
Late trend entries may face sudden reversal, unable to exit in time through stop loss and incur large losses.
Difficult parameter optimization
Although simple, finding the optimal parameter set still requires extensive testing, with high optimization difficulty.
Optimization Directions
Add stop loss strategies
Can set trailing stop or time stop to stop loss before loss gets too big.
Optimize filters
Can test different inverse scalp amplitude parameters or other filter methods.
Dynamic key levels
Make key levels change dynamically with market shifts rather than static levels.
Multi-product parameter optimization
Use machine learning to optimize best parameter sets for different products.
Add volume confirmation
Incorporate volume confirmation to avoid false breakout signals without volume.
Summary
Overall this is a simple and practical trend following strategy. By analyzing two timeframes it enters on mid-to-long term direction conformity to filter noise effectively. The signals are clear and easy to interpret, with intuitive parameter settings. But it also has issues like mistimed entry, difficulty selecting key levels. In summary, this strategy works better as a trend validation tool to combine with other factors, but still has much room for optimization as a standalone trading system.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | true | Long |
| v_input_2 | true | Short |
| v_input_3 | 100 | Capital, % |
| v_input_4 | W | timeframe 1 |
| v_input_5 | D | timeframe 2 |
| v_input_6_ohlc4 | 0 | Source: ohlc4 | high | low | open | hl2 | hlc3 | hlcc4 | close |
| v_input_7 | true | antipila |
| v_input_8 | true | color filter |
| v_input_9 | 1900 | From Year |
| v_input_10 | 2100 | To Year |
| v_input_11 | true | From Month |
| v_input_12 | 12 | To Month |
| v_input_13 | true | From day |
| v_input_14 | 31 | To day |
Source Pine Script
/*backtest
start: 2023-10-15 00:00:00
end: 2023-11-14 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//Noro
//2018

//@version=2
strategy(title = "Noro's Levels Strategy v1.0", shorttitle = "Levels str 1.0", overlay = true, default_qty_type = strategy.percent_of_equity, default_qty_value = 100, pyramiding = 0)

//Settings
needlong = input(true, defval = true, title = "Long")
needshort = input(true, defval = true, title = "Short")
capital = input(100, defval = 100, minval = 1, maxval = 10000, title = "Capital, %")
tf = input('W',  title = "timeframe 1")
tf2 = input('D',  title = "timeframe 2")
src = input(ohlc4, "Source")
ap = input(true, defval = true, title = "antipila")
cf = input(true, defval = true, title = "color filter")
fromyear = input(1900, defval = 1900, minval = 1900, maxval = 2100, title = "From Year")
toyear = input(2100, defval = 2100, minval = 1900, maxval = 2100, title = "To Year")
frommonth = input(01, defval = 01, minval = 01, maxval = 12, title = "From Month")
tomonth = input(12, defval = 12, minval = 01, maxval = 12, title = "To Month")
fromday = input(01, defval = 01, minval = 01, maxval = 31, title = "From day")
today = input(31, defval = 31, minval = 01, maxval = 31, title = "To day")

//Signals
level = request.security(syminfo.tickerid, tf, src[1])
level2 = request.security(syminfo.tickerid, tf2, src[1])
plot(level, linewidth = 3, color = silver)
plot(level2, linewidth = 3, color = gray)
up1 = close > level and ap == false ? true : low > level ? true : false
dn1 = close < level and ap == false ? true : high < level ? true : false
up2 = close > level2 and ap == false ? true : low > level2 ? true : false
dn2 = close < level2 and ap == false ? true : high < level2 ? true : false

//Trading
lot = strategy.position_size != strategy.position_size[1] ? strategy.equity / close * capital / 100 : lot[1]

if up1 and up2 and (close < open or cf == false)
    strategy.entry("Long", strategy.long, needlong == false ? 0 : lot, when = (time > timestamp(fromyear, frommonth, fromday, 00, 00) and time < timestamp(toyear, tomonth, today, 23, 59)))

if dn1 and dn2 and (close > open or cf == false)
    strategy.entry("Short", strategy.short, needshort == false ? 0 : lot, when = (time > timestamp(fromyear, frommonth, fromday, 00, 00) and time < timestamp(toyear, tomonth, today, 23, 59)))

if time > timestamp(toyear, tomonth, today, 23, 59)
    strategy.close_all()
Published by ChaoZhang on the FMZ strategy square · last modified 2023-11-15. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Cross-Timeframe-Double-Breakout-Levels-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- 5 Day Moving Average Channel Breakout Strategy Combined With Mileage ConceptPine Script · Breakout · 1d
- ATR Trailing Stops StrategyPine Script · Breakout · 1h
- ATR Trend Breakout StrategyPine Script · Breakout · 1d
- Adaptive Bollinger Breakout with Moving Average Quantitative Strategy SystemPine Script · Breakout · 1h
- Adaptive Channel Breakout StrategyPine Script · Breakout · 1d
- Adaptive Multi Period Trading Strategy Based on Wave Trend Momentum BreakoutPine Script · Breakout · 2h