Daily Breakout Strategy
The daily breakout strategy is a simple trend following strategy based on daily candlestick charts. It generates trading signals by observing the relationship between the previous day's opening and closing prices to…
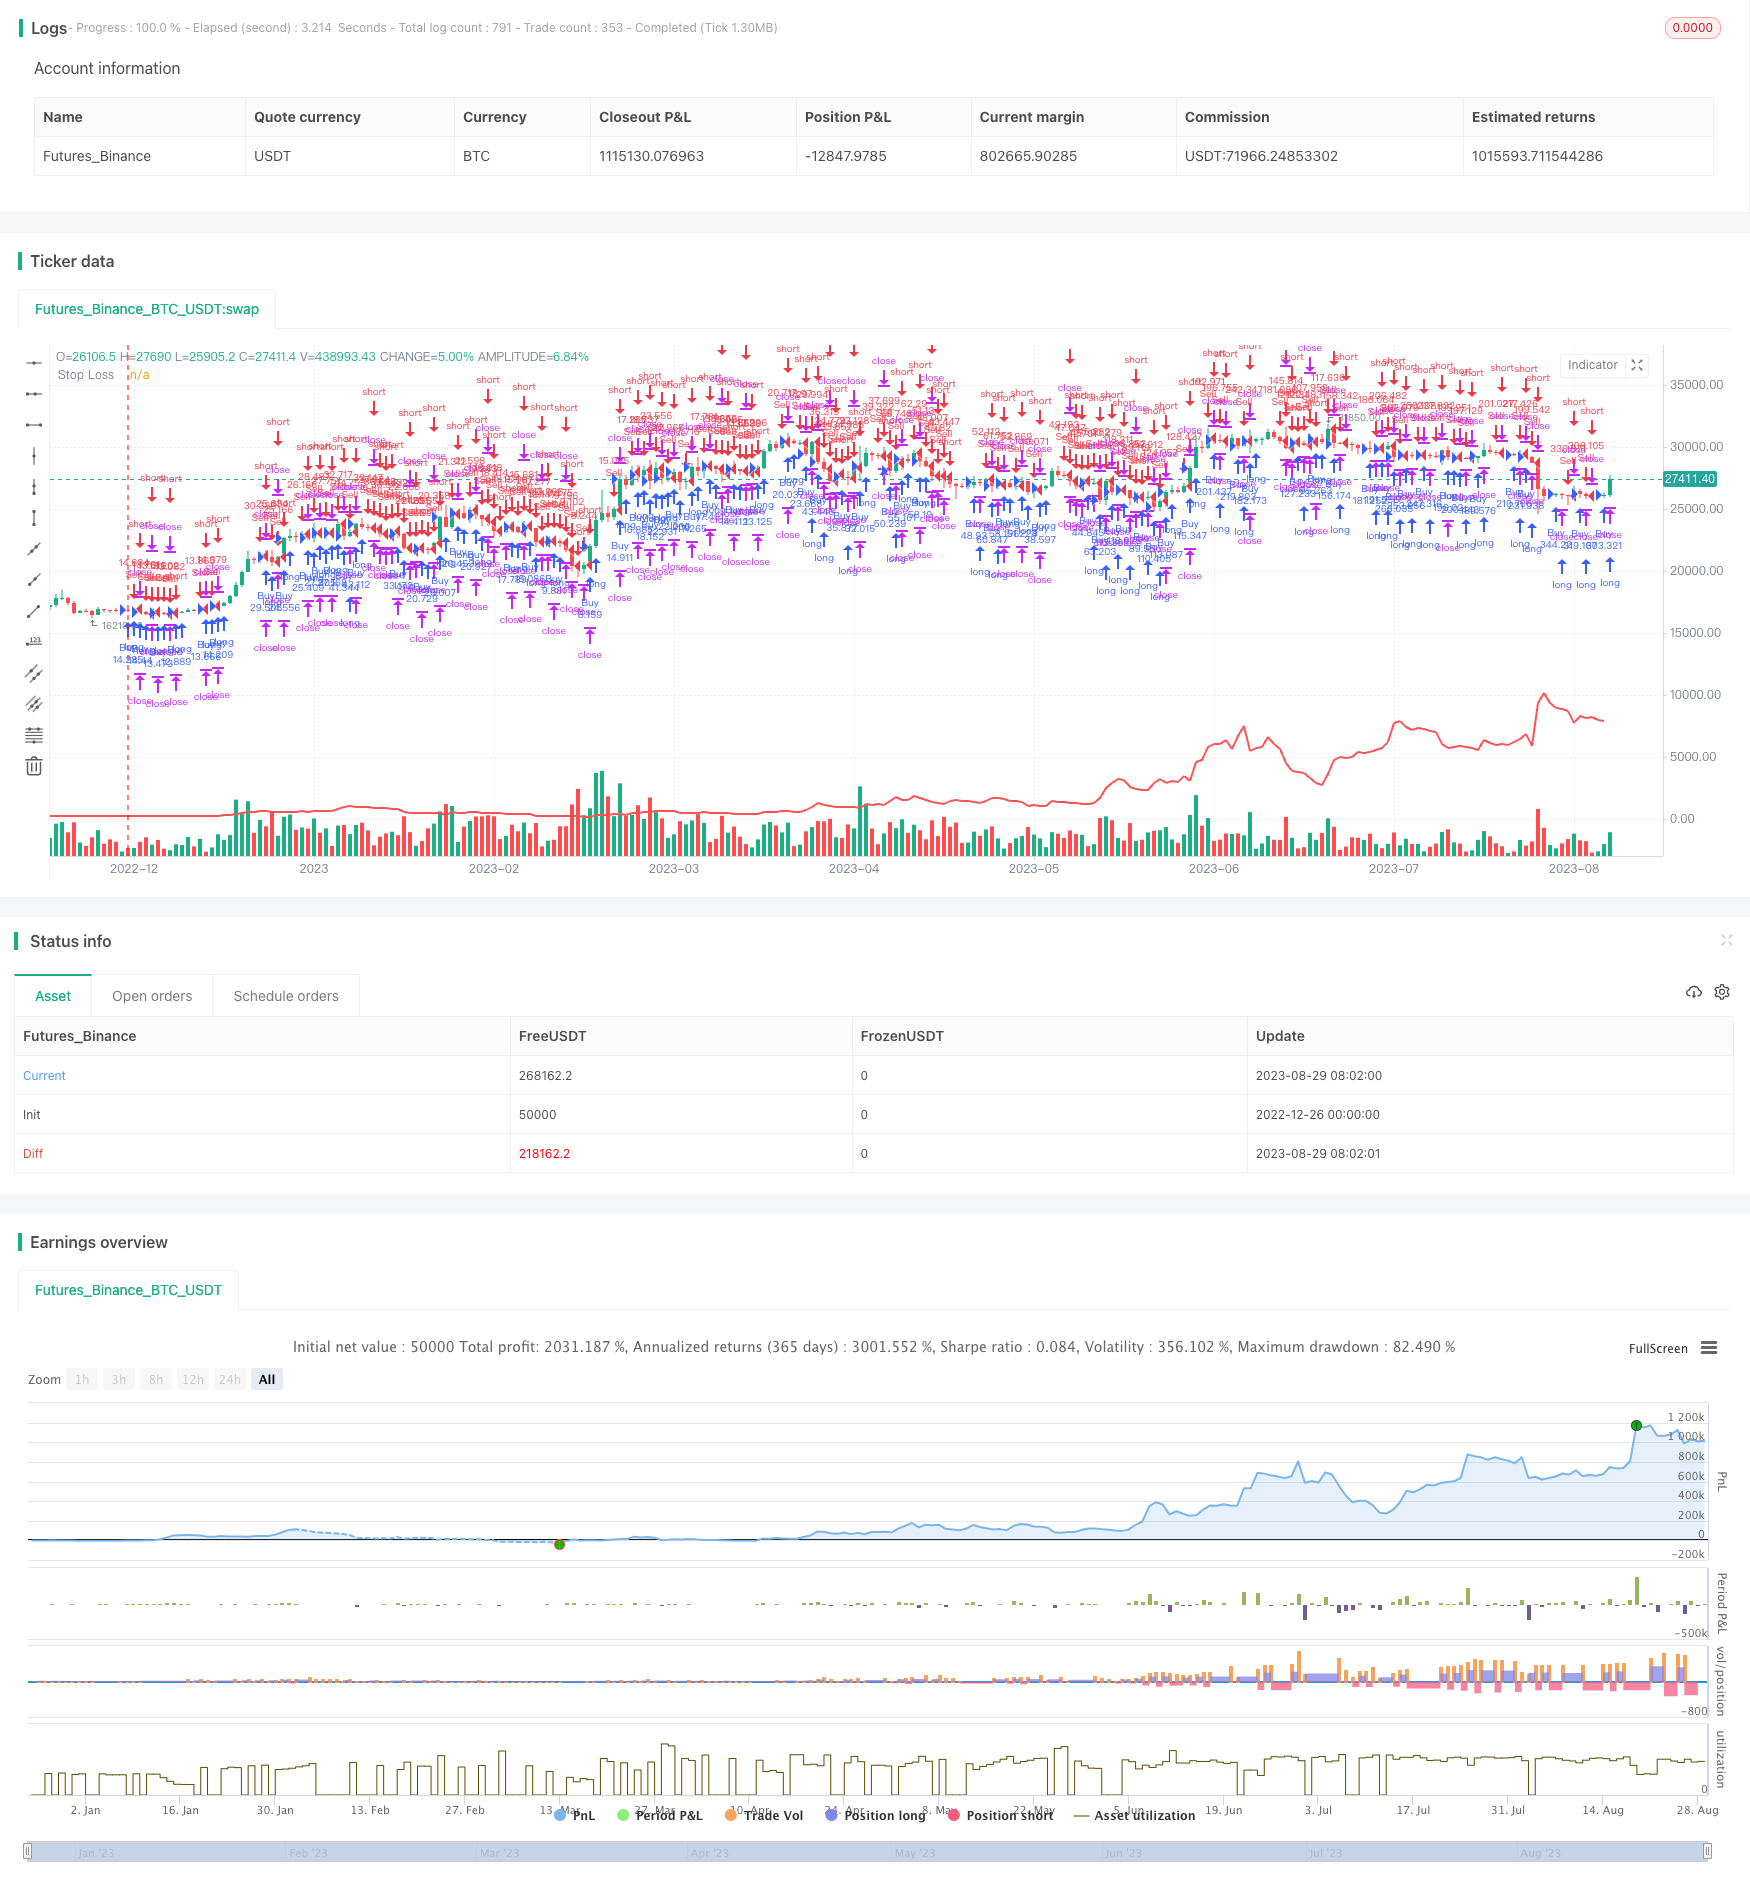
Overview
The daily breakout strategy is a simple trend following strategy based on daily candlestick charts. It generates trading signals by observing the relationship between the previous day's opening and closing prices to determine market momentum.
Strategy Logic
The core logic of this strategy is:
If the previous day's candlestick body is green (closing price higher than opening price), it indicates an upward trend on that day. The strategy will go long at the next day's opening. If the previous day's candlestick body is red (closing price lower than opening price), it indicates a downward trend. The strategy will go short at the next day's opening.
By this simple way, the strategy can identify the market momentum within the recent one candlestick cycle and make trades accordingly. This allows the strategy to follow the latest market trend.
Specifically, the strategy generates trading signals as follows:
- Get the previous trading day's candlestick data at market open each day
- Compare the opening and closing prices of that candlestick
- If open < close (green candlestick), generate long signal, go long at a percentage of available funds
- If open > close (red candlestick), generate short signal, go short at a percentage of available funds
- Use stop loss to exit positions
Through this logic, the strategy can capitalize on short-term price trends.
Advantages
The main advantages of this strategy include:
- Simplicity - The core logic directly compares candlestick color and is very simple and clear.
- Trend following - It identifies the trend direction of the latest trading day, following shorter-term momentum.
- Flexibility - Parameters like position sizing, stop loss can be adjusted to modify risk vs. reward.
- Optimization potential - More enhancements can be added, like multiple timeframe analysis and data fitting to improve robustness.
Risks and Improvements
Some risks and improvement areas:
- Whipsaw risk - It only looks at the daily candle, so may falsely buy pullbacks instead of actual trend in ranging markets. Additional timeframe or indicators can be added to judge consolidation.
- Shorting risk - Short positions have unlimited downside risk. Strict stop loss needs to be implemented.
- Parameter tuning - Fine tune stop loss level, position sizing etc. to achieve better risk-adjusted returns.
- Add indicators - Incorporate more technical indicators to improve robustness and stability.
Conclusion
The daily breakout strategy identifies market momentum through simple and effective comparison of daily candlesticks, allowing it to trade in the direction of shorter-term trends. While simple and easy to implement, it has whipsaw risks. Further optimizations on parameters and additional indicators can enhance strategy reliability.
Source Pine Script
/*backtest
start: 2022-12-26 00:00:00
end: 2023-08-30 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("Daily Candle Strategy", overlay=true, default_qty_type=strategy.percent_of_equity, default_qty_value=0.0)

// Input parameters
initialCapital = 10000
riskFactor = 3500

// Calculate the opening and closing values for the last day's candle
lastDayOpen = request.security(syminfo.tickerid, "D", open[1], lookahead=barmerge.lookahead_on)
lastDayClose = request.security(syminfo.tickerid, "D", close[1], lookahead=barmerge.lookahead_on)

// Determine the color of the last day's candle
lastDayColor = lastDayOpen < lastDayClose ? color.green : color.red

// Plot the last day's candle on the chart
plotshape(series=na, color=lastDayColor, style=shape.triangledown, location=location.abovebar)

// Calculate trade size based on available capital at last day's closing
availableCapital = strategy.equity
tradeSize = availableCapital / riskFactor

// Trading conditions
buyCondition = lastDayColor == color.green
sellCondition = lastDayColor == color.red

// Execute strategy orders with calculated trade size
strategy.entry("Buy", strategy.long, qty=tradeSize, when=buyCondition)
strategy.entry("Sell", strategy.short, qty=tradeSize, when=sellCondition)

// Exit strategy
stopLoss = 0.001 * lastDayOpen * tradeSize
strategy.exit("StopLoss/Profit", from_entry="Buy", loss=stopLoss)
strategy.exit("StopLoss/Profit", from_entry="Sell", loss=stopLoss)

// Plot stop loss level on the chart
plot(stopLoss, color=color.red, linewidth=2, title="Stop Loss")
Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-02. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Daily-Breakout-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- 5 Day Moving Average Channel Breakout Strategy Combined With Mileage ConceptPine Script · Breakout · 1d
- ATR Trailing Stops StrategyPine Script · Breakout · 1h
- ATR Trend Breakout StrategyPine Script · Breakout · 1d
- Adaptive Bollinger Breakout with Moving Average Quantitative Strategy SystemPine Script · Breakout · 1h
- Adaptive Channel Breakout StrategyPine Script · Breakout · 1d
- Adaptive Multi Period Trading Strategy Based on Wave Trend Momentum BreakoutPine Script · Breakout · 2h