Strategy vault / DCA & fixed investment
DCA Strategy with Trailing Take Profit
This strategy combines Dollar Cost Averaging (DCA) with the trailing take profit feature available on exchange platforms. It sets a 1% price deviation for purchases and targets 0.5% profit on each sale. The rationale…
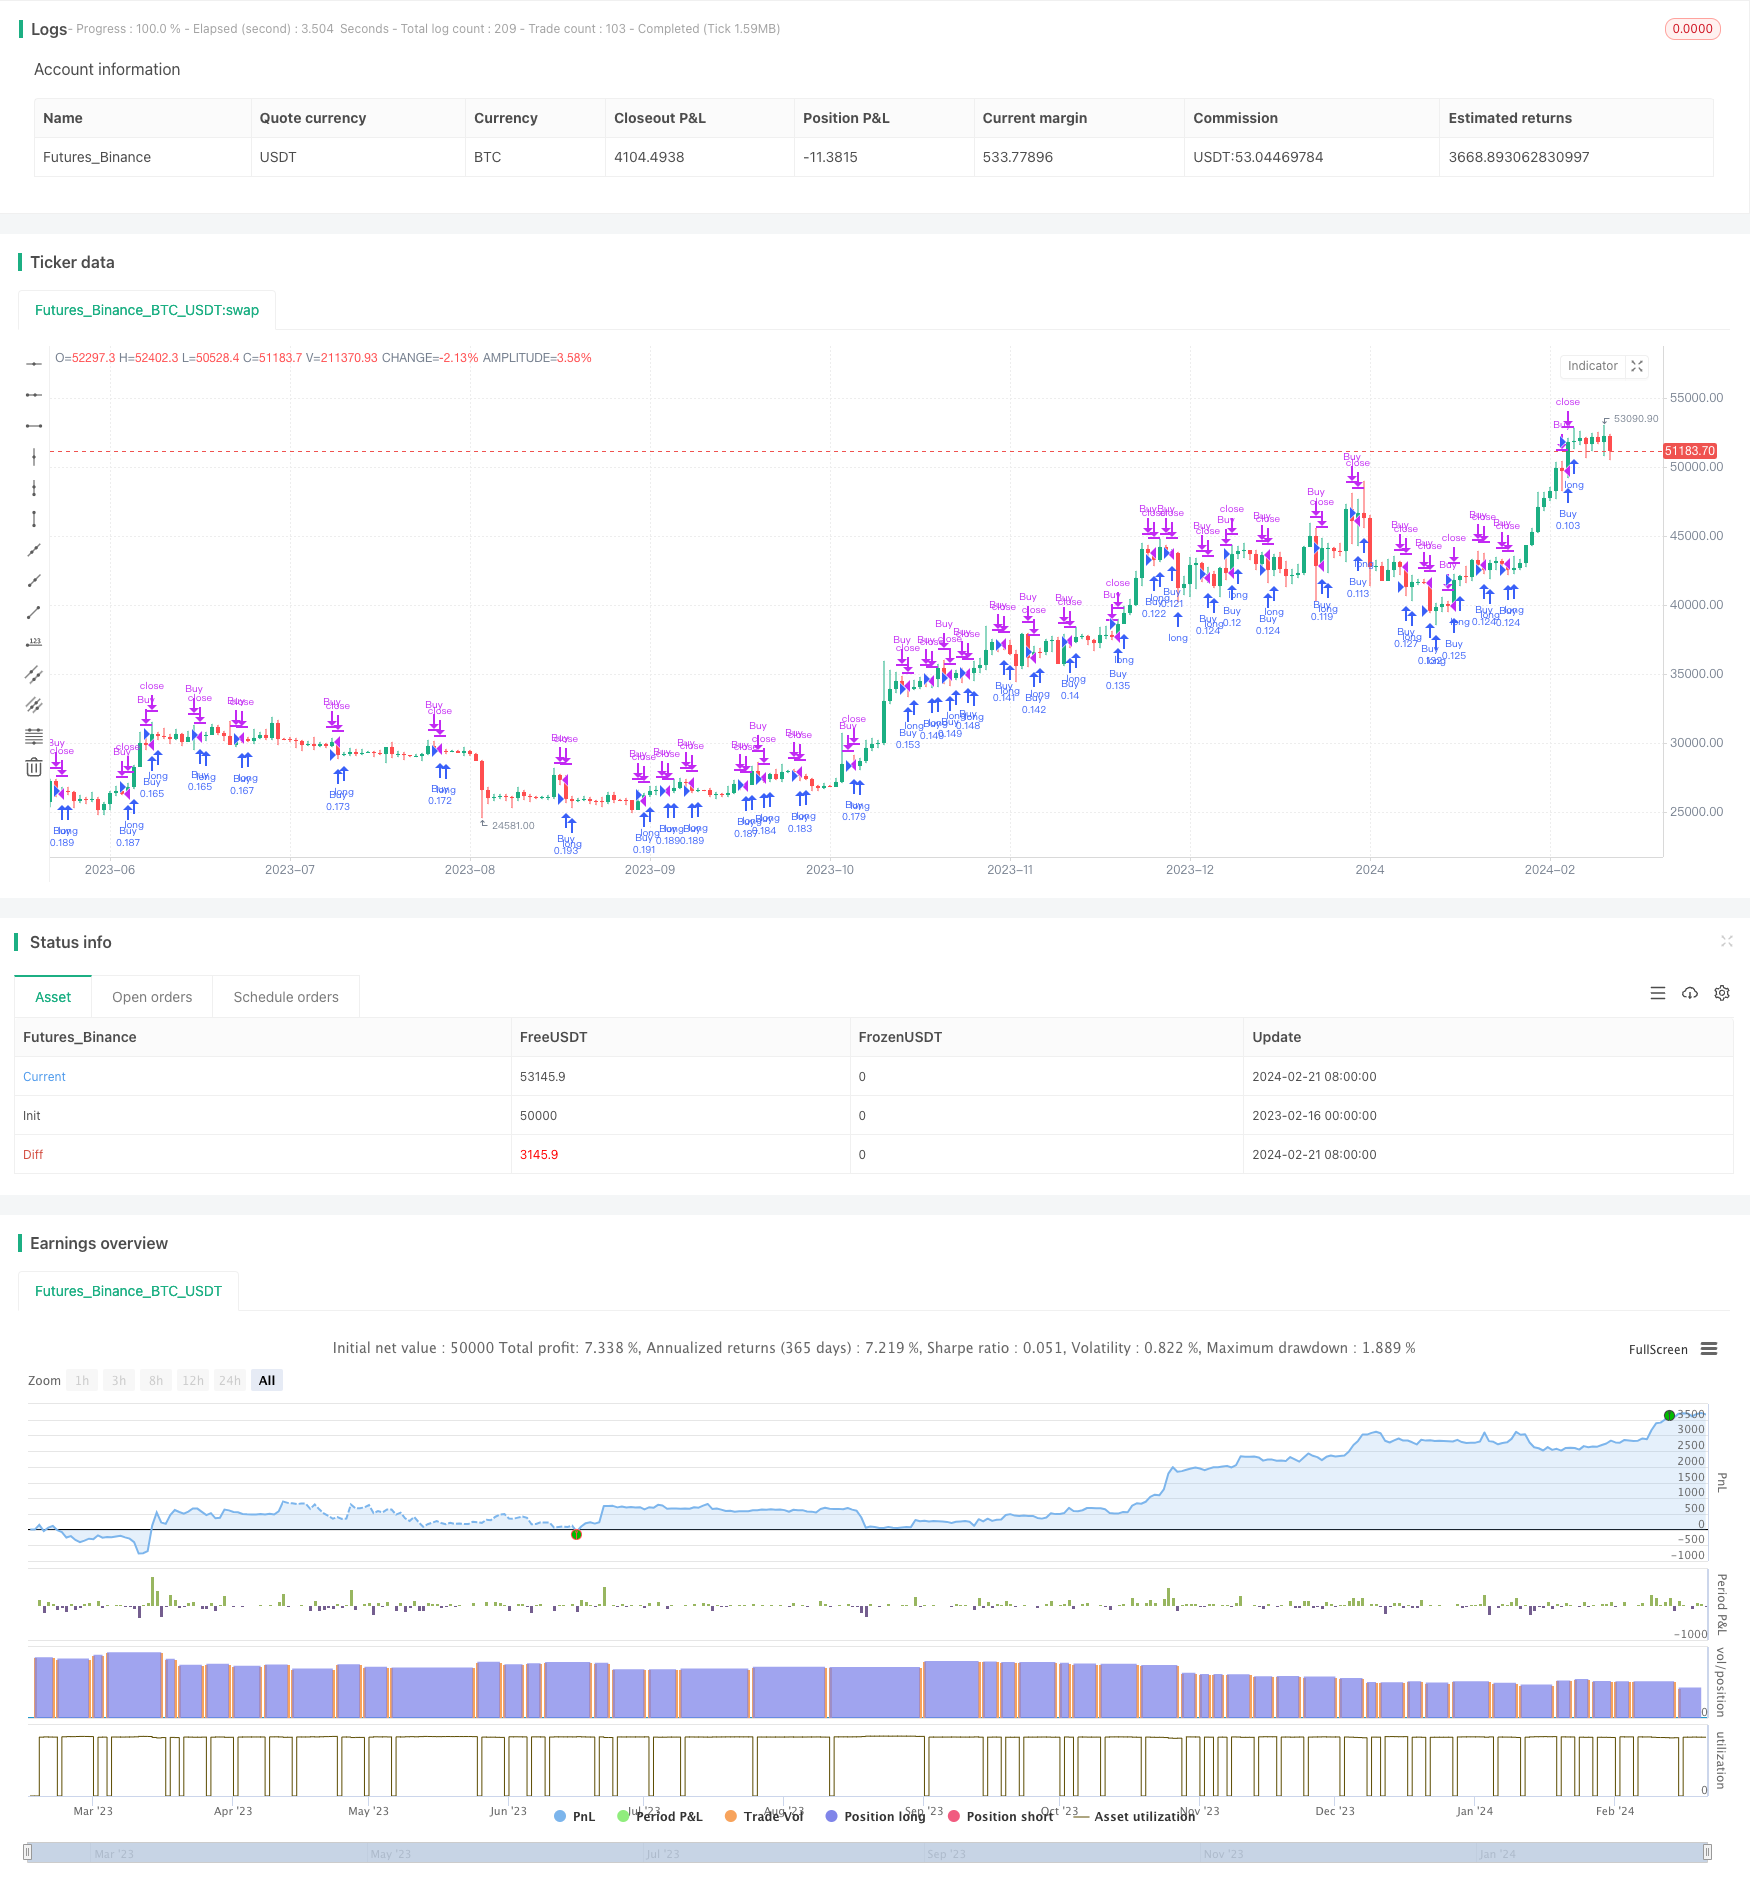
Overview
This strategy combines Dollar Cost Averaging (DCA) with the trailing take profit feature available on exchange platforms. It sets a 1% price deviation for purchases and targets 0.5% profit on each sale. The rationale for targeting small profits is to ensure smooth operations for the trading bot, avoiding getting stuck during slow market periods. Based on backtesting, this bot has proven to be adaptable enough to withstand market fluctuations and manipulation. While the Annual Percentage Rate (APR) may not be exceptionally high, it offers a satisfactory and secure option for long-term investment, often outperforming the traditional buy and hold (HODL) strategy.
Principles
The strategy first sets configurable parameters like trailing stop percentage, max DCA orders, price deviation percentage, etc. It then tracks variables like last buy price, number of buys, initial buy price, trailing stop price, etc. On the buy logic, if the current price is below the last buy price * (1 - price deviation percentage) and the number of buys has not reached max DCA orders, it will issue a buy signal and record the buy price. On the sell logic, if the current price is above the last buy price * (1 + take profit percentage), it will set a trailing stop price. If the price continues to rise above that trailing stop price, the trailing stop is updated to current price * (1 - trailing percentage). If the price drops below the trailing stop price, a sell signal is issued while resetting relevant variables, getting ready for the next round of DCA buys.
Advantages
Combines DCA and trailing stop loss to ensure cost averaging while locking in partial profits to avoid drawdowns.
Flexible trailing stop mechanism with adjustable profit taking and trailing percentage to minimize risk.
Backtested results outperform buying and holding, with steady annualized returns suitable for long-term investments.
Simple to implement with adjustable parameters for easy application across major exchange platforms.
Risks
Limited number of DCA buys means losses can compound if market trends down for extended periods.
Poor trailing stop loss settings may lead to premature profit taking or runaway losses.
Trading costs can eat into profits. High trailing stop loss settings increase number of trades.
Requires sufficient capital to support frequent DCA buys. Insufficient initial capital limits number of buys.
Enhancements
Implement adaptive trailing stops, lowering trailing percentage as certain profit milestones are reached.
Incorporate moving averages, increasing buy amounts around key support areas.
Add rebalancing mechanism to adjust DCA amounts based on total assets.
Optimize parameter settings and test profitability across various holding periods.
Conclusion
This strategy combines DCA and trailing stops for steady algorithmic trading returns over long periods. Backtested results are strong and suitable for investors focused on stable growth. Simple and clean code makes it easy to understand and implement. Further performance gains can be achieved through parameter optimization and incorporating additional indicators. Overall it provides investors with a relatively safe and consistent quantified trading solution.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_float_1 | 0.6 | Take Profit (%) |
| v_input_float_2 | 0.1 | Trailing Stop (%) |
| v_input_int_1 | 10 | Max DCA Orders |
| v_input_float_3 | true | Price Deviation (%) |
Source Pine Script
/*backtest
start: 2023-02-16 00:00:00
end: 2024-02-22 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This Pine Script™ code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © Stavolt

//@version=5
strategy("DCA Strategy with Trailing Take Profit", overlay=true, initial_capital=1000, default_qty_type=strategy.percent_of_equity, default_qty_value=10)

// Correctly using input to define user-configurable parameters
takeProfitPercent = input.float(0.6, title="Take Profit (%)", minval=0.1, maxval=5)
trailingPercent = input.float(0.1, title="Trailing Stop (%)", minval=0.05, maxval=1)
maxDCAOrders = input.int(10, title="Max DCA Orders", minval=1, maxval=20)
priceDeviationPercent = input.float(1.0, title="Price Deviation (%)", minval=0.5, maxval=5)

var float lastBuyPrice = na
var int buyCount = 0
var float initialBuyPrice = na
var float trailingStopPrice = na

// Strategy logic here...
// Note: The detailed logic for buying and selling based on the DCA strategy
// needs to be tailored to your specific requirements and tested for correctness.

if (buyCount < maxDCAOrders)
    if (na(lastBuyPrice) or close < lastBuyPrice * (1 - priceDeviationPercent / 100))
        strategy.entry("Buy", strategy.long)
        lastBuyPrice := close
        buyCount += 1
        if (na(initialBuyPrice))
            initialBuyPrice := close

if (not na(lastBuyPrice) and close > lastBuyPrice * (1 + takeProfitPercent / 100))
    if (na(trailingStopPrice) or close > trailingStopPrice)
        trailingStopPrice := close * (1 - trailingPercent / 100)
    if (close < trailingStopPrice)
        strategy.close("Buy")
        lastBuyPrice := na
        trailingStopPrice := na
        buyCount := 0
        initialBuyPrice := na
Published by ChaoZhang on the FMZ strategy square · last modified 2024-02-23. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/DCA-Strategy-with-Trailing-Take-Profit.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Dollar Cost Averaging Investment StrategyPine Script · DCA & fixed investment · 1d
- Dynamic DCA based Cryptocurrency Quantitative Trading StrategyPine Script · DCA & fixed investment · 1h
- Dynamic Position Building StrategyPine Script · DCA & fixed investment · 1h
- Fibonacci Zone DCA StrategyPine Script · DCA & fixed investment · 1d
- Multi Indicator Confirmation EMA Breakout with DCA and Dynamic Take Profit StrategyPine Script · DCA & fixed investment · 1d
- Bollinger Band and RSI Mixing with DCA StrategyPine Script · DCA & fixed investment · 1d