Donchian Channel With Trailing Stop Loss Strategy
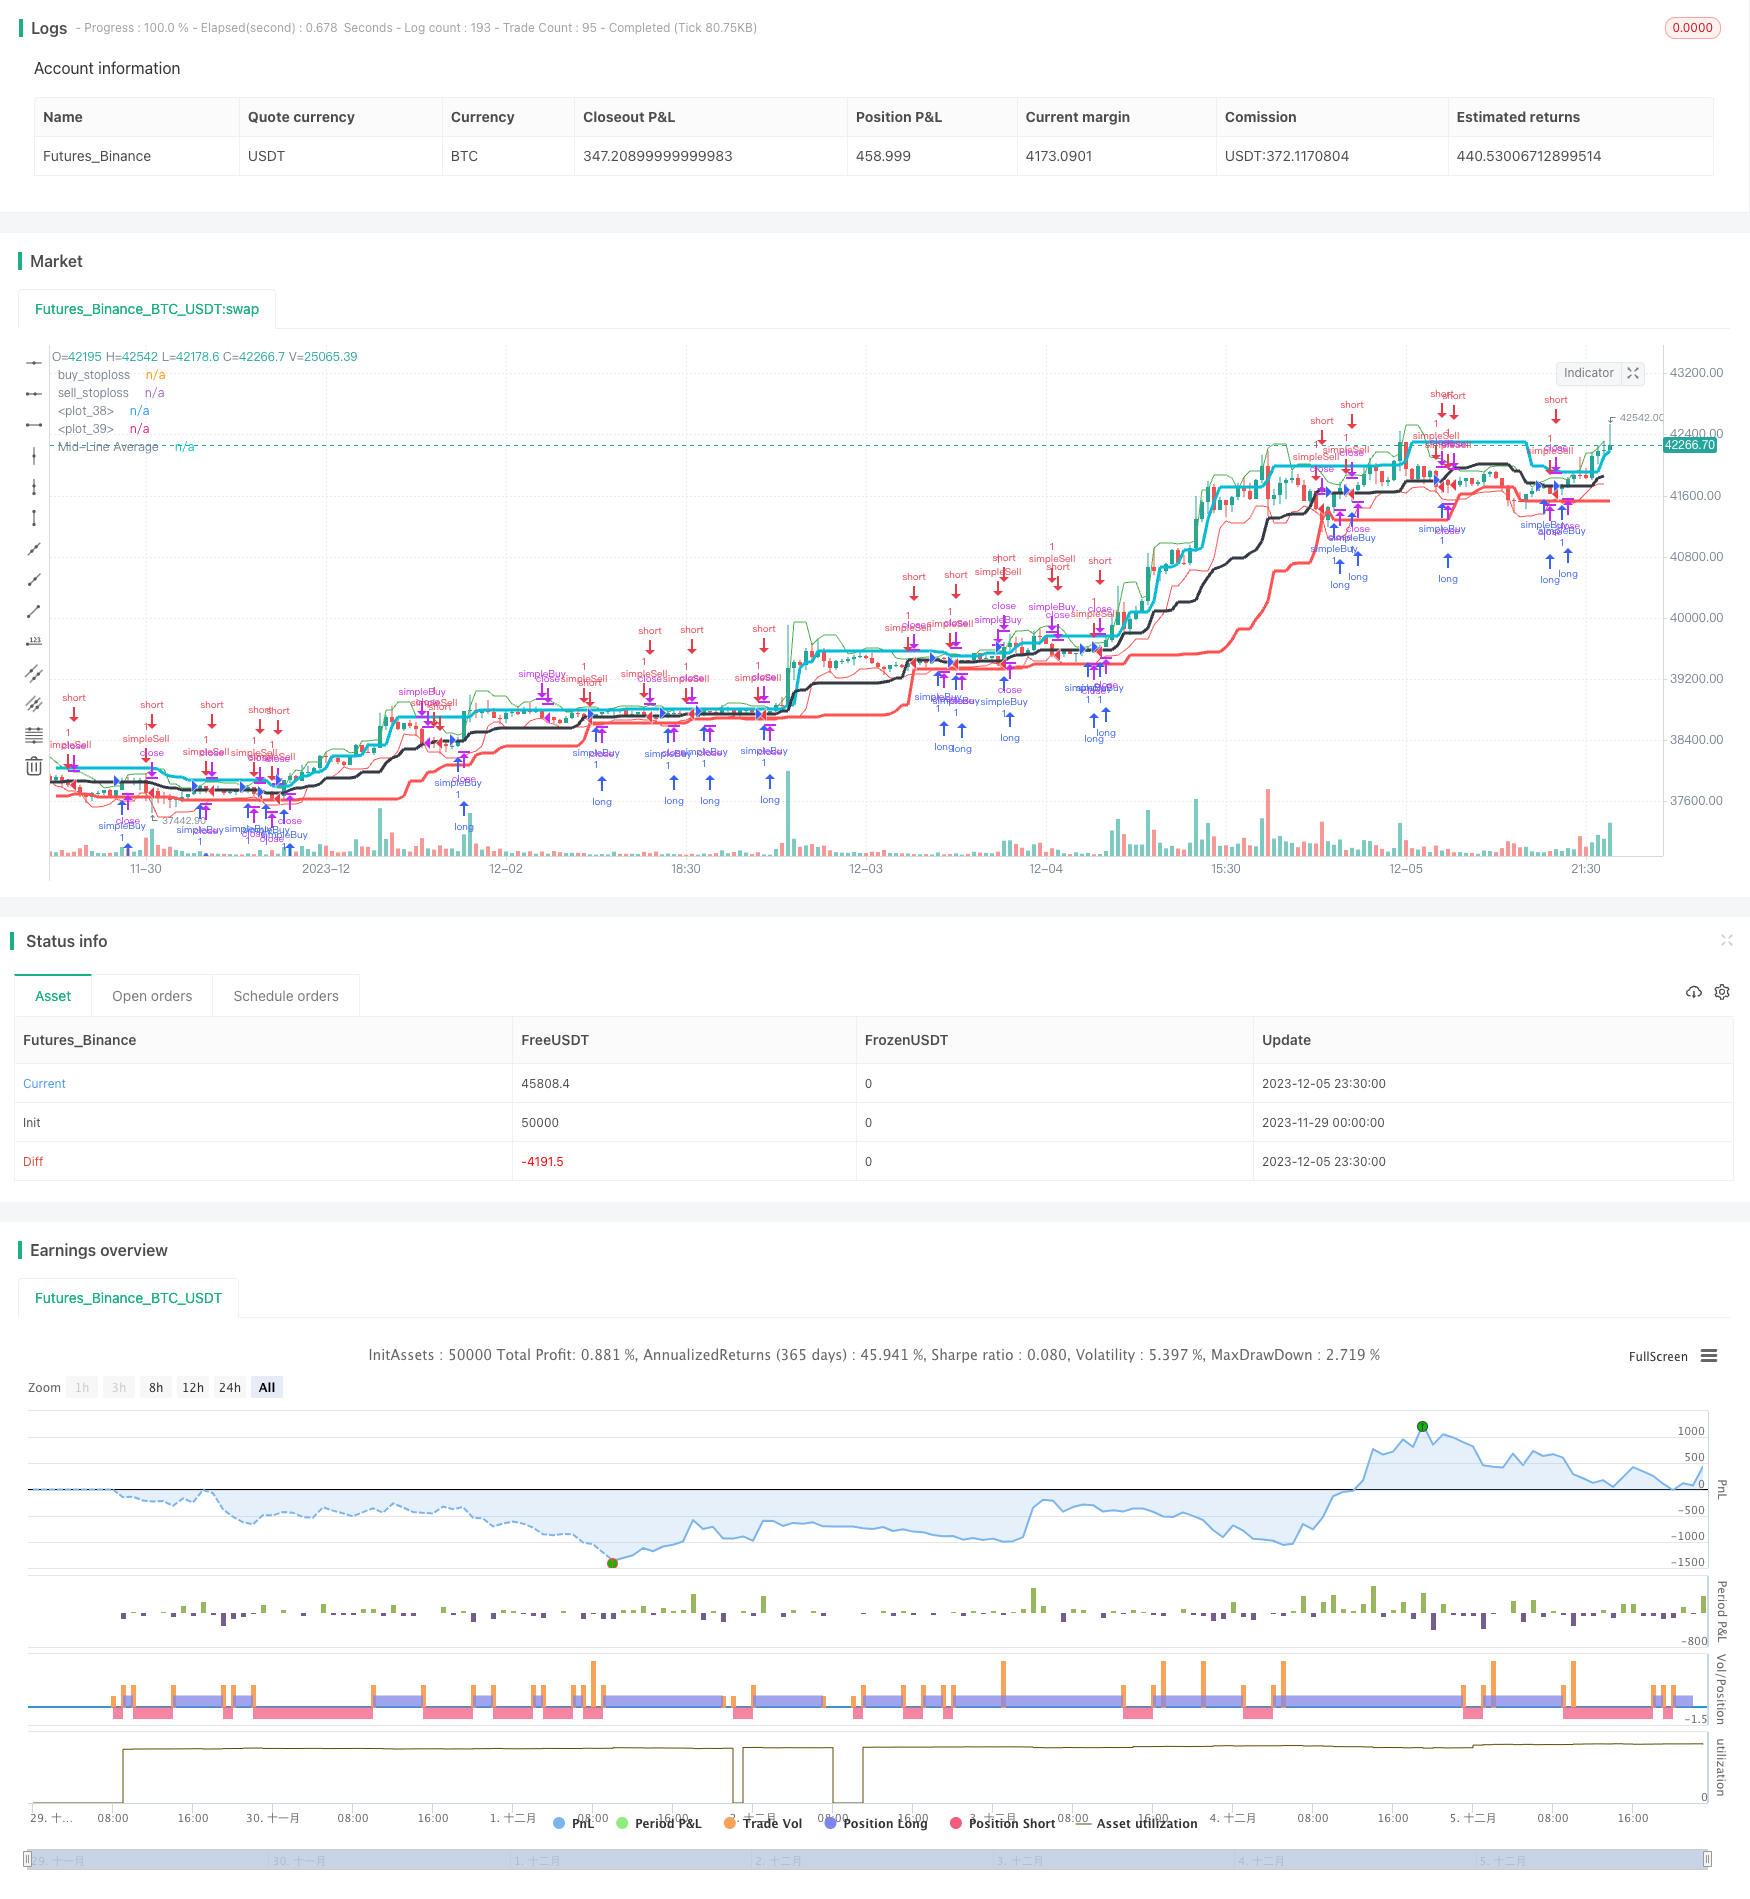
This is a trend following strategy based on the Donchian Channel indicator, combined with dynamic stop loss based on the ATR indicator to lock in profits. It belongs to the trend following strategy category.
Overview
This is a trend following strategy based on the Donchian Channel indicator, combined with dynamic stop loss based on the ATR indicator to lock in profits. It belongs to the trend following strategy category.
Strategy Logic
The strategy uses a 20-period Donchian Channel, where the channel midline is the average of the highest high and lowest low. It goes long when price crosses above the channel midline and goes short when price crosses below the midline. The exit rule is when price touches the dynamic stop loss line, which is calculated as the lowest low of the recent 3 bars minus one third of the ATR value for long positions, and highest high of recent 3 bars plus one third of the ATR value for short positions.
Advantage Analysis
The main advantages of this strategy are:
- Donchian Channel is effective in identifying market trend directions and catching trends.
- The dynamic trailing stop loss based on ATR locks in profits while controlling risks.
- Incorporating ATR factor into stop loss calculation takes market volatility into consideration, making the stop more reasonable.
- The stop loss calculation method is stable and reliable, avoiding stops being too close and getting stopped out prematurely.
Risk Analysis
The main risks of this strategy include:
- Donchian Channel has some lagging effect, which may miss short-term opportunities.
- Improper ATR parameter setting may lead to stop loss being too wide or too close.
- Trend determination mechanism is relatively simple, which may generate more false signals during market consolidations.
- Lack of effective support/resistance judgment, resulting in improper market entry timing.
Optimization Directions
Some optimization directions for this strategy:
- Add other indicators to avoid frequent trading when there is no clear trend.
- Add support/resistance judgment to optimize entry timing.
- Test other dynamic stop loss calculation methods to further optimize the stop loss strategy.
- Test the effects of different Donchian Channel period parameters on strategy performance.
- Add filters on volume or increments to reduce false signals.
Conclusion
In summary, this is a simple and practical trend following strategy. It identifies trend direction via Donchian Channel and locks in profits with dynamic trailing stop loss, which can effectively follow trends. The strategy is quite practical to use, but can be further optimized in various ways for better performance in more complex market environments.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 20 | ATR Length: |
| v_input_2 | 2017 | Backtest Start Year |
| v_input_3 | true | Backtest Start Month |
| v_input_4 | true | Backtest Start Day |
| v_input_5 | 2018 | Backtest Start Year |
| v_input_6 | 12 | testEndMonth |
| v_input_7 | 31 | Backtest Start Day |
| v_input_8 | 20 | Period |
Source Pine Script
/*backtest
start: 2023-11-29 00:00:00
end: 2023-12-06 00:00:00
period: 30m
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4
strategy(title = "dc",  overlay = true)
atrLength = input(title="ATR Length:", defval=20, minval=1)

testStartYear = input(2017, "Backtest Start Year")
testStartMonth = input(1, "Backtest Start Month")
testStartDay = input(1, "Backtest Start Day")
testPeriodStart = timestamp(testStartYear,testStartMonth,testStartDay,0,0)

testEndYear = input(2018, "Backtest Start Year")
testEndMonth = input(12)
testEndDay = input(31, "Backtest Start Day")
testPeriodEnd = timestamp(testEndYear,testEndMonth,testEndDay,0,0)


testPeriod() =>
    true
    //time >= testPeriodStart  ? true : false

dcPeriod = input(20, "Period")

dcUpper = highest(close, dcPeriod)[1]
dcLower = lowest(close, dcPeriod)[1]
dcAverage = (dcUpper + dcLower) / 2
atrValue=atr(atrLength)


useTakeProfit   = na
useStopLoss     = na
useTrailStop    = na
useTrailOffset  = na
//@version=1
Buy_stop = lowest(low[1],3) - atr(20)[1] / 3
plot(Buy_stop, color=red, title="buy_stoploss")
Sell_stop = highest(high[1],3) + atr(20)[1] / 3
plot(Sell_stop, color=green, title="sell_stoploss")

plot(dcLower, style=line, linewidth=3, color=red, offset=1)
plot(dcUpper, style=line, linewidth=3, color=aqua, offset=1)

plot(dcAverage, color=black, style=line, linewidth=3, title="Mid-Line Average")

strategy.entry("simpleBuy", strategy.long, when=(close > dcAverage) and cross(close,dcAverage))
strategy.close("simpleBuy",when= ( close< Buy_stop))

strategy.entry("simpleSell", strategy.short,when=(close < dcAverage) and cross(close,dcAverage) )
strategy.close("simpleSell",when=( close > Sell_stop))

//strategy.exit("Exit simpleBuy", from_entry = "simpleBuy", profit = useTakeProfit, loss = useStopLoss, trail_points = useTrailStop, trail_offset = useTrailOffset)
//strategy.exit("Exit simpleSell", from_entry = "simpleSell", profit = useTakeProfit, loss = useStopLoss, trail_points = useTrailStop, trail_offset = useTrailOffset)
Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-07. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Donchian-Channel-With-Trailing-Stop-Loss-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Momentum Breakout Trading Strategy 435896Pine Script · Breakout · 1d
- Breakout Strategy Based on Turtle TradingPine Script · Breakout · 1d
- Donchian Channel Breakout Strategy 442842Pine Script · Breakout · 4h
- Donchian Channel Breakout StrategyPine Script · Breakout · 4h
- Donchian Channel Trend Following StrategyPine Script · Breakout · 1h
- Donchian Channel and Larry Williams Large Trade Index StrategyPine Script · Breakout · 1m