Strategy vault / Trend following
Double Exponential Moving Average and ALMA Strategy
This strategy combines double exponential moving average and ALMA indicator to achieve trend following and entry. ALMA line serves as the main trend filter, going long when price is above ALMA line and going short…
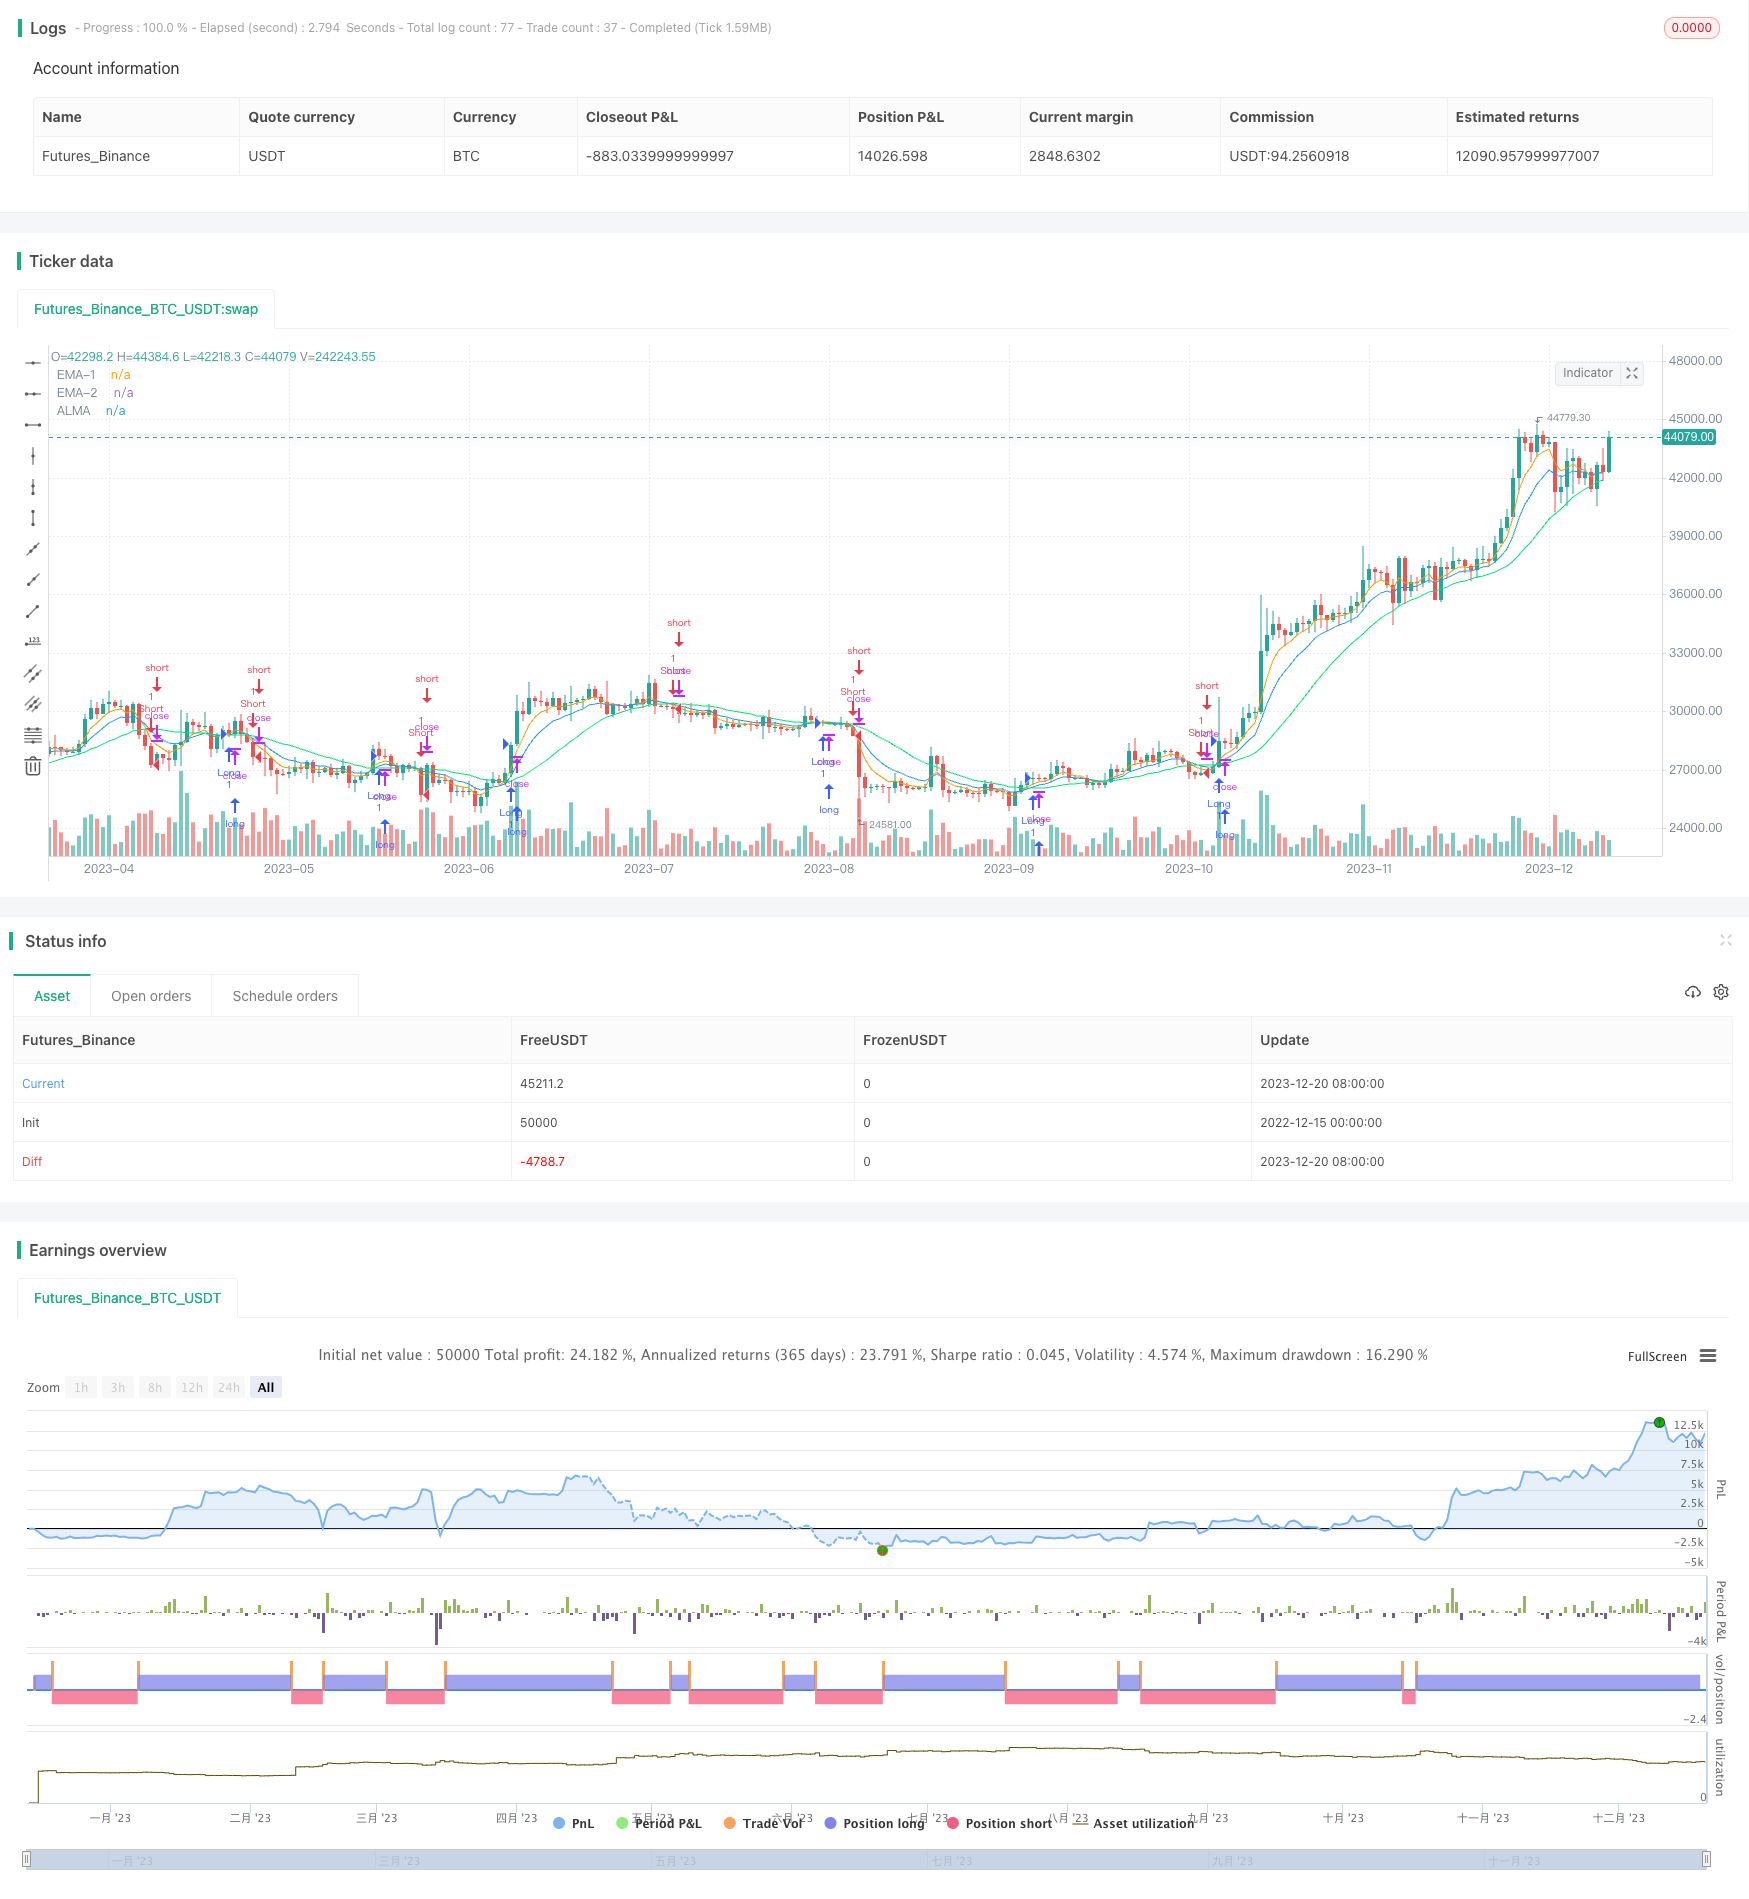
Overview
This strategy combines double exponential moving average and ALMA indicator to achieve trend following and entry. ALMA line serves as the main trend filter, going long when price is above ALMA line and going short when price is below ALMA line. Double EMA is used to give early trend signals for timely entry.
Strategy Logic
- Calculate fast EMA1 and slow EMA2 of double exponential moving average.
- Calculate ALMA line.
- When EMA1 and EMA2 form golden cross, go long if price is above ALMA line; when EMA1 and EMA2 form dead cross, go short if price is below ALMA line.
- So ALMA line serves as the main filter to avoid whipsaws during ranging market. And double EMA gives early trend signals for timely entry.
Advantage Analysis
- Double EMA can reflect price trend ahead of time, avoiding entering ranging zone.
- ALMA line can dynamically capture trends with adaptive smoothness, which is a great trend filtering indicator.
- The combination considers both timeliness of trend and reliability of entry.
Risk Analysis
- Double EMA may give false signals during violent price fluctuations.
- ALMA line has the issue of lagging behind prices, resulting in some trends being filtered out.
- Inappropriate parameter settings can also lead to poor strategy performance.
Solutions:
- Adjust periods of double EMA properly to reduce false signals.
- Tune parameters of ALMA line to decrease lagging.
- Do parameter optimization to find the best parameter combination.
Optimization Directions
- Test double EMA with different period combinations to find the optimal parameters.
- Test ALMA line with different window size, offset and sigma values for parameter optimization.
- Incorporate other indicators like volatility index for further signal filtering.
- Optimize stop loss strategy to control single trade loss.
Conclusion
This strategy combines double EMA and ALMA indicator to achieve timely trend following and reliable entry filtering. By improving parameter optimization and stop loss strategy, it can further reduce false signals, control risks and improve strategy performance. It is suitable for trending markets and medium-long term trading especially.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 50 | Window Size |
| v_input_2 | 0.85 | Offset |
| v_input_3 | 6 | Sigma |
| v_input_4 | 5 | EMA-1 |
| v_input_5 | 10 | EMA-2 |
Source Pine Script
/*backtest
start: 2022-12-15 00:00:00
end: 2023-12-21 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=3
//Author: HighProfit

//Lead-In
strategy("Double Exponential Moving Avarage & Arnoud Legoux Moving Avarage Strategy", shorttitle="ST-DEMA+ALMA", overlay=true)

//Arnoud Legoux Moving Avarage Inputs
source = close
windowsize = input(title="Window Size", defval=50)
offset = input(title="Offset", type=float, defval=0.85)
sigma = input(title="Sigma", type=float, defval=6)

//Exponential Moving Avarage Inputs
L1= input(5,"EMA-1")
L2= input(10,"EMA-2")

//Exponential Moving Avarage Calculations
e1= ema(close, L1)
e2= ema(close, L2)

//Conditions
longCondition = e1 and e2 > alma(source, windowsize, offset, sigma)
if (longCondition)
    strategy.entry("Long", strategy.long)

shortCondition = e1 and e2 < alma(source, windowsize, offset, sigma)
if (shortCondition)
    strategy.entry("Short", strategy.short)

//Plots
plot(alma(source, windowsize, offset, sigma), color=lime, linewidth=1, title="ALMA")
plot(e1, color=orange, linewidth=1, title="EMA-1")
plot(e2, color=blue, linewidth=1, title="EMA-2")
Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-22. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Double-Exponential-Moving-Average-and-ALMA-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- 200 EMA VWAP MFI Trend Following StrategyPine Script · Trend following · 1d
- 4 EMA Trend StrategyPine Script · Trend following · 1d
- ADX MA and EMA Long Only Trend Tracking StrategyPine Script · Trend following · 1d
- ATR Dynamic Trend Following and EMA Crossover Trading StrategyPine Script · Trend following · 1d
- ATR and Moving Average Crossover Hybrid StrategyPine Script · Trend following · 1h
- ATR and T3 Moving Average StrategyPine Script · Trend following · 5m