Strategy vault / Trend following
Double Moving Average Crossover Trading Strategy 436775
This strategy generates buy and sell signals based on the golden cross and death cross of moving averages. Specifically, it uses a 5-day exponential moving average (EMA) and a 34-day double exponential moving average…
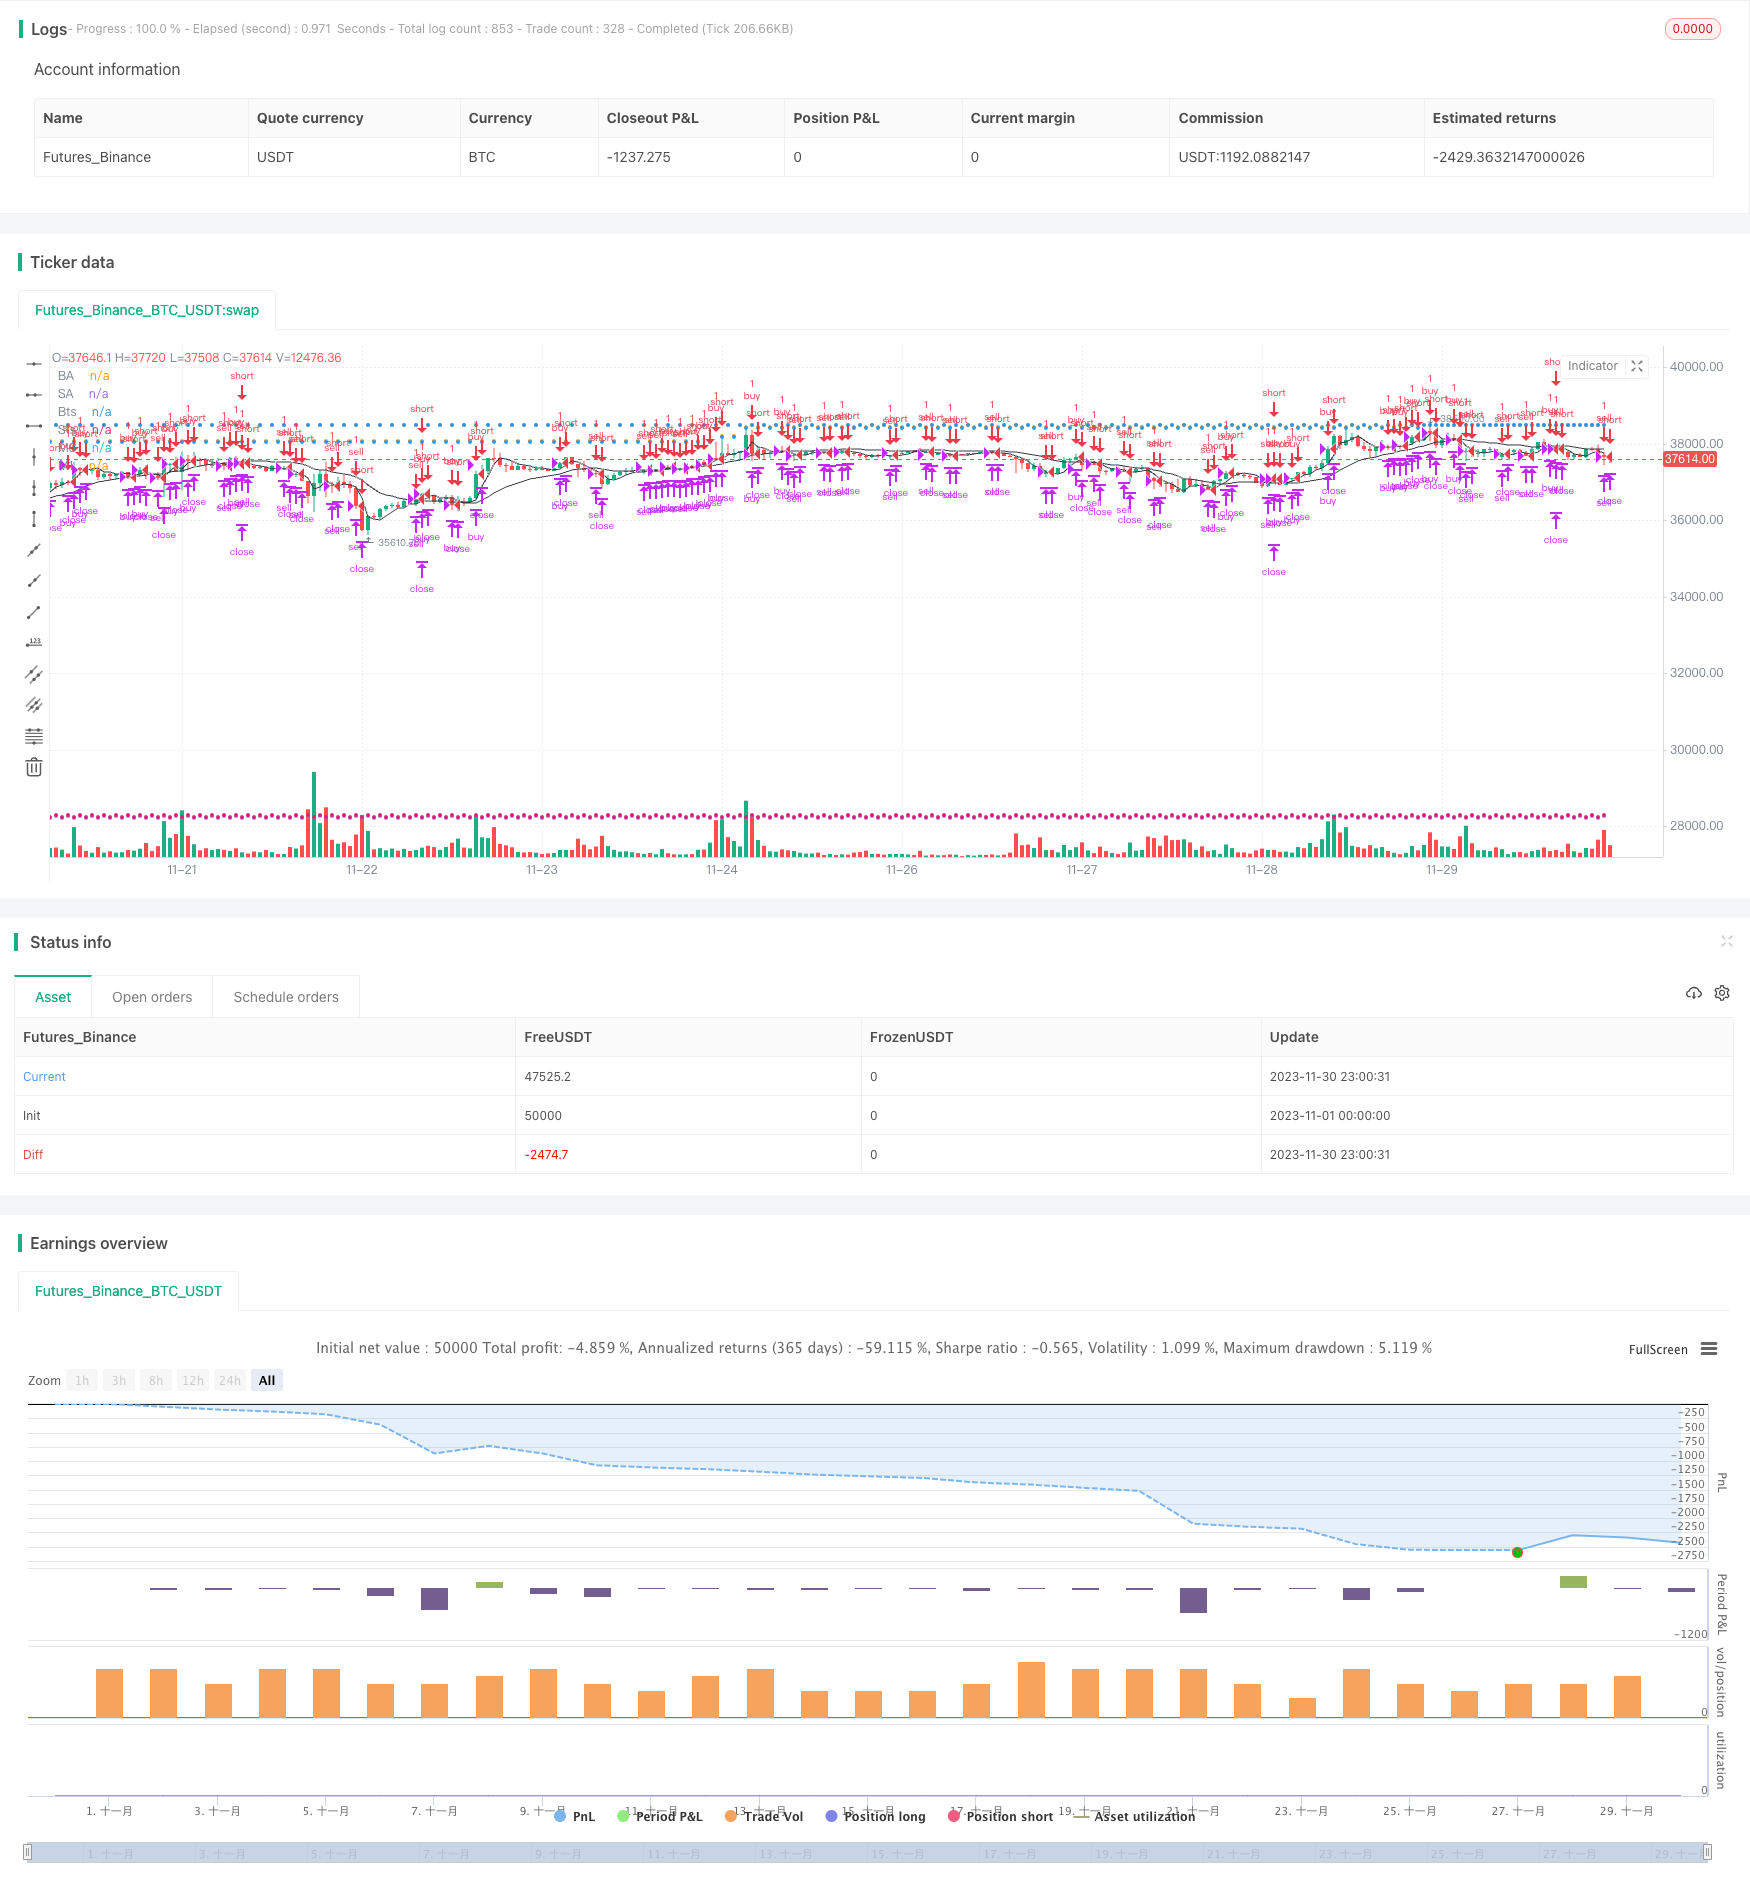
Overview
This strategy generates buy and sell signals based on the golden cross and death cross of moving averages. Specifically, it uses a 5-day exponential moving average (EMA) and a 34-day double exponential moving average (DEMA). When the short-term 5-day EMA crosses above the long-term 34-day DEMA, a buy signal is generated. When the short-term 5-day EMA crosses below the long-term 34-day DEMA, a sell signal is generated.
Strategy Logic
- Calculate the 5-day EMA and 34-day DEMA
- Generate a buy signal when the short-term 5-day EMA crosses above the long-term 34-day DEMA
- Generate a sell signal when the short-term 5-day EMA crosses below the long-term 34-day DEMA
- Option to trade only during specific trading sessions
- Option to use trailing stop loss
This strategy combines both trend following and moving average crossover factors for stable performance. Moving averages as a trend following indicator can effectively identify market trends; The EMA and DEMA combination can effectively smooth price data to generate trading signals; The crossovers between short-term and long-term moving averages can provide early trading signals when major trend changes.
Advantage Analysis
- Simple and clear strategy logic, easy to understand and implement
- Combination use of moving averages considers both trend judgment and price data smoothing
- Crossovers between short-term and long-term moving averages can provide early signals at major turning points
- Parameters can be optimized to adjust moving average lengths for different products and timeframes
- Integrating two factors can improve strategy stability
Risk Analysis
- More false signals may occur in ranging markets
- Inappropriate moving average lengths may cause signal lagging
- Improper trading hours and stop loss settings may affect strategy profitability
These risks can be reduced by adjusting moving average lengths, optimizing trading hours, and setting reasonable stop loss.
Optimization Directions
- Adjust moving average length parameters for different trading products and timeframes
- Optimize trading session parameters to trade during most active periods
- Compare fixed stop loss vs trailing stop loss
- Test impact of different price source options on strategy
Conclusion
This strategy generates trading signals through double moving average crossovers, combined with trend following and data smoothing techniques. It is a simple and practical trend following strategy. Through parameter tuning and logic refinement, it can adapt to different products and timeframes, provide early signals at major trend changes, and avoid false signals. Worth recommending and applying.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | true | Use Trading Session? |
| v_input_2 | true | Use Trailing Stop? |
| v_input_3 | 0400-1500 | Trade Session: |
| v_input_4 | true | Trade Size: |
| v_input_5 | 55 | Take profit in pips: |
| v_input_6 | 22 | Stop loss in pips: |
| v_input_7 | 5 | EMA length: |
| v_input_8 | 34 | DEMA length: |
| v_input_9_open | 0 | Price source:: open | high | low | close | hl2 | hlc3 | hlcc4 | ohlc4 |
Source Pine Script
/*backtest
start: 2023-11-01 00:00:00
end: 2023-11-30 23:59:59
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
args: [["v_input_1",false]]
*/

//@version=2
strategy(title='[STRATEGY][RS]MicuRobert EMA cross V2', shorttitle='S', overlay=true)
USE_TRADESESSION = input(title='Use Trading Session?', type=bool, defval=true)
USE_TRAILINGSTOP = input(title='Use Trailing Stop?', type=bool, defval=true)
trade_session = input(title='Trade Session:',  defval='0400-1500', confirm=false)
istradingsession = not USE_TRADESESSION ? false : not na(time('1', trade_session))
bgcolor(istradingsession?gray:na)
trade_size = input(title='Trade Size:', type=float, defval=1)
tp = input(title='Take profit in pips:', type=float, defval=55.0) * (syminfo.mintick*10)
sl = input(title='Stop loss in pips:', type=float, defval=22.0) * (syminfo.mintick*10)
ma_length00 = input(title='EMA length:', defval=5)
ma_length01 = input(title='DEMA length:',  defval=34)
price = input(title='Price source:', defval=open)

//  ||--- NO LAG EMA, Credit LazyBear:  ---||
f_LB_zlema(_src, _length)=>
    _ema1=ema(_src, _length)
    _ema2=ema(_ema1, _length)
    _d=_ema1-_ema2
    _zlema=_ema1+_d
//  ||-------------------------------------||

ma00 = f_LB_zlema(price, ma_length00)
ma01 = f_LB_zlema(price, ma_length01)
plot(title='M0', series=ma00, color=black)
plot(title='M1', series=ma01, color=black)

isnewbuy = change(strategy.position_size)>0 and change(strategy.opentrades)>0
isnewsel = change(strategy.position_size)<0 and change(strategy.opentrades)>0

buy_entry_price = isnewbuy ? price : buy_entry_price[1]
sel_entry_price = isnewsel ? price : sel_entry_price[1]
plot(title='BE', series=buy_entry_price, style=circles, color=strategy.position_size <= 0 ? na : aqua)
plot(title='SE', series=sel_entry_price, style=circles, color=strategy.position_size >= 0 ? na : aqua)
buy_appex = na(buy_appex[1]) ? price : isnewbuy ? high : high >= buy_appex[1] ? high : buy_appex[1]
sel_appex = na(sel_appex[1]) ? price : isnewsel ? low : low <= sel_appex[1] ? low : sel_appex[1]
plot(title='BA', series=buy_appex, style=circles, color=strategy.position_size <= 0 ? na : teal)
plot(title='SA', series=sel_appex, style=circles, color=strategy.position_size >= 0 ? na : teal)
buy_ts = buy_appex - sl
sel_ts = sel_appex + sl
plot(title='Bts', series=buy_ts, style=circles, color=strategy.position_size <= 0 ? na : red)
plot(title='Sts', series=sel_ts, style=circles, color=strategy.position_size >= 0 ? na : red)

buy_cond1 = crossover(ma00, ma01) and (USE_TRADESESSION ? istradingsession : true)
buy_cond0 = crossover(price, ma00) and ma00 > ma01 and (USE_TRADESESSION ? istradingsession : true)
buy_entry = buy_cond1 or buy_cond0
buy_close = (not USE_TRAILINGSTOP ? low <= buy_entry_price - sl: low <= buy_ts) or high>=buy_entry_price+tp//high>=last_traded_price + tp or low<=last_traded_price - sl //high >= hh or
sel_cond1 = crossunder(ma00, ma01) and (USE_TRADESESSION ? istradingsession : true)
sel_cond0 = crossunder(price, ma00) and ma00 < ma01 and (USE_TRADESESSION ? istradingsession : true)
sel_entry = sel_cond1 or sel_cond0
sel_close = (not USE_TRAILINGSTOP ? high >= sel_entry_price + sl : high >= sel_ts) or low<=sel_entry_price-tp//low<=last_traded_price - tp or high>=last_traded_price + sl //low <= ll or

strategy.entry('buy', long=strategy.long, qty=trade_size, comment='buy', when=buy_entry)
strategy.close('buy', when=buy_close)
strategy.entry('sell', long=strategy.short, qty=trade_size, comment='sell', when=sel_entry)
strategy.close('sell', when=sel_close)Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-27. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Double-Moving-Average-Crossover-Trading-Strategy-436775.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- 200 EMA VWAP MFI Trend Following StrategyPine Script · Trend following · 1d
- 4 EMA Trend StrategyPine Script · Trend following · 1d
- ADX MA and EMA Long Only Trend Tracking StrategyPine Script · Trend following · 1d
- ATR Dynamic Trend Following and EMA Crossover Trading StrategyPine Script · Trend following · 1d
- ATR and Moving Average Crossover Hybrid StrategyPine Script · Trend following · 1h
- ATR and T3 Moving Average StrategyPine Script · Trend following · 5m