Dual Channel Breakout Strategy
The strategy is named after its use of two indicators, Bollinger Bands and Keltner Channels, to generate trading signals. It monitors price breakouts beyond channel boundaries, going long on downside breakouts and…
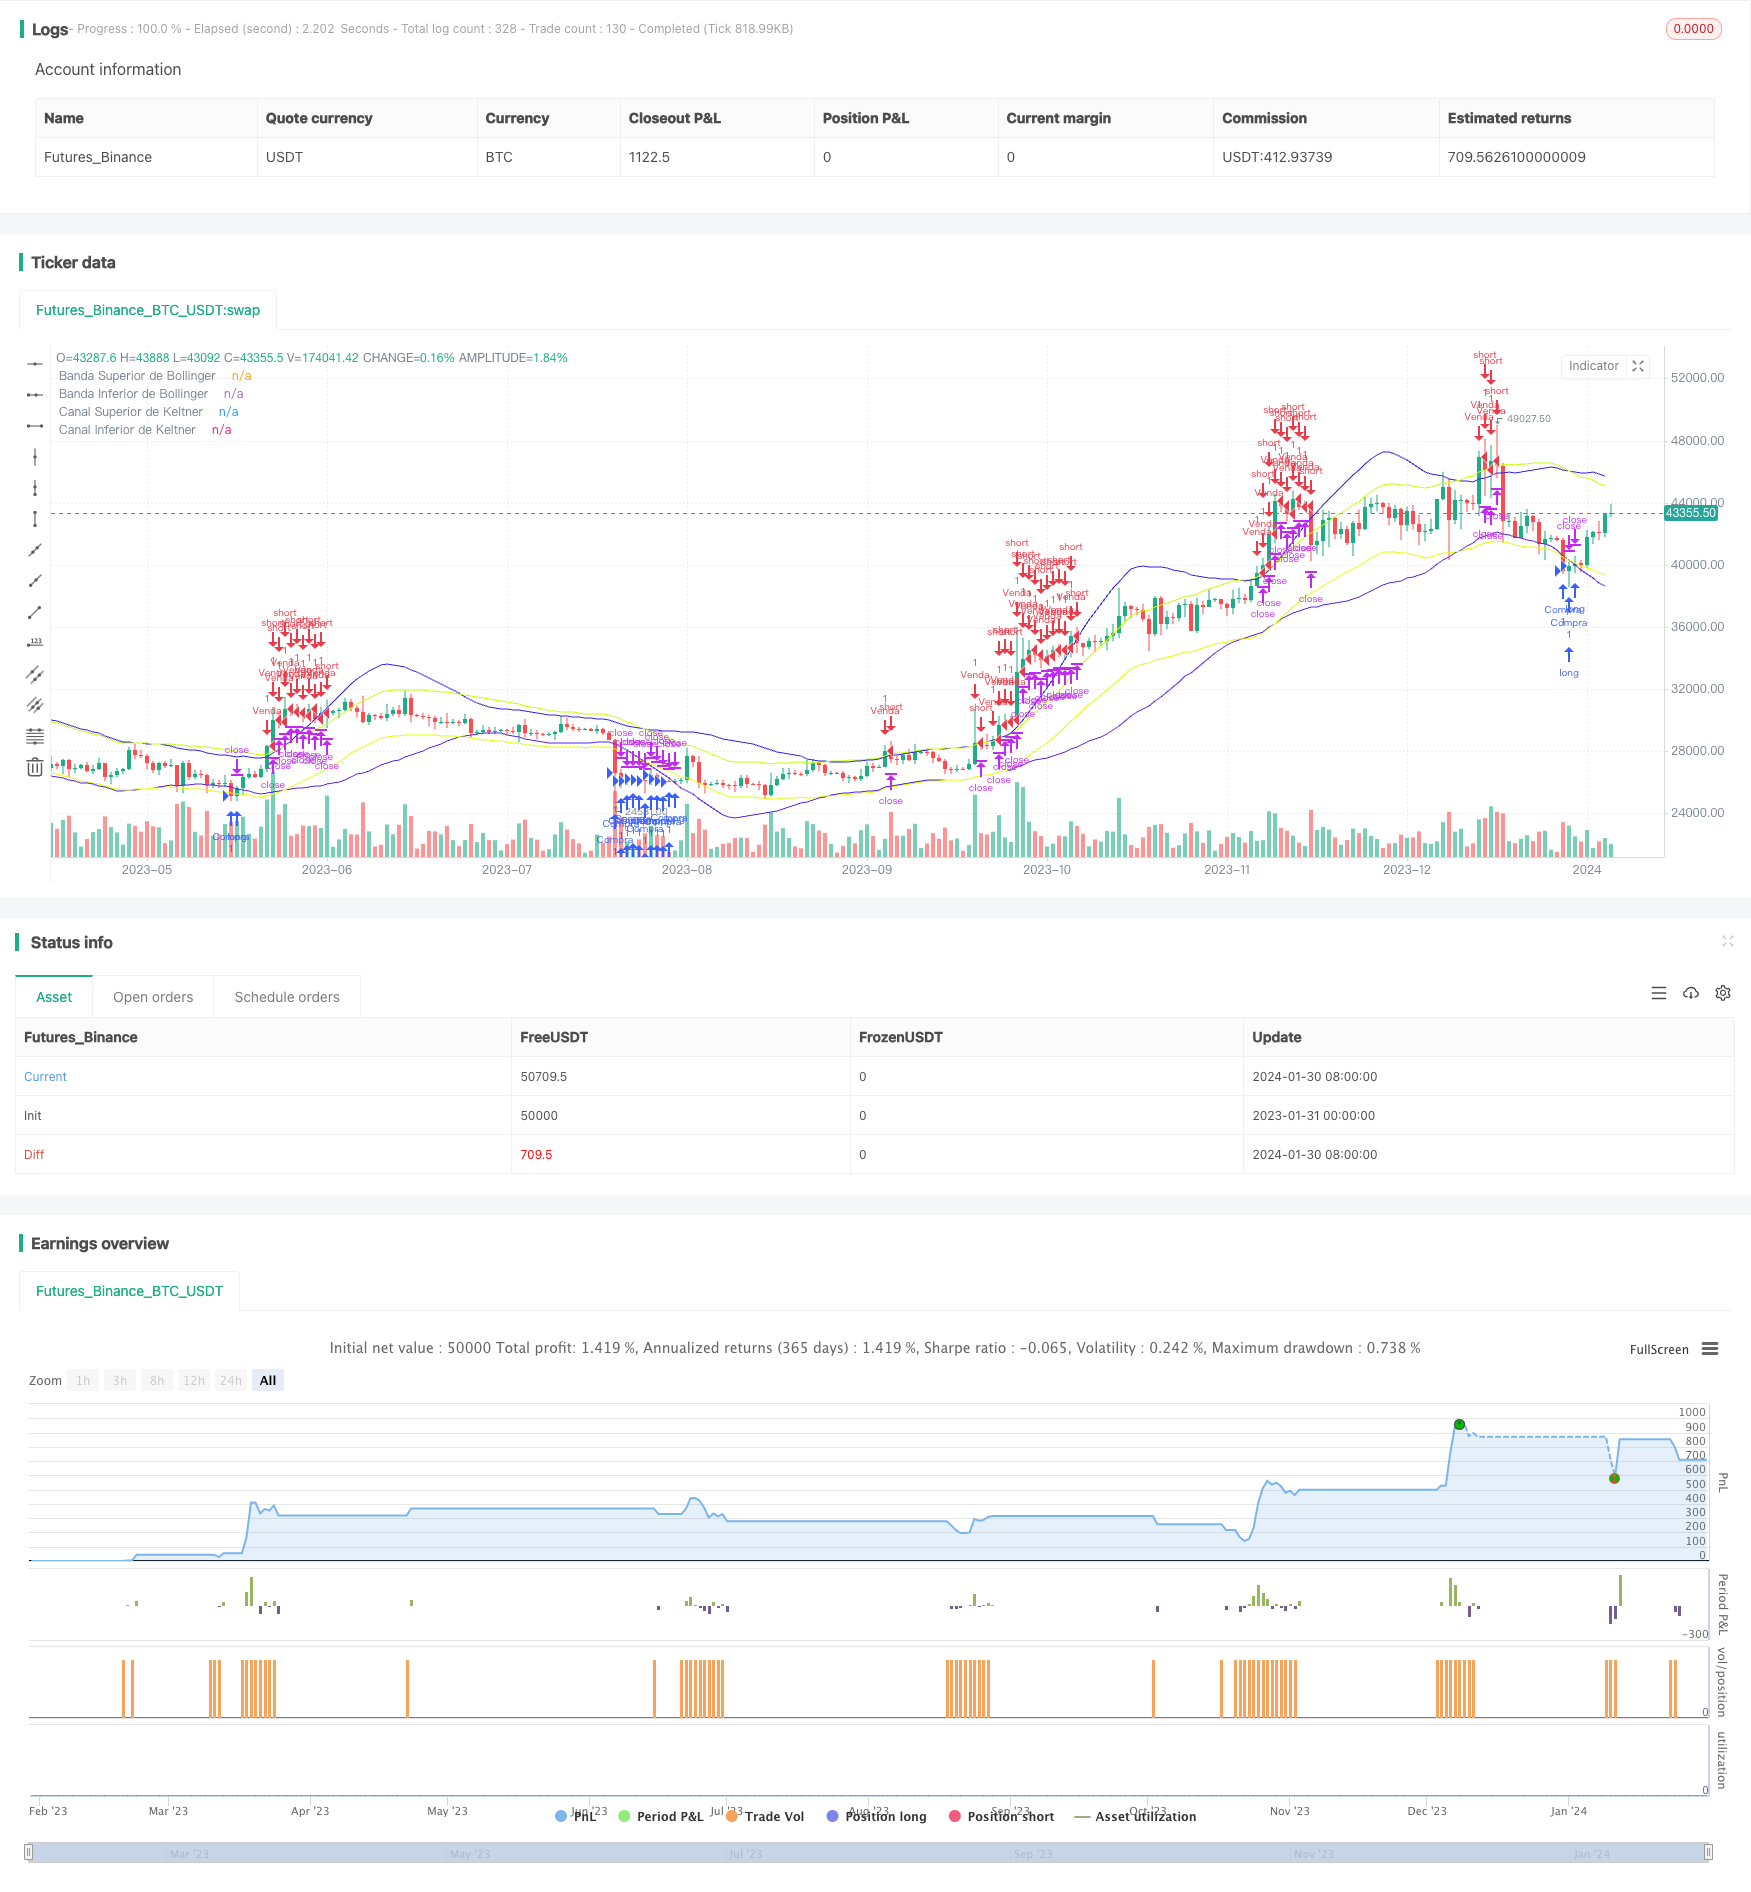
The strategy is named after its use of two indicators, Bollinger Bands and Keltner Channels, to generate trading signals. It monitors price breakouts beyond channel boundaries, going long on downside breakouts and short on upside breakouts.
Strategy Logic
The strategy combines Bollinger Bands and Keltner Channels. Bollinger Bands are adaptive channels plotted at a moving average line plus/minus standard deviations. Keltner Channels use true range to compute channel width.
The trading logic is to go long when the closing price falls below the lower Bollinger Band and lower Keltner Channel, anticipating a reversal. It goes short when the closing price rises above the upper Bollinger and Keltner Channel boundaries. Stops and take profits are set after entry.
Strengths
By combining two channels, the strategy effectively identifies abnormal price swings. The dual channel filters help avoid false signals. The stops and take profits also aid in risk control.
Compared to using just Bollinger Bands or Keltner Channels, this strategy filters out more noise for higher-quality signals. Dual-channel breakouts allow timely entries aiming to capture reversals.
Risk Analysis
A key risk is the lagging nature of channel indicators. Prices could start reversing before hitting the channel boundaries that trigger signals. This may result in late entries or being caught in pullbacks.
Overly tight stops and excessively wide take profits are other risks. These need to be adjusted per market conditions.
Enhancement Opportunities
The strategy can be optimized by adding auxiliary filters like momentum oscillators. Parameter tuning to discover optimal combinations may also help.
Incorporating adaptive stops and take profits is another enhancement route, helping the strategy better adapt to evolving markets.
Conclusion
This dual channel breakout strategy combines the strengths of Bollinger Bands and Keltner Channels to effectively identify reversal opportunities, while controlling risks via dual channel filters and stop/take profit settings. It is a quality, risk-managed quantitative trading strategy.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 20 | Comprimento das Bandas de Bollinger |
| v_input_2 | 2 | Desvio Padrão das Bandas de Bollinger |
| v_input_3 | 20 | Comprimento dos Canais de Keltner |
| v_input_4 | 1.5 | Multiplicador ATR dos Canais de Keltner |
| v_input_5 | 10 | Take Profit (em $) |
| v_input_6 | 20 | Stop Loss (em $) |
Source Pine Script
/*backtest
start: 2023-01-31 00:00:00
end: 2024-01-31 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4
strategy("Estratégia de Compra/Venda BB e KC", overlay=true)

// Parâmetros das Bandas de Bollinger
bollinger_length = input(20, title="Comprimento das Bandas de Bollinger", minval=1)
bollinger_deviation = input(2.0, title="Desvio Padrão das Bandas de Bollinger", minval=0.1)

// Parâmetros dos Canais de Keltner
keltner_length = input(20, title="Comprimento dos Canais de Keltner", minval=1)
atr_multiplier = input(1.5, title="Multiplicador ATR dos Canais de Keltner", minval=0.1)

// Take Profit e Stop Loss em termos financeiros
take_profit = input(10.0, title="Take Profit (em $)", step=1)
stop_loss = input(20.0, title="Stop Loss (em $)", step=1)

// Cálculos das Bandas de Bollinger
basis_bb = sma(close, bollinger_length)
dev_bb = sma(stdev(close, bollinger_length), bollinger_length)
upper_bb = basis_bb + dev_bb * bollinger_deviation
lower_bb = basis_bb - dev_bb * bollinger_deviation

// Cálculos dos Canais de Keltner
basis_kc = sma(close, keltner_length)
atr_kc = sma(atr(keltner_length), keltner_length)
upper_kc = basis_kc + atr_multiplier * atr_kc
lower_kc = basis_kc - atr_multiplier * atr_kc

// Condição de Compra
buy_condition = close < lower_bb and close < lower_kc

// Condição de Venda
sell_condition = close > upper_bb and close > upper_kc

// Estratégia de Compra/Venda com TP e SL
if (buy_condition)
    strategy.entry("Compra", strategy.long)
    strategy.exit("Take Profit/Stop Loss", from_entry="Compra", profit=take_profit, loss=stop_loss)
if (sell_condition)
    strategy.entry("Venda", strategy.short)
    strategy.exit("Take Profit/Stop Loss", from_entry="Venda", profit=take_profit, loss=stop_loss)

// Plot das Bandas de Bollinger e dos Canais de Keltner
plot(upper_bb, color=color.rgb(47, 33, 243), title="Banda Superior de Bollinger")
plot(lower_bb, color=color.rgb(89, 33, 243), title="Banda Inferior de Bollinger")
plot(upper_kc, color=color.rgb(200, 255, 0), title="Canal Superior de Keltner")
plot(lower_kc, color=color.rgb(225, 255, 0), title="Canal Inferior de Keltner")
Published by ChaoZhang on the FMZ strategy square · last modified 2024-02-01. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Dual-Channel-Breakout-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Dual MA Indicator Oscillating Price Tracking StrategyPine Script · Breakout · 2h
- Triple Indicators Sentiment Driven Breakout StrategyPine Script · Breakout · 1h
- Triple Pattern Oscillation Trading StrategyPine Script · Breakout · 1h
- Volatility Squeeze Breakout StrategyPine Script · Breakout · 1h
- BB Breakout StrategyPine Script · Breakout · 1d
- Bollinger Band Breakout Trend Following StrategyPine Script · Breakout · 1d