Strategy vault / Trend following
Dual Direction SMMA Crossover Strategy with ATR Based Risk Management and Fixed Take Profit
This is a dual-direction trend-following strategy based on SMMA (Smoothed Moving Average). The strategy generates long and short signals through price-SMMA crossovers, combining ATR-based dynamic stop-loss and fixed…
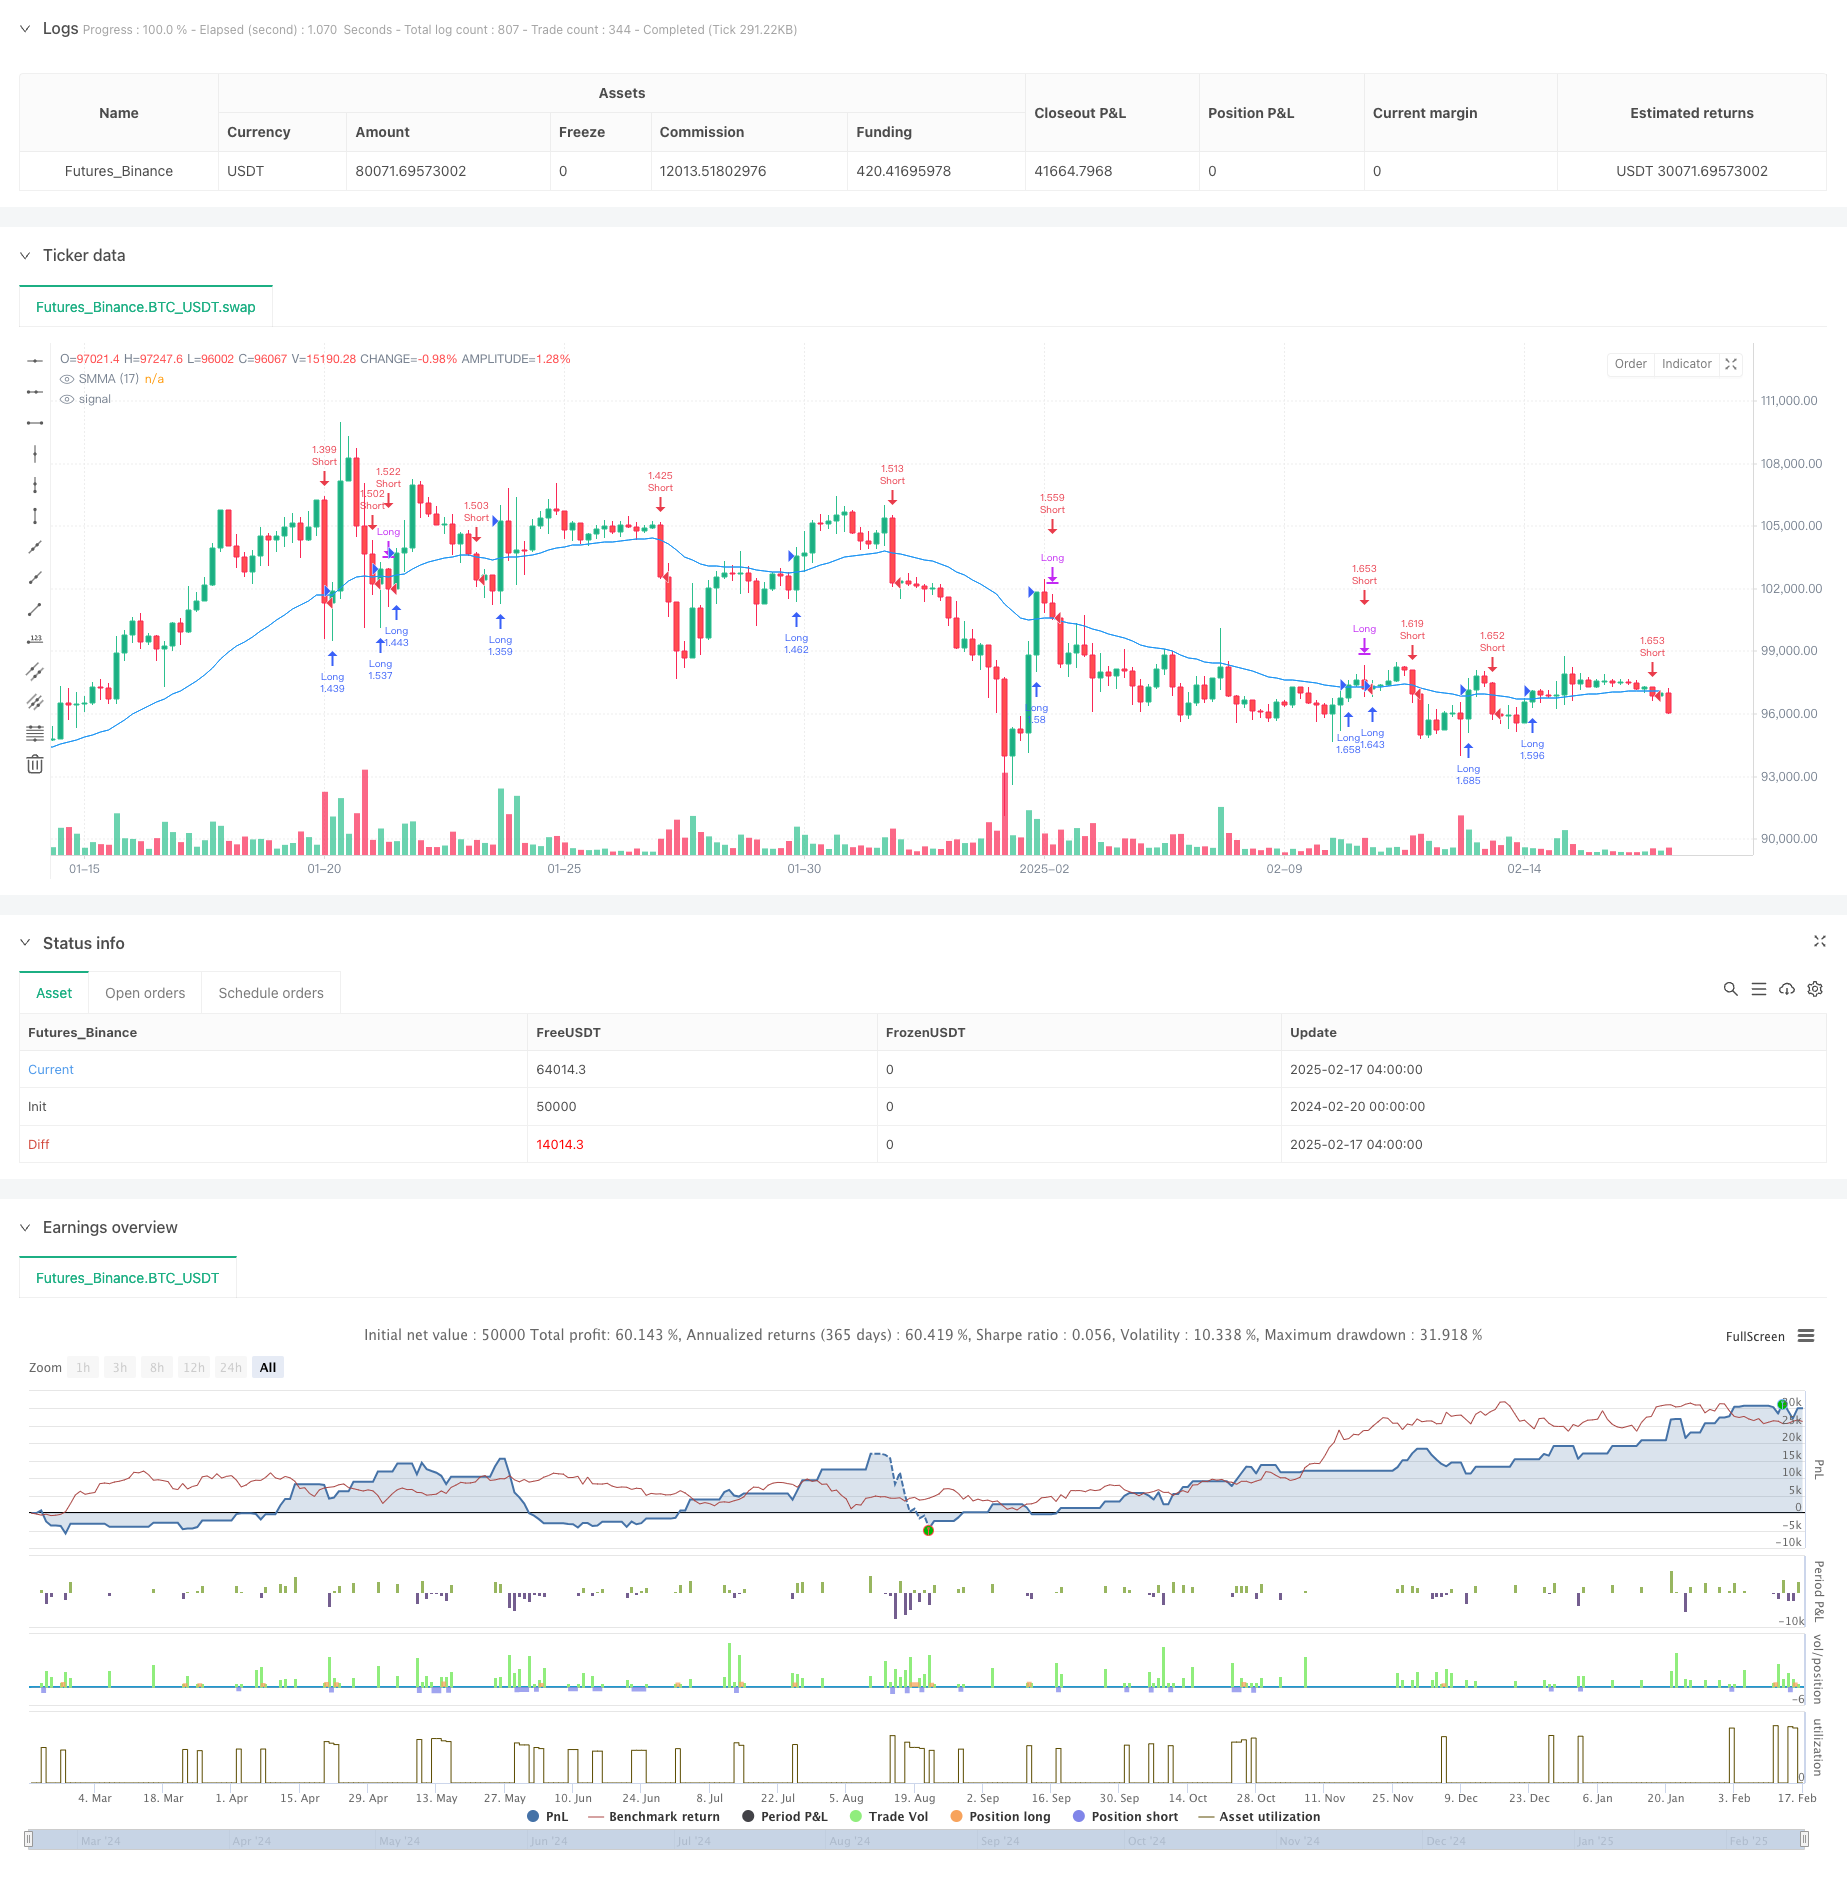
Overview
This is a dual-direction trend-following strategy based on SMMA (Smoothed Moving Average). The strategy generates long and short signals through price-SMMA crossovers, combining ATR-based dynamic stop-loss and fixed take-profit targets for risk and reward management. The strategy design is concise and effective, suitable for trend following across different timeframes.
Strategy Principles
The core mechanism relies on price crossovers with a 17-period SMMA to capture trend changes. Long positions are initiated when price crosses above SMMA, while short positions are taken when price crosses below SMMA. Exit management employs a triple mechanism: 1) ATR-based dynamic stop-loss set at 0.75 times ATR above/below SMMA; 2) Fixed take-profit targets of 1150 points for longs and 1500 points for shorts; 3) Reverse crossover signals for position closure. This combination both protects profits and allows trends to develop fully.
Strategy Advantages
- Stable signal system: SMMA provides smoother signals compared to simple moving averages, effectively reducing false signals
- Comprehensive risk management: Combines ATR-based dynamic stops with fixed profit targets, adapting to market volatility while securing reasonable profits
- Dual-direction trading: Fully captures bilateral market opportunities, improving capital efficiency
- High scalability: Clear strategy framework, easily implementable across different markets and timeframes
- Clear operational rules: Objective entry and exit conditions minimize subjective interference
Strategy Risks
- Choppy market risk: Frequent trades in ranging markets may lead to losses
- Slippage risk: Fixed point profit targets may face slippage in fast markets
- Trend reversal risk: ATR stops may not react quickly enough to sudden trend reversals
- Parameter dependency: Strategy performance heavily relies on SMMA period and ATR multiplier choices
- Money management risk: Fixed percentage position sizing may lack flexibility during volatility changes
Optimization Directions
- Introduce trend strength filtering: Add indicators like ADX to screen for strong trends, reducing false signals in ranging markets
- Dynamic profit targets: Consider using ATR to dynamically adjust profit targets for better market adaptation
- Improved position sizing: Implement volatility-weighted position calculation for optimized capital efficiency
- Multi-timeframe confirmation: Add longer timeframe trend confirmation to improve trade quality
- Market environment adaptation: Include market type classification logic to adjust strategy parameters under different market conditions
Summary
This is a well-designed trend-following strategy that captures trends through SMMA crossovers, implements risk control using ATR, and manages profits with fixed targets. The strategy logic is clear, implementation is straightforward, with good operability and extensibility. While performance may suffer in ranging markets, the suggested optimization directions can further enhance strategy stability and adaptability. For traders who prefer trend following, this represents a noteworthy strategy framework.
Source Pine Script
/*backtest
start: 2024-02-20 00:00:00
end: 2025-02-17 08:00:00
period: 4h
basePeriod: 4h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("SMMA 17 Crossover Strategy (Long & Short, ATR SL & Fixed TP)", overlay=true, default_qty_type=strategy.percent_of_equity, default_qty_value=200)

// ? SMMA Calculation
smmaLength = 17
smma = 0.0
smma := na(smma[1]) ? ta.sma(close, smmaLength) : (smma[1] * (smmaLength - 1) + close) / smmaLength

// ? ATR Calculation (For Dynamic Stop-Loss)
atrLength = 14
atr = ta.rma(ta.tr(true), atrLength)

// ? Long Entry Condition
longCondition = ta.crossover(close, smma)  // ✅ Price crosses above SMMA

// ? Long Exit Condition
longExit = ta.crossunder(close, smma)  // ✅ Price crosses below SMMA

// ? ATR-Based Stop-Loss (Dynamic) for Long
longStopLoss = smma - (atr * 0.75)  // ✅ Stop Loss below SMMA

// ? Fixed Take Profit for Long (1150 Points)
var float longEntryPrice = na
var float longTakeProfit = na
if longCondition
    longEntryPrice := close
    longTakeProfit := longEntryPrice + 1150  // ✅ TP 1150 points above entry

// ? Short Entry Condition
shortCondition = ta.crossunder(close, smma)  // ✅ Price crosses BELOW SMMA (Short trade)

// ? Short Exit Condition
shortExit = ta.crossover(close, smma)  // ✅ Price crosses ABOVE SMMA (Close Short trade)

// ? ATR-Based Stop-Loss (Dynamic) for Short
shortStopLoss = smma + (atr * 0.75)  // ✅ Stop Loss above SMMA

// ? Fixed Take Profit for Short (1500 Points) - Updated from 2000
var float shortEntryPrice = na
var float shortTakeProfit = na
if shortCondition
    shortEntryPrice := close
    shortTakeProfit := shortEntryPrice - 1500  // ✅ TP 1500 points below entry (Updated)

// ? Plot SMMA (For Visualization)
plot(smma, title="SMMA (17)", color=color.blue)

// ? Long Entry (Allow Multiple)
if longCondition
    strategy.entry("Long", strategy.long)

// ? Long Exit Conditions (Whichever Comes First)
strategy.exit("Long TP/SL", from_entry="Long", stop=longStopLoss, limit=longTakeProfit)
if longExit
    strategy.close("Long")

// ? Short Entry (Allow Multiple)
if shortCondition
    strategy.entry("Short", strategy.short)

// ? Short Exit Conditions (Whichever Comes First)
strategy.exit("Short TP/SL", from_entry="Short", stop=shortStopLoss, limit=shortTakeProfit)
if shortExit
    strategy.close("Short")
Published by ChaoZhang on the FMZ strategy square · last modified 2025-02-19. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Dual-Direction-SMMA-Crossover-Strategy-with-ATR-Based-Risk-Management-and-Fixed-Take-Profit.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Adaptive Risk Management Strategy Based on Dynamic ATR and Moving Average CrossoverPine Script · Trend following · 2h
- Multi Dimensional Short Term Trend Predictor Technical Analysis and Volatility Adaptive Trading StrategyPine Script · Trend following · 1h
- Multi Factor Trend Price Action Strategy with Dynamic Risk Management SystemPine Script · Trend following · 2h
- Multi Indicator Dynamic Trend Following Strategy Based on EMA and SMAPine Script · Trend following · 1d
- Multi Indicator Trend Following with Oscillator Alert StrategyPine Script · Trend following · 2h
- Trend Tracking and Short term Trading Strategy Based on ADX IndicatorPine Script · Trend following · 1d