Dual EMA Crossover Breakout Strategy
The Dual EMA Crossover Breakout strategy generates buy and sell signals based on the crossover of fast and slow EMA lines, combined with trading volume breakout, candlestick patterns and price breakout filters to…
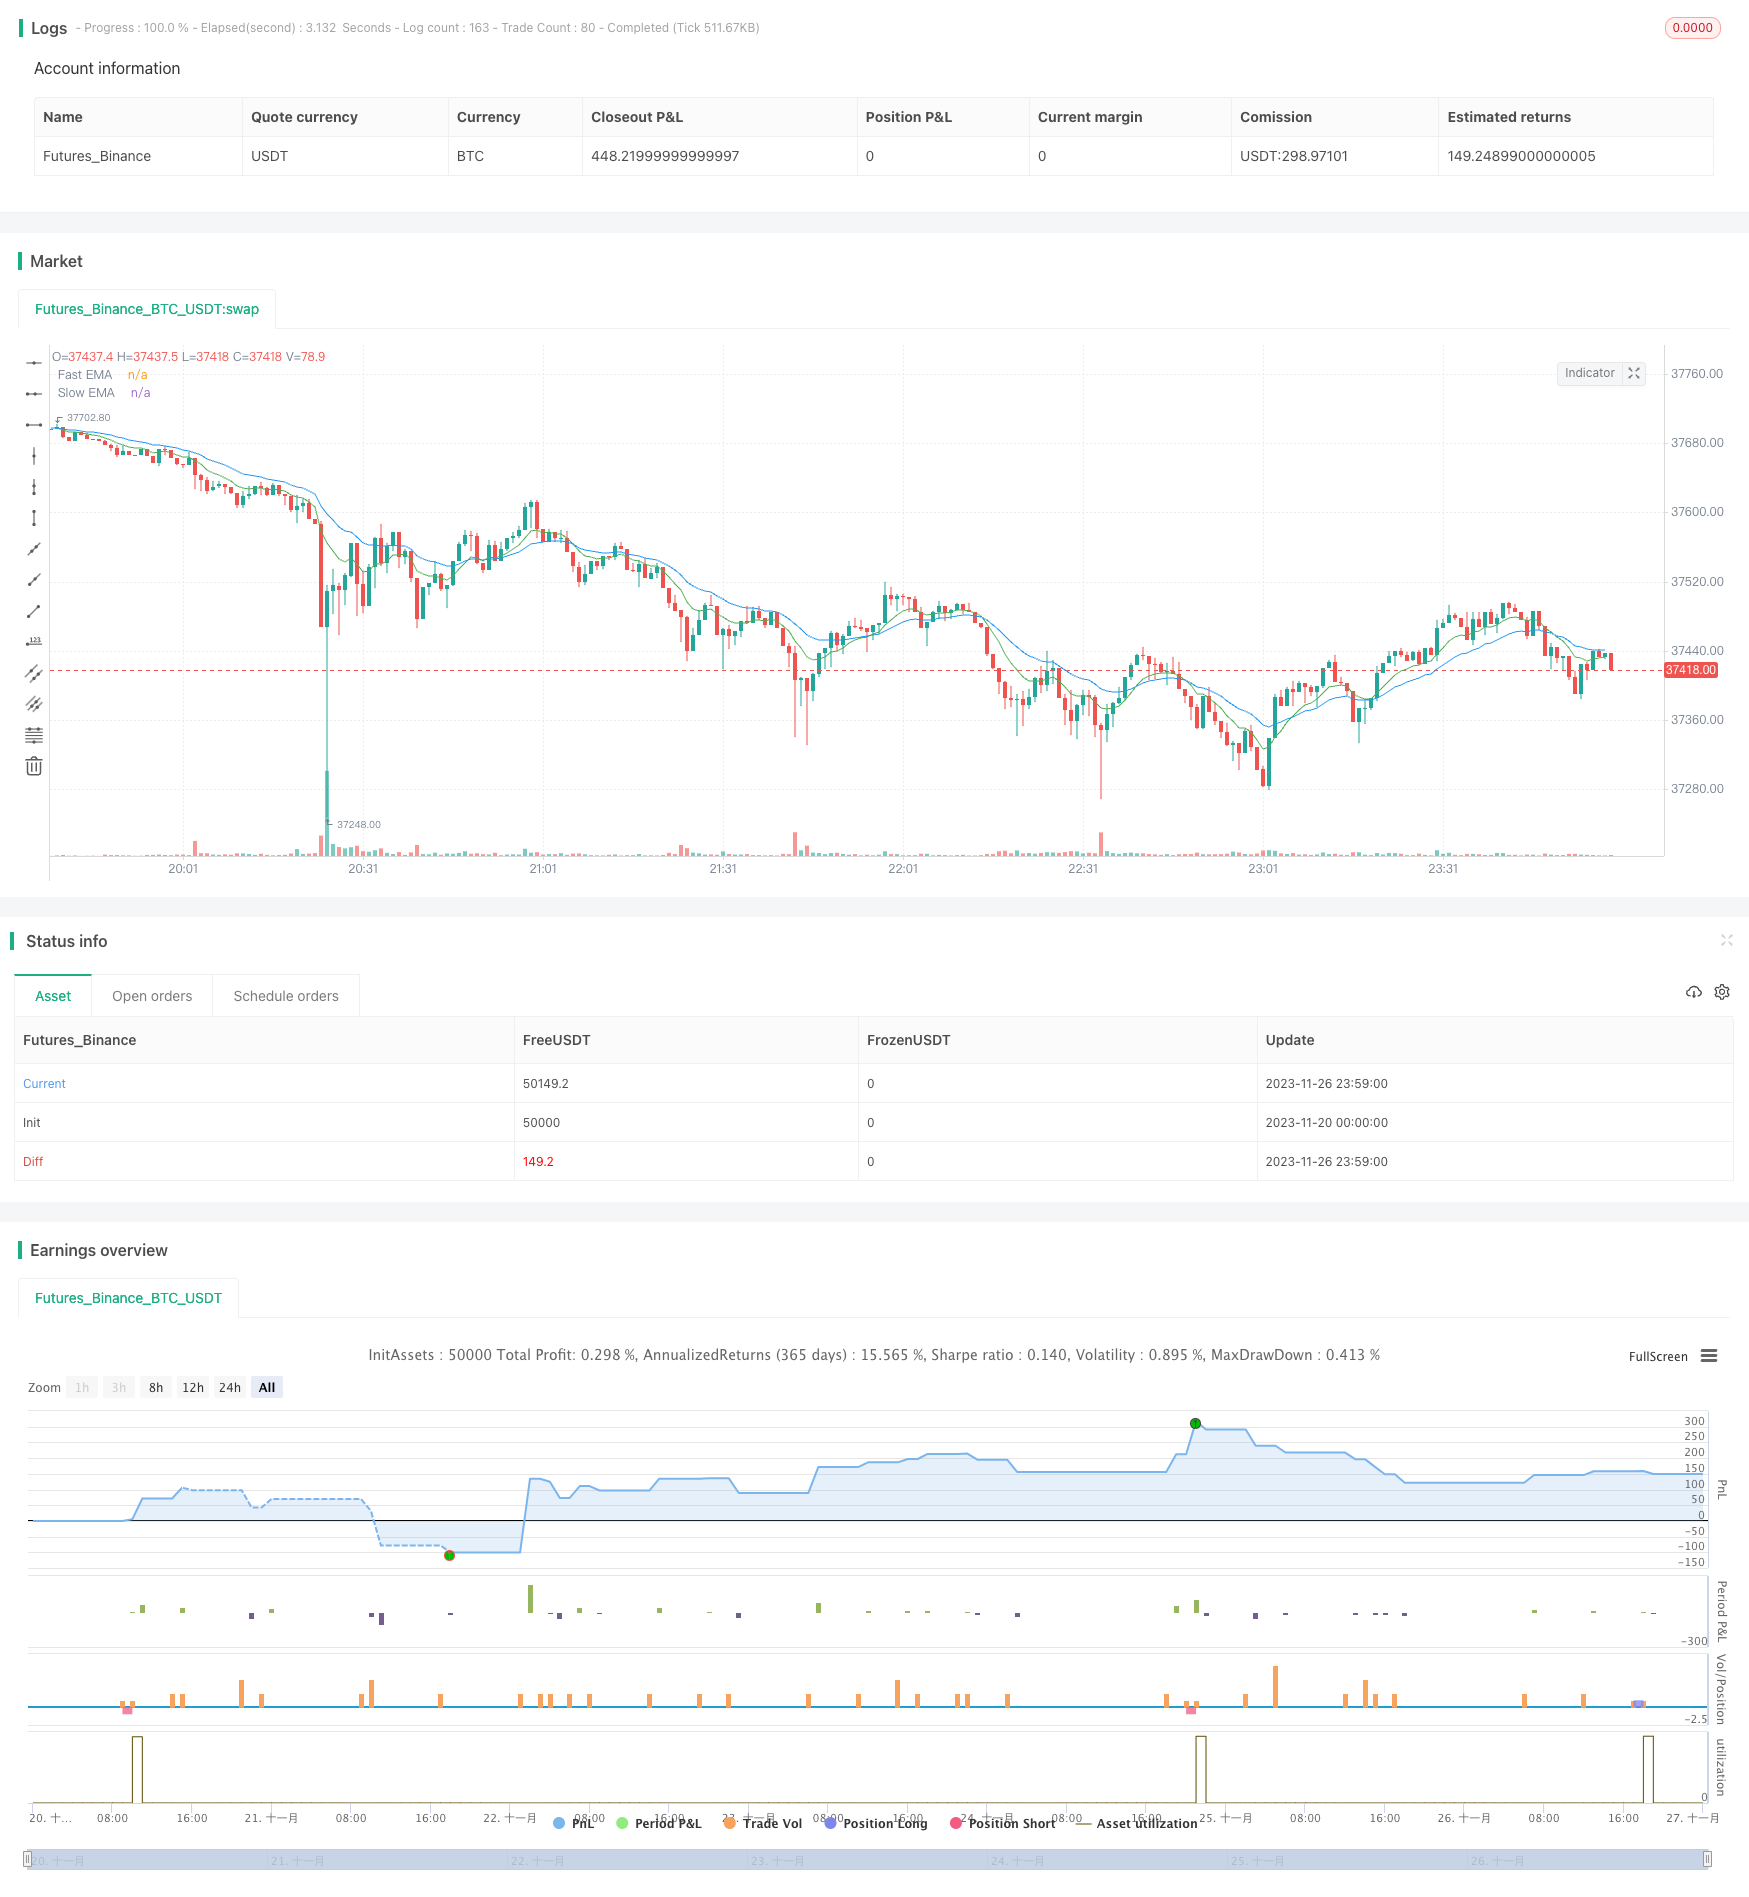
Overview
The Dual EMA Crossover Breakout strategy generates buy and sell signals based on the crossover of fast and slow EMA lines, combined with trading volume breakout, candlestick patterns and price breakout filters to improve reliability. By integrating multiple technical indicators, it aims to identify trends while controlling risks.
Principles
The core logic of the Dual EMA Crossover Breakout strategy lies in the golden crossover theory of two EMAs. The theory believes that when the shorter-term EMA crosses above the longer-term EMA, it signals an uptrend, so long positions should be established. When the shorter-term EMA crosses below the longer-term EMA, it signals a downtrend, so short positions should be established.
Specifically, the strategy first calculates the 9-period and 21-period EMAs. When the 9-EMA crosses above the 21-EMA, a "long" signal is generated. When the 9-EMA crosses below the 21-EMA, a "short" signal is generated. To filter out false signals, the following conditions are checked:
Volume condition - Volume of recent candle should exceed 85% of average volume of previous 5 candles. This filters out signals with insufficient trading volumes.
Price breakout condition - Price needs to breakout above 9-EMA as entry confirmation.
Candlestick pattern condition - Identify bullish or bearish reversal patterns, avoiding whipsaws during sideways markets.
For long positions, exits are triggered when price breaks below 9-EMA. For short positions, exits are triggered when price breaks above 9-EMA.
Advantage Analysis
By combining signals from multiple technical indicators, the Dual EMA Crossover Breakout strategy can effectively identify trends and improve win rate. The main advantages are:
Using dual EMAs to determine major trend direction is highly reliable.
Adding volume filter avoids wrong signals when volume is insufficient.
Adding candlestick pattern filter eliminates noise from range-bound markets.
Entering after price breaks EMA confirms trend.
The stop loss mechanism actively controls risks.
Risk Analysis
There are still some risks with the strategy:
EMA may generate false signals during choppy markets, causing losses. Overall trend judgement can help decide on opening positions.
Fixed EMA periods may fail to adapt to changing markets. Adaptive EMAs can be tested.
There are still probabilities of misidentifying candlestick patterns. Stop losses control risk.
The strategy may miss some price moves and have imperfect trend tracking. Parameter tuning or combining with other strategies can help.
Optimization Directions
The main optimization directions are:
Test more EMA combinations to find optimal parameters.
Add adaptive EMAs based on changing market conditions.
Optimize position sizing for different market conditions.
Incorporate more indicators like MACD, KDJ to form ensemble strategies.
Introduce machine learning models to improve robustness.
Conclusion
The Dual EMA Crossover Breakout strategy effectively identifies trends using dual EMA directional analysis, and adds multiple volume/price/pattern filters to improve efficiency while controlling risks. Easy to implement with optimization flexibility, it is a recommended breakout trend following strategy.
Source Pine Script
/*backtest
start: 2023-11-20 00:00:00
end: 2023-11-27 00:00:00
period: 1m
basePeriod: 1m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
//Author: Andrew Shubitowski
strategy("Buy/Sell Strat", overlay = true)

//Define EMAs & Crossovers (Feature 2)
a = ta.ema(close, 9)
b = ta.ema(close, 21)
crossUp = ta.crossover(a, b)
crossDown = ta.crossunder(a, b)


//Define & calc volume averages (Feature 1)
float volAvg = 0
for i = 1 to 5
    volAvg := volAvg + volume[i]
volAvg := volAvg / 5

//Define candlestick pattern recongition (Feature 4)
bool reversalPatternUp = false
bool reversalPatternDown = false
if (close > close[1] and close[1] > close [2] and close[3] > close[2] and close > close[3])
    reversalPatternUp := true

if (close < close[1] and close[1] < close [2] and close[3] < close[2] and close < close[3])
    reversalPatternDown := true

//Execute trade (Feature 3 + 5)
if (crossUp)
    strategy.entry("long", strategy.long, when = ((volume * 0.85) > volAvg and close > a and reversalPatternUp == true))

if (crossDown)
    strategy.entry("short", strategy.short, when = ((volume * 0.85) > volAvg and close < a and reversalPatternDown == true))

//Exit strategy (New Feature)
close_condition_long = close < a
close_condition_short = close > a
if (close_condition_long)
    strategy.close("long")

if (close_condition_short)
    strategy.close("short")

//plot the EMAs
plot(a, title = "Fast EMA", color = color.green)
plot(b, title = "Slow EMA", color = color.blue)


//Some visual validation parameters
//plotchar(volAvg, "Volume", "", location.top, color.aqua) //*TEST* volume calc check
//plotshape(reversalPatternUp, style = shape.arrowup, color = color.aqua) //*TEST* reversal check
//plotshape(reversalPatternDown, style = shape.arrowup, location = location.belowbar, color = color.red) //*TEST* reversal check
Published by ChaoZhang on the FMZ strategy square · last modified 2023-11-28. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Dual-EMA-Crossover-Breakout-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Adaptive Multi Period Trading Strategy Based on Wave Trend Momentum BreakoutPine Script · Breakout · 2h
- Dynamic Bollinger Bands Breakout Quantitative Trading StrategyPine Script · Breakout · 2d
- Dynamic Dual Moving Average Breakthrough Trading System Dynamic Dual Moving Average Breakthrough Trading SystemPine Script · Breakout · 1d
- Flexible Long Short Trading Strategy Based on Keltner ChannelsPine Script · Breakout · 1d
- Momentum Breakout Trading Strategy 435896Pine Script · Breakout · 1d
- Momentum Breakthrough EMA StrategyPine Script · Breakout · 1d