Strategy vault / Trend following
Dual EMA Crossover Oscillation Tracking Strategy
The Dual EMA Crossover Oscillation Tracking strategy is a strategy that identifies trends using the EMA indicator and tracks oscillations during volatile market conditions. This strategy incorporates both the…
Overview
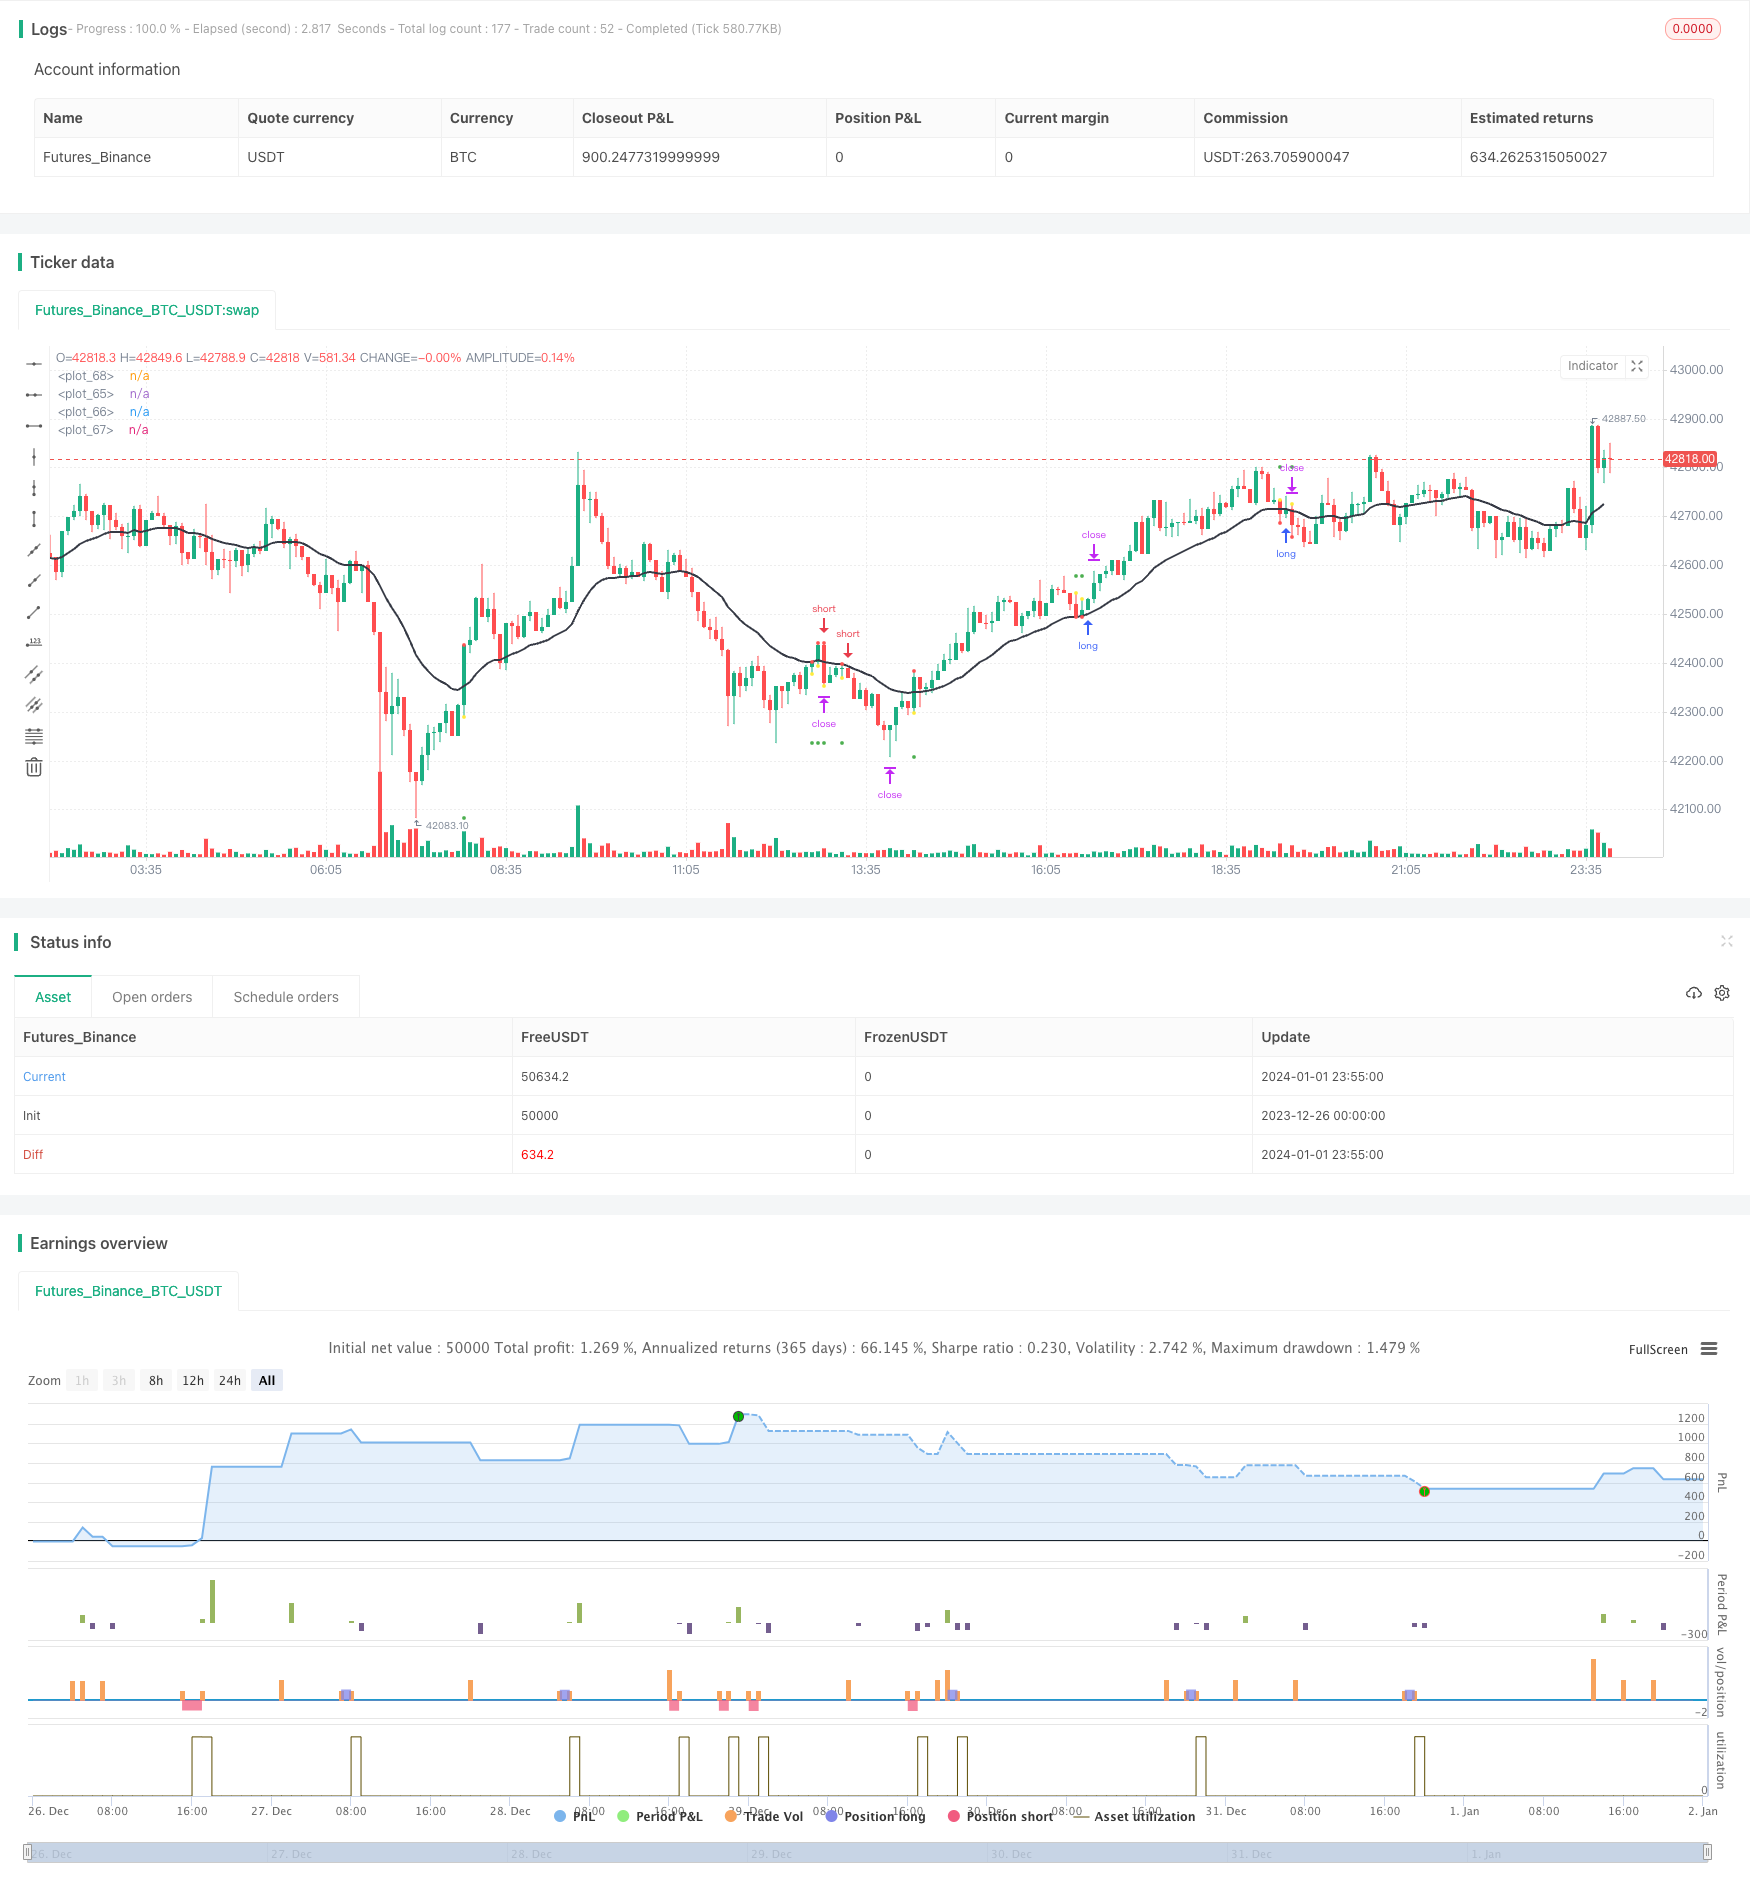
The Dual EMA Crossover Oscillation Tracking strategy is a strategy that identifies trends using the EMA indicator and tracks oscillations during volatile market conditions. This strategy incorporates both the concepts of trend tracking and oscillation capturing. It aims to achieve better returns by conducting long-term tracking during strong trends and short-term trading during oscillations.
Strategy Logic
This strategy uses the 20-period EMA as an indicator for judging trends. When the price crosses above the EMA, it signals an upward trend, and when the price crosses below, it signals a downward trend.
When the price crosses above the EMA, a long position is entered using the highest price over the past 20 periods as the take profit and the lowest low since the crossover as the stop loss. When the price crosses below the EMA, a short position is entered using the lowest price over the past 20 periods as the take profit and the highest high since the crossover as the stop loss.
At the same time, the strategy also checks if the ADX is above 30. Trades are only taken when the trend is strong enough, i.e. when the ADX is higher than 30. This avoids stop outs during market oscillations.
During open trades, the trailing stop continues to adjust based on market conditions to lock in more profits.
Advantage Analysis
This strategy combines the advantages of both trend tracking and oscillation trading. It can produce higher returns during trending markets and more consistent returns during oscillations. The adaptability is strong.
The use of EMA also keeps the parameters simple, lowering the risks of overoptimization and ensuring stability.
Risk Analysis
The main risk of this strategy is the possibility of more frequent stop outs during intensified oscillations. This is where the ADX comes into play. By disabling trading when ADX is low, losses in the absence of a clear trend can be avoided.
In addition, proper stop loss placement is also key. Excessively wide stops may increase single trade loss amount. Excessively tight stops may be too sensitive and increase stop out probability. A balance needs to be found between profit targets and stop loss risks.
Optimization Directions
Possible optimizations for this strategy include:
Testing more EMA periods to find the optimal combination.
Optimizing ADX parameters including the ADX period and threshold values.
Improving the profit taking and stop loss algorithms, for example by introducing dynamic stops.
Combining additional indicators like KDJ and MACD to create a multi-indicator confirmation system.
Summary
In summary, the Dual EMA Crossover Oscillation Tracking strategy is a highly practical strategy. It combines the strengths of both trend trading strategies and oscillation strategies. It can be used for both long-term tracking and short-term trading. Further improvements in performance can be achieved through parameter optimization and adding confirming indicators. It suits investors with some degree of analytical capabilities regarding market conditions.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 14 | ADX period |
| v_input_2 | 30 | adxMin |
| v_input_3 | 20 | emaLength |
| v_input_4 | 20 | highPeriod |
| v_input_5 | false | Custom Backtesting Dates |
| v_input_6 | 2018 | Backtest Start Year |
| v_input_7 | 3 | Backtest Start Month |
| v_input_8 | 6 | Backtest Start Day |
| v_input_9 | 8 | Backtest Start Hour |
| v_input_10 | 2018 | Backtest Stop Year |
| v_input_11 | 12 | Backtest Stop Month |
| v_input_12 | 14 | Backtest Stop Day |
| v_input_13 | 14 | Backtest Stop Hour |
Source Pine Script
/*backtest
start: 2023-12-26 00:00:00
end: 2024-01-02 00:00:00
period: 5m
basePeriod: 1m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=2
strategy("Linda Raschke's Holy Grail", shorttitle="RHG", default_qty_type = strategy.percent_of_equity, default_qty_value = 100, overlay = true)
adxlen = input(14, title="ADX period")
adxMin = input(30)
dilen = adxlen
f_highest(_src, _length)=>
    _adjusted_length = _length < 1 ? 1 : _length
    _value = _src
    for _i = 0 to (_adjusted_length-1)
        _value := _src[_i] >= _value ? _src[_i] : _value
    _return = _value

f_lowest(_src, _length)=>
    _adjusted_length = _length < 1 ? 1 : _length
    _value = _src
    for _i = 0 to (_adjusted_length-1)
        _value := _src[_i] <= _value ? _src[_i] : _value
    _return = _value

dirmov(len) =>
	up = change(high)
	down = -change(low)
	plusDM = na(up) ? na : (up > down and up > 0 ? up : 0)
    minusDM = na(down) ? na : (down > up and down > 0 ? down : 0)
	truerange = rma(tr, len)
	plus = fixnan(100 * rma(plusDM, len) / truerange)
	minus = fixnan(100 * rma(minusDM, len) / truerange)
	[plus, minus]

adx(dilen, adxlen) =>
	[plus, minus] = dirmov(dilen)
	sum = plus + minus
	adx = 100 * rma(abs(plus - minus) / (sum == 0 ? 1 : sum), adxlen)

emaLength = input(20)
curEma = ema(close, emaLength)
highPeriod = input(20)
d = na

takeProfitLong = highest(high, highPeriod)
stopLossLong = f_lowest(low, barssince(low >= curEma))

if strategy.position_size == 0
    if adx(dilen, adxlen) <= adxMin or high < curEma
        strategy.cancel("Long")
    if adx(dilen, adxlen) > adxMin and low < curEma and high > curEma and curEma > curEma[highPeriod / 2] and curEma > curEma[highPeriod] and takeProfitLong > high
        strategy.order("Long", strategy.long, stop = high)
        strategy.exit("Exit", "Long", limit = takeProfitLong, stop = stopLossLong)
        d := high

takeProfitShort = lowest(low, highPeriod)
stopLossShort = f_highest(high, barssince(high <= curEma))

if strategy.position_size == 0
    if adx(dilen, adxlen) <= adxMin or low > curEma
        strategy.cancel("Short")
    if adx(dilen, adxlen) > adxMin and high > curEma and low < curEma and curEma < curEma[highPeriod / 2] and curEma < curEma[highPeriod] and takeProfitShort < low
        strategy.order("Short", strategy.short, stop = low)
        strategy.exit("Exit", "Short", limit = takeProfitShort, stop = stopLossShort)
        d := low


strategy.close("Exit")

plot(d == high ? stopLossLong : d == low ? stopLossShort : na, style = circles, linewidth = 4, color = red)
plot(d == high ? takeProfitLong : d == low ? takeProfitShort : na, style = circles, linewidth = 4, color = green)
plot(d, style = circles, linewidth = 4, color = yellow)
plot(curEma, color = black, linewidth = 2)

// === Backtesting Dates ===
testPeriodSwitch = input(false, "Custom Backtesting Dates")
testStartYear = input(2018, "Backtest Start Year")
testStartMonth = input(3, "Backtest Start Month")
testStartDay = input(6, "Backtest Start Day")
testStartHour = input(08, "Backtest Start Hour")
testPeriodStart = timestamp(testStartYear,testStartMonth,testStartDay,testStartHour,0)
testStopYear = input(2018, "Backtest Stop Year")
testStopMonth = input(12, "Backtest Stop Month")
testStopDay = input(14, "Backtest Stop Day")
testStopHour = input(14, "Backtest Stop Hour")
testPeriodStop = timestamp(testStopYear,testStopMonth,testStopDay,testStopHour,0)
testPeriod() =>
    time >= testPeriodStart and time <= testPeriodStop ? true : false
isPeriod = testPeriodSwitch == true ? testPeriod() : true
// === /END
if not isPeriod
    strategy.cancel_all()
    strategy.close_all()
Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-03. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Dual-EMA-Crossover-Oscillation-Tracking-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- EMA SMA Multi Indicator Comprehensive Trend Following StrategyPine Script · Trend following · 1h
- Multi Indicator Dynamic Trend Following Strategy Based on EMA and SMAPine Script · Trend following · 1d
- Super Trend Triple StrategyPine Script · Trend following · 1h
- Dual EMA Crossover Trend Following Strategy with ATR and ADX FiltersPine Script · Trend following · 1d
- Dynamic Trend Identification Strategy with Exponential Moving Average and Adaptive Volatility ThresholdPine Script · Trend following · 1h
- EMA Crossover Strategy with Dynamic Trailing Stop LossPine Script · Trend following · 2d