Strategy vault / Trend following
Dual EMA Crossover Trend Following Strategy with Risk Management and Time Filtering System
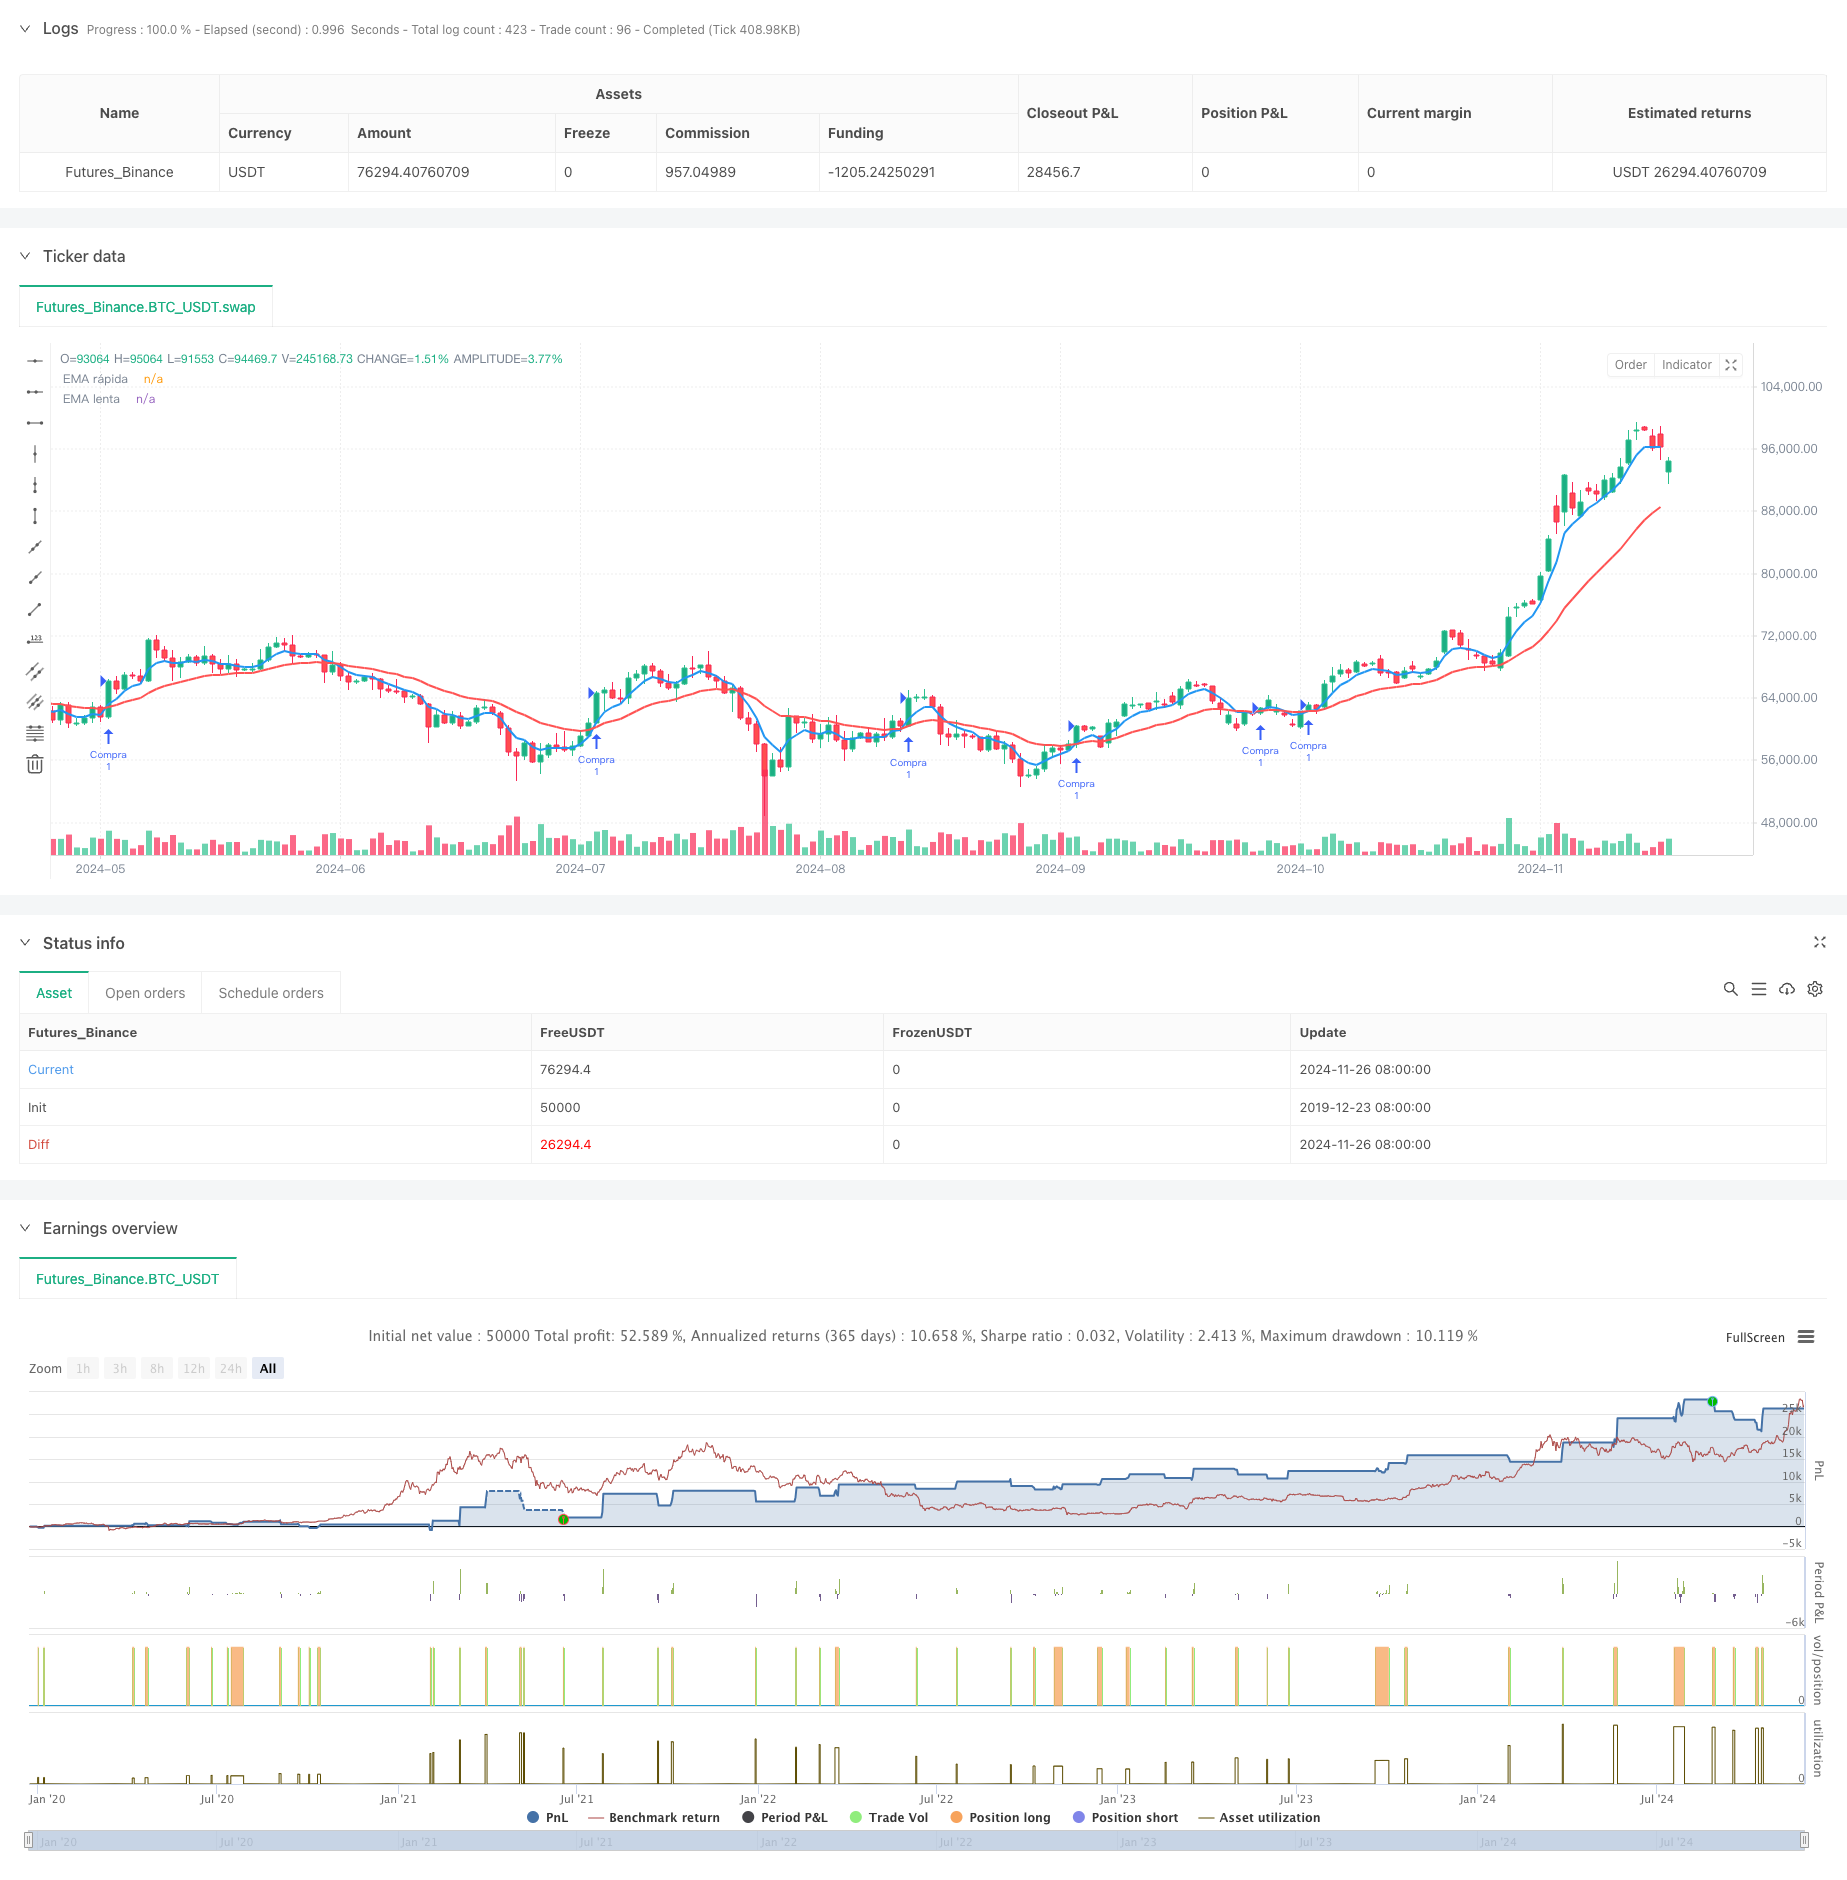
This strategy is a complete trading system that combines dual EMA crossover signals, stop-loss/take-profit management, and time filtering. The core strategy is based on the crossover of fast and slow exponential…
Overview
This strategy is a complete trading system that combines dual EMA crossover signals, stop-loss/take-profit management, and time filtering. The core strategy is based on the crossover of fast and slow exponential moving averages (EMA) to capture market trends, with risk control through Take Profit and Stop Loss settings. Additionally, the strategy includes time filtering functionality that allows traders to execute trades within specific time ranges.
Strategy Principles
The strategy operates based on the following core mechanisms:
- Uses two EMAs with different periods (default 5 and 21)
- Generates long signals when fast EMA crosses above slow EMA
- Generates short signals when fast EMA crosses below slow EMA
- Each trade has percentage-based stop-loss and take-profit levels
- Trading direction can be configured for: long-only, short-only, or both
- Includes time filtering to execute trades only within specified timeframes
- System generates alerts at key moments (entry, stop-loss/take-profit hits)
Strategy Advantages
- Systematic risk management: Clear risk control through preset stop-loss and take-profit levels
- Flexible parameter configuration: Traders can adjust EMA periods and risk levels
- Directional freedom: Options for unidirectional or bidirectional trading
- Time management capability: Avoids trading during unfavorable periods
- Real-time alert system: Helps traders receive timely signals and risk notifications
- Complete position management: Automated entry and exit without manual intervention
Strategy Risks
- Choppy market risk: May generate frequent false signals in ranging markets
- Slippage risk: Actual stop-loss/take-profit prices may deviate during high volatility
- Parameter sensitivity: Strategy performance heavily depends on EMA period selection
- Trend dependency: May underperform in non-trending markets
- Money management risk: Fixed percentage stops may not be flexible enough in certain conditions
Optimization Directions
- Add market environment filtering:
- Incorporate volatility indicators for different market states
- Implement trend strength filters to avoid false breakouts
- Dynamic parameter adjustment:
- Adjust stop-loss/take-profit levels based on market volatility
- Modify EMA periods according to trend strength
- Enhanced risk management:
- Add trailing stop functionality to protect profits
- Implement scaling in/out mechanisms
- Improve entry precision:
- Incorporate volume indicators to confirm signal validity
- Add supplementary technical indicators for confirmation
Summary
This is a well-designed trend-following strategy that combines a moving average system, risk management, and time filtering to provide a comprehensive trading solution. The strategy offers high configurability, suitable for traders with different risk preferences. Through the suggested optimization directions, there is room for further improvement. The key is to adjust parameters based on actual market conditions and personal trading objectives while maintaining strict risk control.
Source Pine Script
/*backtest
start: 2019-12-23 08:00:00
end: 2024-11-27 08:00:00
period: 1d
basePeriod: 1d
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("Estrategia Cruce de EMAs con: Stop Loss, Take Profit, Días de Operación y Alertas (Modificables)", overlay=true, commission_value = 0.2, process_orders_on_close = true, initial_capital = 1000)

// Parámetros de las EMAs
emaRapidaLen = input.int(5, title="Periodo EMA rápida")
emaLentaLen = input.int(21, title="Periodo EMA lenta")

// Parámetros de Stop Loss y Take Profit
stopLoss = input.float(3.0, title="Stop Loss (%)", step=0.1) / 100
takeProfit = input.float(6.0, title="Take Profit (%)", step=0.1) / 100

// Tipo de operación: Largo, Corto o Ambos
operacion = input.string(title="Tipo de operación", defval="Largo", options=["Largo", "Corto", "Ambos"])

// Parámetros de la duración de la estrategia (días)
diasInicio = input(timestamp("2009-01-03 00:00"), title="Fecha de inicio (YYYY-MM-DD HH:MM)")
diasFin = input(timestamp("2024-09-11 00:00"), title="Fecha de fin (YYYY-MM-DD HH:MM)")

// Comprobar si estamos dentro del rango de días definido
dentroDeRango = true

// Cálculo de las EMAs
emaRapida = ta.ema(close, emaRapidaLen)
emaLenta = ta.ema(close, emaLentaLen)

// Condiciones para cruce de EMAs
cruceAlcista = ta.crossover(emaRapida, emaLenta)
cruceBajista = ta.crossunder(emaRapida, emaLenta)

// Operaciones en Largo (solo si estamos en el rango de días definido)
if dentroDeRango and (operacion == "Largo" or operacion == "Ambos") and cruceAlcista
    strategy.entry("Compra", strategy.long)
    alert("Posición larga abierta: Cruce alcista de EMAs", alert.freq_once_per_bar_close)

// Operaciones en Corto (solo si estamos en el rango de días definido)
if dentroDeRango and (operacion == "Corto" or operacion == "Ambos") and cruceBajista
    strategy.entry("Venta", strategy.short)
    alert("Posición corta abierta: Cruce bajista de EMAs", alert.freq_once_per_bar_close)

// Cálculo del Stop Loss y Take Profit para largos
if (strategy.position_size > 0 and strategy.opentrades.entry_id(strategy.opentrades - 1) == "Compra")
    strategy.exit("Cerrar Compra", "Compra", stop=strategy.position_avg_price * (1 - stopLoss), limit=strategy.position_avg_price * (1 + takeProfit))
    alert("Posición larga cerrada: Alcanzado Stop Loss o Take Profit", alert.freq_once_per_bar_close)

// Cálculo del Stop Loss y Take Profit para cortos
if (strategy.position_size < 0 and strategy.opentrades.entry_id(strategy.opentrades - 1) == "Venta")
    strategy.exit("Cerrar Venta", "Venta", stop=strategy.position_avg_price * (1 + stopLoss), limit=strategy.position_avg_price * (1 - takeProfit))
    alert("Posición corta cerrada: Alcanzado Stop Loss o Take Profit", alert.freq_once_per_bar_close)

// Plot de las EMAs
plot(emaRapida, color=color.blue, title="EMA rápida", linewidth = 2)
plot(emaLenta, color=color.red, title="EMA lenta", linewidth = 2)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-11-29. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Dual-EMA-Crossover-Trend-Following-Strategy-with-Risk-Management-and-Time-Filtering-System.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- 200 EMA VWAP MFI Trend Following StrategyPine Script · Trend following · 1d
- 4 EMA Trend StrategyPine Script · Trend following · 1d
- ADX MA and EMA Long Only Trend Tracking StrategyPine Script · Trend following · 1d
- ATR Dynamic Trend Following and EMA Crossover Trading StrategyPine Script · Trend following · 1d
- ATR and Moving Average Crossover Hybrid StrategyPine Script · Trend following · 1h
- ATR and T3 Moving Average StrategyPine Script · Trend following · 5m